Tribunals and Commissions judgments

1767 Tribunals and Commissions judgments explained in plain English: what was decided, the law applied and why it matters. Page 14 of 74.

Form 67 Late Filing | Directory Compliance Permits FTC Claim Under India-USA DTAA : ITAT Pune
Case Law Analysis
|Income Tax Appellate Tribunal

Form 67 Late Filing | Directory Compliance Permits FTC Claim Under India-USA DTAA : ITAT Pune

The ITAT Pune has ruled that failure to file Form 67 by the due date does not extinguish the right to claim Foreign Tax Credit under the India-USA DTAA, as compliance is procedural and directory, not mandatory. This empowers taxpayers with legitimate foreign tax payments to secure credit even with technical delays, reinforcing substance over form in international tax disputes.
Section 80G IT Act | Teaching Vedas as 'Knowledge' Constitutes Charitable Purpose, Not Religious Activity: ITAT Panaji
Case Law Analysis
|Income Tax Appellate Tribunal

Section 80G IT Act | Teaching Vedas as 'Knowledge' Constitutes Charitable Purpose, Not Religious Activity: ITAT Panaji

ITAT Panaji rules that imparting Vedic education for public benefit qualifies as a charitable purpose under Section 80G, overturning the CIT's classification of it as a religious activity. The decision clarifies that 'Vedas' mean 'knowledge' and emphasizes Hinduism as a way of life, impacting trusts engaged in ancient Indian studies and similar educational activities.

Service Tax | Ocean Freight Markup Not Taxable as 'Business Support Service' Under Finance Act, 1994 : CESTAT Chandigarh
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

Service Tax | Ocean Freight Markup Not Taxable as 'Business Support Service' Under Finance Act, 1994 : CESTAT Chandigarh

CESTAT Chandigarh holds that when a freight forwarder purchases ocean freight on a principal-to-principal basis and resells it with a markup, the transaction does not constitute a taxable 'Business Support Service' under the Finance Act, 1994. This clarifies the scope of taxable auxiliary services in logistics and benefits freight forwarders operating as principals, not agents, in international shipping arrangements.

Section 147 IT Act | Reassessment Cannot Expand to Unrelated Disallowances Under Section 40A(3) Without Fresh Reasons : ITAT Delhi
Case Law Analysis
|Income Tax Appellate Tribunal

Section 147 IT Act | Reassessment Cannot Expand to Unrelated Disallowances Under Section 40A(3) Without Fresh Reasons : ITAT Delhi

ITAT Delhi has ruled that reassessment proceedings initiated under Section 147 for cash deposits cannot be used to impose disallowances under Section 40A(3) for unrelated cash payments to suppliers. This reinforces that reassessment is confined to the specific reasons recorded at reopening, protecting assessees from collateral tax demands without fresh evidence. A critical safeguard for businesses facing broad-based reassessments.

Section 69A IT Act | Cash Withdrawals from Disclosed Accounts Cannot Be Taxed as Unexplained Money Without Evidence of Undisclosed Income: ITAT Surat
Case Law Analysis
|Income Tax Appellate Tribunal

Section 69A IT Act | Cash Withdrawals from Disclosed Accounts Cannot Be Taxed as Unexplained Money Without Evidence of Undisclosed Income: ITAT Surat

ITAT Surat holds that cash withdrawals from disclosed bank accounts cannot be treated as unexplained money under Section 69A of the Income Tax Act unless there is evidence linking such withdrawals to undisclosed income. The ruling underscores that mere cash withdrawals, without proof of unaccounted sources, do not justify tax additions, reinforcing the need for concrete evidence in best judgment assessments.

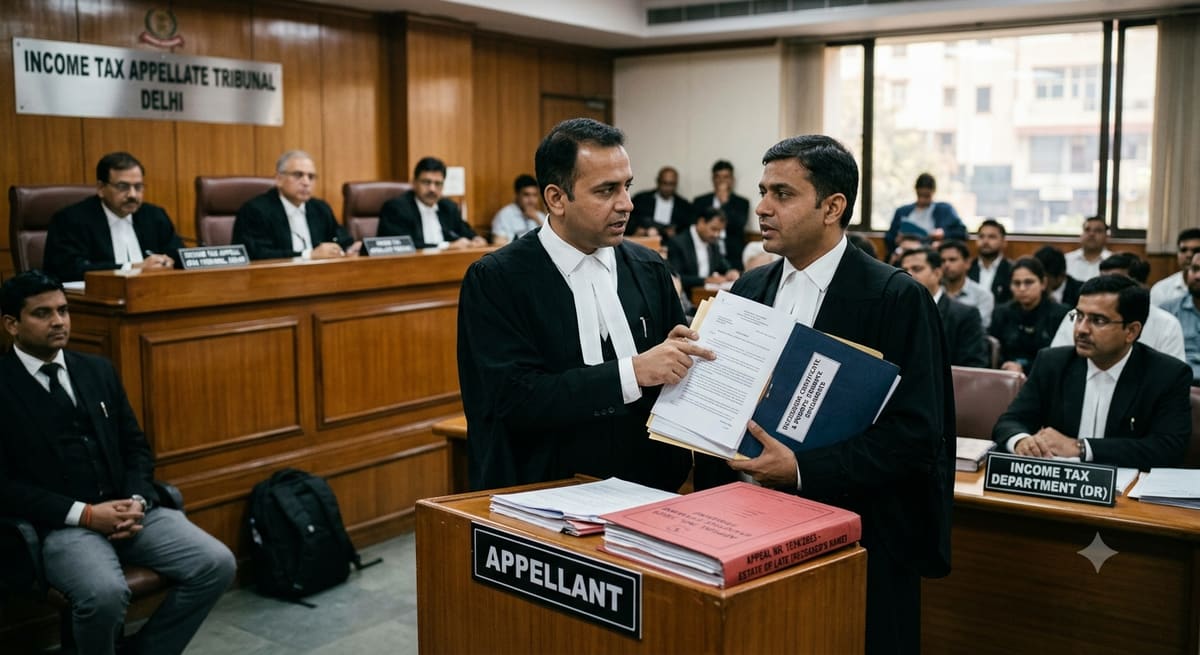
Natural Justice in Tax Appeals | ITAT Delhi Quashes CIT(A) Order for Denying Fair Hearing Under Section 250(6) IT Act
Case Law Analysis
|Income Tax Appellate Tribunal

Natural Justice in Tax Appeals | ITAT Delhi Quashes CIT(A) Order for Denying Fair Hearing Under Section 250(6) IT Act

ITAT Delhi set aside a CIT(A) order for violating principles of natural justice by deciding an appeal ex-parte without granting the assessee an effective hearing. The Tribunal ruled that mere non-submission of documents does not justify bypassing quasi-judicial obligations under Section 250(6) of the Income Tax Act, emphasizing procedural fairness in tax adjudication.

DTAA Article 15 | Foreign Salary Taxable Only in Country of Service Rendering : ITAT Delhi Overrules Domestic Taxation
Case Law Analysis
|Income Tax Appellate Tribunal

DTAA Article 15 | Foreign Salary Taxable Only in Country of Service Rendering : ITAT Delhi Overrules Domestic Taxation

ITAT Delhi clarifies that under Article 15 of the India-Australia DTAA, salary for services rendered abroad is taxable exclusively in the country where the services are performed, not in India. The ruling shields foreign-earned income of Indian residents from double taxation, reinforcing DTAA supremacy over domestic tax laws.

HSN Chapter Note 4 | Crushing and Screening of Iron Ore Not 'Manufacture' - Exemption for Ores Upheld : CESTAT Kolkata
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

HSN Chapter Note 4 | Crushing and Screening of Iron Ore Not 'Manufacture' - Exemption for Ores Upheld : CESTAT Kolkata

The CESTAT Kolkata rules that mere size reduction and segregation of iron ore through crushing and screening do not amount to manufacture under HSN Chapter Note 4, preserving the unconditional exemption for raw ores under Notification No. 12/2012-CE. This clarifies the boundary between mining activities and taxable production, directly impacting miners, contractors, and tax authorities handling ore-based supply chains.

Section 11/12 IT Act | Gross Receipts of Charitable Trusts Not Taxable Without Allowance of Admissible Expenses: ITAT Mumbai
|Income Tax Appellate Tribunal

Section 11/12 IT Act | Gross Receipts of Charitable Trusts Not Taxable Without Allowance of Admissible Expenses: ITAT Mumbai

ITAT Mumbai rules that denial of exemption under Sections 11/12 of the Income Tax Act does not permit taxation of gross receipts; allowable expenses must be computed under normal provisions. The ruling reinforces that technical defaults like delayed filings cannot justify taxing gross income without deducting legitimate expenses for charitable trusts.

Section 194IA | Inadvertent PAN Error in Form 26QB Does Not Deny TDS Credit When Tax Is Properly Paid : ITAT Ahmedabad
Case Law Analysis
|Income Tax Appellate Tribunal

Section 194IA | Inadvertent PAN Error in Form 26QB Does Not Deny TDS Credit When Tax Is Properly Paid : ITAT Ahmedabad

When a buyer mistakenly enters their own PAN in the seller’s column on Form 26QB, the ITAT rules that TDS credit cannot be denied if the tax was duly deposited and no double claim exists. This protects purchasers from administrative penalties due to clerical errors, reinforcing that substance must prevail over form in tax compliance.

Customs Act Section 111(d) | Invalid PSIC Due to Unauthorized Agency Jurisdiction Does Not Render Goods 'Prohibited' If Post-Shipment Inspection Confirms Compliance : CESTAT Chandigarh
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

Customs Act Section 111(d) | Invalid PSIC Due to Unauthorized Agency Jurisdiction Does Not Render Goods 'Prohibited' If Post-Shipment Inspection Confirms Compliance : CESTAT Chandigarh

CESTAT Chandigarh rules that a Pre-Shipment Inspection Certificate issued by an unauthorized agency does not automatically classify imported goods as 'prohibited' under Section 111(d), provided a subsequent DGFT-approved post-shipment inspection verifies safety and regulatory compliance. This shields importers from confiscation where goods are legally sound but administratively misdocumented, reinforcing that procedural flaws cannot override substantive safety verification.

Service Tax on Export of Services | Recipient’s Location Outside India Determines Tax Exemption : CESTAT Kolkata
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

Service Tax on Export of Services | Recipient’s Location Outside India Determines Tax Exemption : CESTAT Kolkata

CESTAT Kolkata rules that services rendered in India to a foreign recipient qualify as 'export of services' and are exempt from service tax if payment is received in foreign exchange. The ruling sets aside a ₹4.55 crore tax demand, reinforcing that taxability hinges on the recipient’s location, not the place of performance.

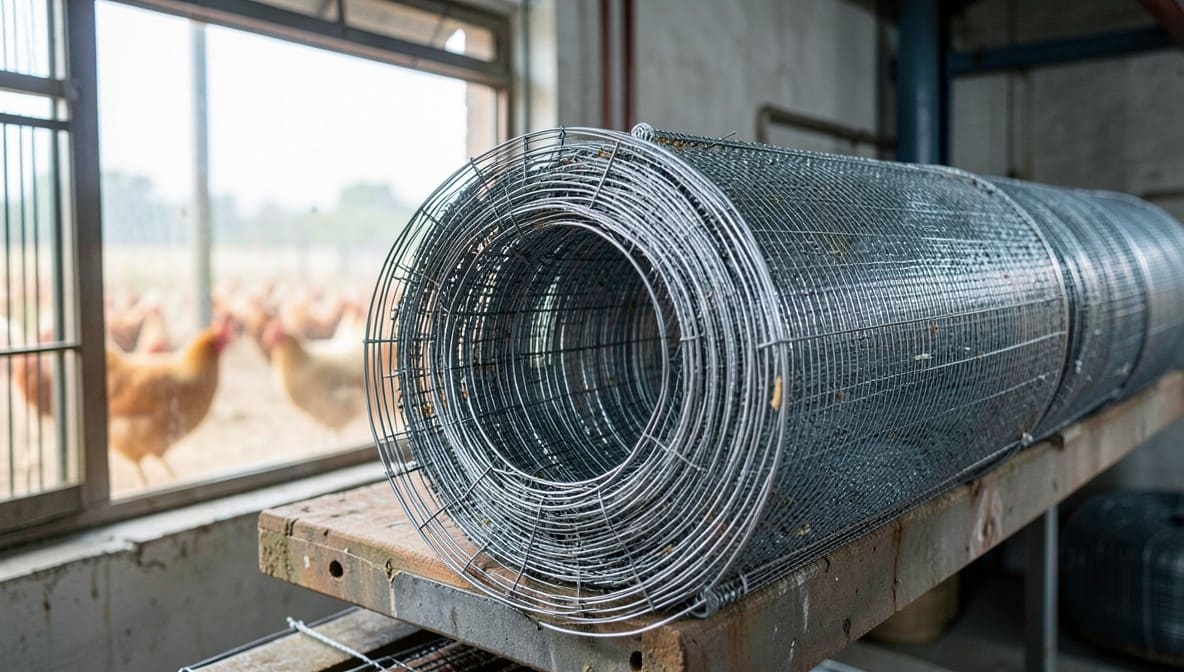
HSN 7314 vs. 8436 | GI Welded Wire Mesh for Poultry Cages Classifiable as Iron/Steel Article, Not Poultry Machinery: CESTAT Hyderabad
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

HSN 7314 vs. 8436 | GI Welded Wire Mesh for Poultry Cages Classifiable as Iron/Steel Article, Not Poultry Machinery: CESTAT Hyderabad

CESTAT Hyderabad rules that galvanized iron welded wire mesh used in poultry cages falls under HSN 7314 (iron/steel articles) rather than HSN 8436 (poultry machinery), directly impacting customs duty liability. The decision clarifies classification disputes for manufacturers and importers of similar industrial materials.

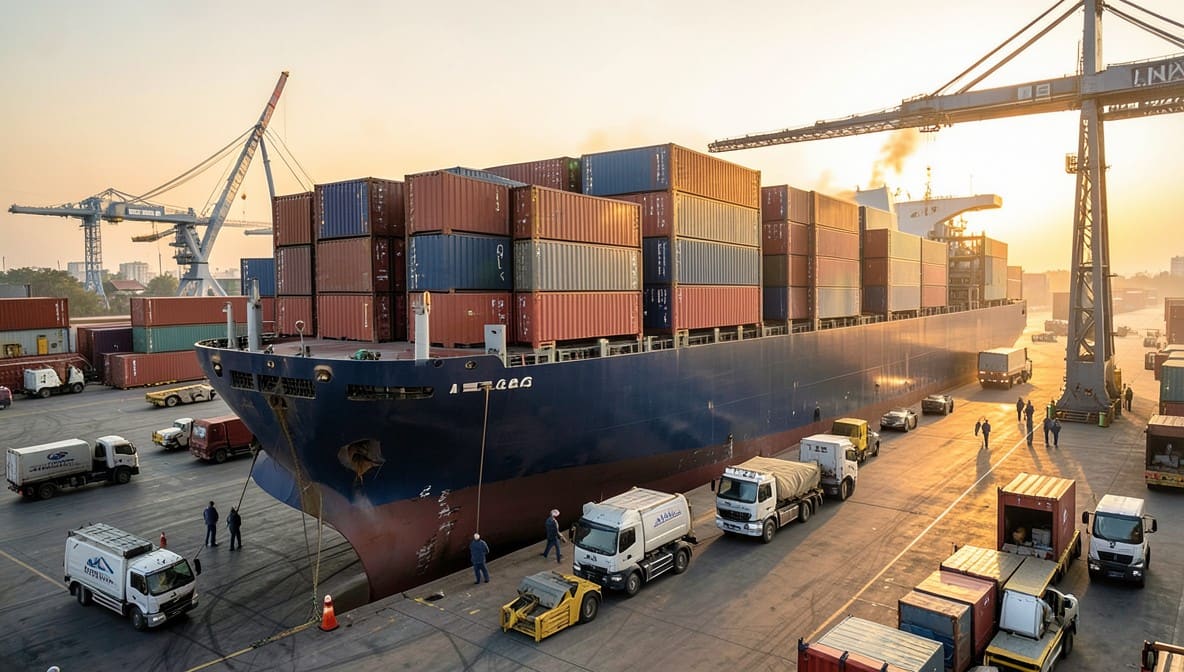
Article 8 India-China DTAA | Inland Haulage Charges Integral to International Shipping Profits Are Tax-Exempt : ITAT Mumbai
|Income Tax Appellate Tribunal

Article 8 India-China DTAA | Inland Haulage Charges Integral to International Shipping Profits Are Tax-Exempt : ITAT Mumbai

The ITAT Mumbai has ruled that Inland Haulage Charges received by non-resident shipping companies are exempt under Article 8 of the India-China DTAA because they are inseparable from the operation of ships in international traffic. This clarifies that ancillary land-based logistics supporting global shipping routes qualify for treaty protection, significantly benefiting foreign container lines operating in India.

Section 69A Income Tax Act | Fraudulent PAN Misuse Requires De Novo Adjudication on Unexplained Investments: ITAT Delhi
Case Law Analysis
|Income Tax Appellate Tribunal

Section 69A Income Tax Act | Fraudulent PAN Misuse Requires De Novo Adjudication on Unexplained Investments: ITAT Delhi

ITAT Delhi remands a case for fresh adjudication under Section 69A after finding fraudulent third-party misuse of the assessee’s PAN, limiting tax liability to just 1% commission income. The ruling underscores the need for proper assessment of unexplained investments before imposing penalties, offering relief to taxpayers facing wrongful additions due to identity fraud.

Transfer Pricing | Arm's Length Pricing Precludes Further Profit Attribution to Permanent Establishment: ITAT Delhi
Case Law Analysis
|Income Tax Appellate Tribunal

Transfer Pricing | Arm's Length Pricing Precludes Further Profit Attribution to Permanent Establishment: ITAT Delhi

The ITAT Delhi has ruled that once transfer pricing adjustments establish arm's length pricing for transactions with an associated enterprise, no additional profits can be attributed to a permanent establishment in India. This reinforces the principle that PE profit allocation must flow from the actual economic activity and pricing, not from speculative or artificial reallocations - a critical safeguard for multinational enterprises operating under DTAAs and the MLI.

Section 270A Income Tax Act | Penalty Invalid Unless Show Cause Notice Specifies Under-Reporting or Misreporting: ITAT Delhi
Case Law Analysis
|Income Tax Appellate Tribunal

Section 270A Income Tax Act | Penalty Invalid Unless Show Cause Notice Specifies Under-Reporting or Misreporting: ITAT Delhi

The ITAT Delhi has ruled that a penalty under Section 270A cannot be sustained if the show cause notice fails to clearly distinguish whether the assessee under-reported or misreported income. This upholds natural justice by requiring precise allegations before imposing financial penalties, directly impacting all taxpayers facing scrutiny for income disclosure discrepancies.

Section 147 Income Tax Act | Assessment Against Non-Existent Entity Void Ab Initio: ITAT Delhi Quashes Reassessment Post-Amalgamation
Case Law Analysis
|Income Tax Appellate Tribunal

Section 147 Income Tax Act | Assessment Against Non-Existent Entity Void Ab Initio: ITAT Delhi Quashes Reassessment Post-Amalgamation

ITAT Delhi rules that tax assessments under Section 147 against a merged entity are legally unsustainable, as proceedings cannot be initiated against a non-existent legal person. The ruling reinforces that jurisdictional defects render such assessments void, impacting tax authorities' powers in post-amalgamation scenarios.

Section 147 Reassessment | Mechanical Approval by Prescribed Authority Invalidates Reopening Proceedings : ITAT Delhi
Case Law Analysis
|Income Tax Appellate Tribunal

Section 147 Reassessment | Mechanical Approval by Prescribed Authority Invalidates Reopening Proceedings : ITAT Delhi

ITAT Delhi sets aside reassessment proceedings under Section 147 of the Income Tax Act, 1961, ruling that mere mechanical approval by the prescribed authority without independent application of mind renders the reopening invalid. The judgment reinforces procedural compliance as a safeguard against arbitrary tax reassessments, impacting taxpayers and tax authorities alike.

Section 69C Income Tax Act | 5% Lumpsum Disallowance on Bogus Purchases Permitted as Equitable Compromise, Not Precedent: ITAT Delhi
Case Law Analysis
|Income Tax Appellate Tribunal

Section 69C Income Tax Act | 5% Lumpsum Disallowance on Bogus Purchases Permitted as Equitable Compromise, Not Precedent: ITAT Delhi

ITAT Delhi has sanctioned a 5% disallowance of Rs.31 lakh in alleged bogus purchases under Section 69C, treating it as a fair, non-precedential middle ground where full disallowance lacks evidentiary support but complete acceptance is untenable. This nuanced approach affects exporters and cash-intensive businesses facing disputed purchase trails, offering a new benchmark for adjudicating borderline cases without setting binding precedent.

Section 147 Income Tax Act | Reopening Invalid Without Addition on Cash Deposits: ITAT Delhi
Case Law Analysis
|Income Tax Appellate Tribunal

Section 147 Income Tax Act | Reopening Invalid Without Addition on Cash Deposits: ITAT Delhi

The ITAT Delhi has ruled that the Income Tax Department cannot reopen an assessment solely on the basis of unreported cash deposits if no addition is made against those deposits in the original assessment. This sets a critical precedent: mere non-filing of return coupled with large cash inflows is insufficient grounds for reopening - the revenue must demonstrate a tangible income addition. Taxpayers and practitioners now have clear protection against speculative reassessments based on deposit volume alone.