The Customs Appellate Tribunal has clarified that the mere issuance of a Pre-Shipment Inspection Certificate (PSIC) by an empanelled agency outside its notified operational area does not transform imported goods into 'prohibited goods' under Section 111(d) of the Customs Act, 1962, provided post-shipment inspection confirms compliance with safety standards. This ruling reinforces the principle that procedural lapses, absent intent or actual risk, cannot justify confiscation.
Background & Facts
The Dispute
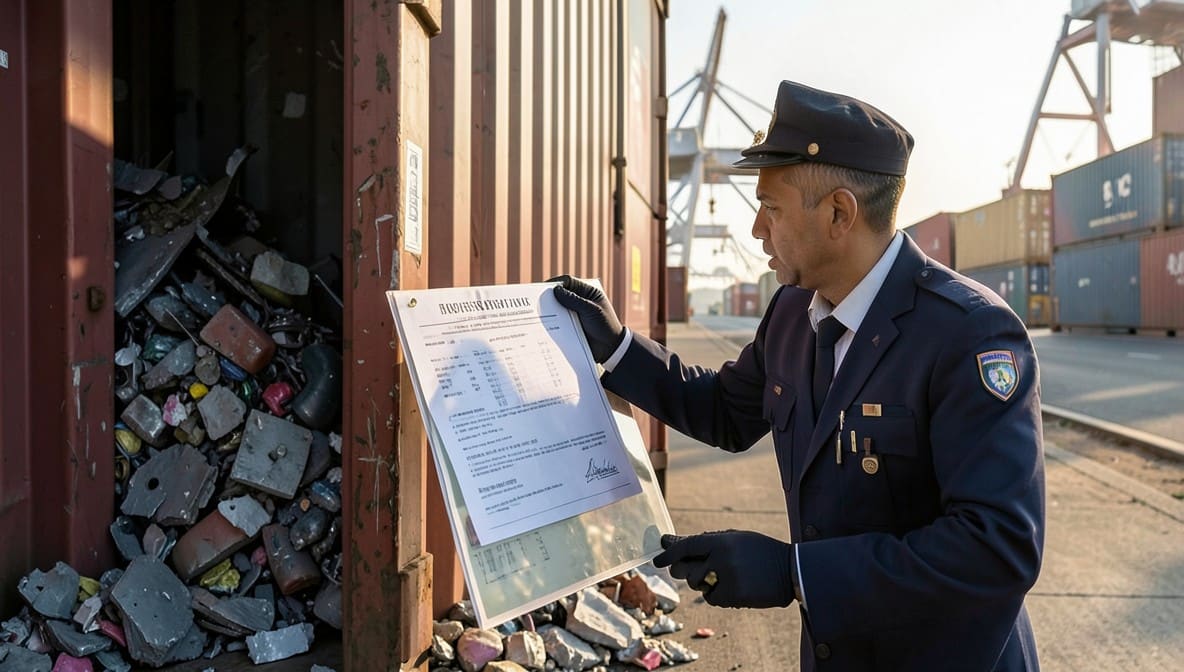
The appellant, M/s Sona Casting Pvt Ltd, imported Heavy Melting Scrap from Guyana under Bill of Entry No. 4236079 dated 01.09.2025. The Department seized the consignment upon discovering that the PSIC submitted was issued by M/s Asia Inspection Agency Ltd, an agency empanelled by DGFT but not authorized to conduct inspections in Guyana. The DGFT Public Notice No. 48/2015-20 dated 05.01.2023 explicitly excluded Guyana from the operational area of this agency. The Department treated the PSIC as invalid and classified the goods as prohibited under Section 111(d) of the Customs Act, 1962.
Key Facts
- The importer submitted a PSIC dated 28.08.2025, issued by M/s Asia Inspection Agency Ltd, indicating inspection at Port Georgetown, Guyana
- DGFT Public Notice No. 48/2015-20 dated 05.01.2023 did not list Guyana as an authorized inspection location for the agency
- The goods were seized on 02.09.2025
- On request, Post Shipment Inspection was conducted by DGFT-approved agency M/s Global Marine Inspection on 14.10.2025
- Post-shipment inspection confirmed radiation levels and safety parameters were within prescribed limits
- No arms, ammunition, explosives, or war materials were detected
- The appellant had no prior history of non-compliance
Procedural History
- 01.09.2025: Import of Heavy Melting Scrap via Bill of Entry No. 4236079
- 02.09.2025: Goods seized by Customs on grounds of invalid PSIC
- 04.12.2025: Order-in-Original passed by Adjudicating Authority
- Confiscation of goods under Section 111(d)
- Redemption fine of Rs. 8,00,000
- Penalty of Rs. 4,00,000 under Section 112
- Penalty of Rs. 4,00,000 under Section 114AA
- 09.04.2026: Commissioner (Appeals) dismissed the appeal and upheld the Order-in-Original
- 27.05.2026: Hearing before CESTAT Chandigarh
- 30.06.2026: Final Order passed by CESTAT
Relief Sought
The appellant sought setting aside of the confiscation order, redemption fine, and penalties imposed under Sections 111(d), 112, and 114AA of the Customs Act, 1962, arguing that the goods were not prohibited and substantial compliance had been achieved.
The Legal Issue
The central question was whether the import of goods with a PSIC issued by a DGFT-empanelled agency outside its notified operational area constitutes 'improper import' under Section 111(d) of the Customs Act, 1962, thereby rendering the goods 'prohibited', when post-shipment inspection confirms the absence of any prohibited content.
Arguments Presented
For the Appellant
The appellant argued that Section 2(33) defines prohibited goods as those whose import is expressly forbidden, not those where procedural conditions are breached. The PSIC’s purpose is to detect war materials, which was conclusively ruled out by post-shipment inspection. Reliance was placed on Commissioner of Customs v. Moolchand Steels Pvt Ltd [2008 (224) ELT 57 (Guj.)], Palco Recycle Exchange Ltd [2026 (3) TMI 1094], CC v. Senor Metals Pvt Ltd [2009 (236) ELT 445 (Guj.)], and M/s Kamachi Steels Ltd [2023 (7) TMI 779], all holding that non-compliance with PSIC technicalities does not equate to improper import. The appellant emphasized that the DGFT Handbook permits post-shipment inspection under para 2.51(d) and that the agency was otherwise empanelled and the inspection was genuine.
For the Respondent
The Department contended that the PSIC is a mandatory pre-condition for import of metallic scrap under the Foreign Trade Policy. Submitting a certificate from an agency not authorized for the country of origin constitutes a fundamental breach, rendering the import non-compliant and the goods liable to confiscation. It argued that the appellant knowingly submitted a certificate from an unauthorized jurisdiction, indicating intent to circumvent policy. The Department distinguished the cited precedents on factual grounds, asserting that those cases involved different factual matrices or did not involve jurisdictional overreach.
The Court's Analysis
The Tribunal examined the statutory definition of 'prohibited goods' under Section 2(33) and the scope of Section 111(d), which permits confiscation only for goods 'improperly imported' - i.e., those imported contrary to a prohibition under the Act or any other law. The Court noted that the DGFT Handbook does not prohibit the import of metallic scrap; it merely imposes conditions. Non-compliance with such conditions, the Court held, does not equate to a prohibition.
"Non-compliance thereof may entail an importer to undergo 100% inspection of the entire consignment. That would not tantamount to improper import of goods as required by Section 111 of the Act."
The Tribunal emphasized that the purpose of PSIC is to ensure the consignment does not contain arms, ammunition, or explosive materials. Since the post-shipment inspection by a DGFT-approved agency confirmed the absence of such materials, the essential objective of the policy was fulfilled. The Court found that the lapse - issuance of PSIC by an agency not authorized for Guyana - was a technical irregularity, not a substantive violation. The appellant had no motive to conceal prohibited content, and the inspection was conducted by a duly empanelled agency. The Tribunal further held that the decisions in Palco Recycle Exchange Ltd, Senor Metals, and Kamachi Steels Ltd were directly applicable and binding in their reasoning.
The Court rejected the Department’s argument that the appellant had knowledge of the jurisdictional limitation, noting no evidence of mala fide or collusion. The imposition of penalties under Sections 112 and 114AA was deemed disproportionate in the absence of any risk to public safety or regulatory integrity.
The Verdict
The appellant succeeded. The CESTAT set aside the Order-in-Original dated 04.12.2025 and the Order-in-Appeal dated 09.04.2026. The confiscation of goods under Section 111(d), the redemption fine of Rs. 8,00,000, the penalty of Rs. 4,00,000 under Section 112, and the penalty of Rs. 4,00,000 under Section 114AA were all quashed. The goods were directed to be released to the appellant without any further liability. The Tribunal directed the Department to return any seized documents and close the case within 15 days of the order.
What This Means For Similar Cases
Technical PSIC Violations Do Not Justify Confiscation
- Practitioners must argue that Section 111(d) applies only to goods whose import is expressly prohibited, not those with procedural irregularities
- Post-shipment inspection by DGFT-approved agencies can cure technical defects in PSIC issuance, provided no prohibited content is found
- The burden shifts to the Department to prove mala fide intent or actual risk, not merely procedural non-compliance
DGFT Policy Compliance Is Substantive, Not Formalistic
- The Handbook’s requirement for PSIC is a condition, not a prohibition
- Importers are entitled to rely on empanelled agencies; they are not obligated to verify the agency’s geographic authorization
- Authorities must distinguish between policy breaches (subject to inspection or penalty) and prohibited imports (subject to confiscation)
Precedents on PSIC Are Binding Across Tribunals
- CESTAT benches across India must follow the ratio in Palco Recycle Exchange Ltd and Senor Metals when similar facts arise
- Appeals against confiscation based on PSIC jurisdictional errors should be filed with emphasis on post-shipment safety certification
- Penalty orders under Sections 112 and 114AA must be challenged on grounds of disproportionality where no harm or intent is established