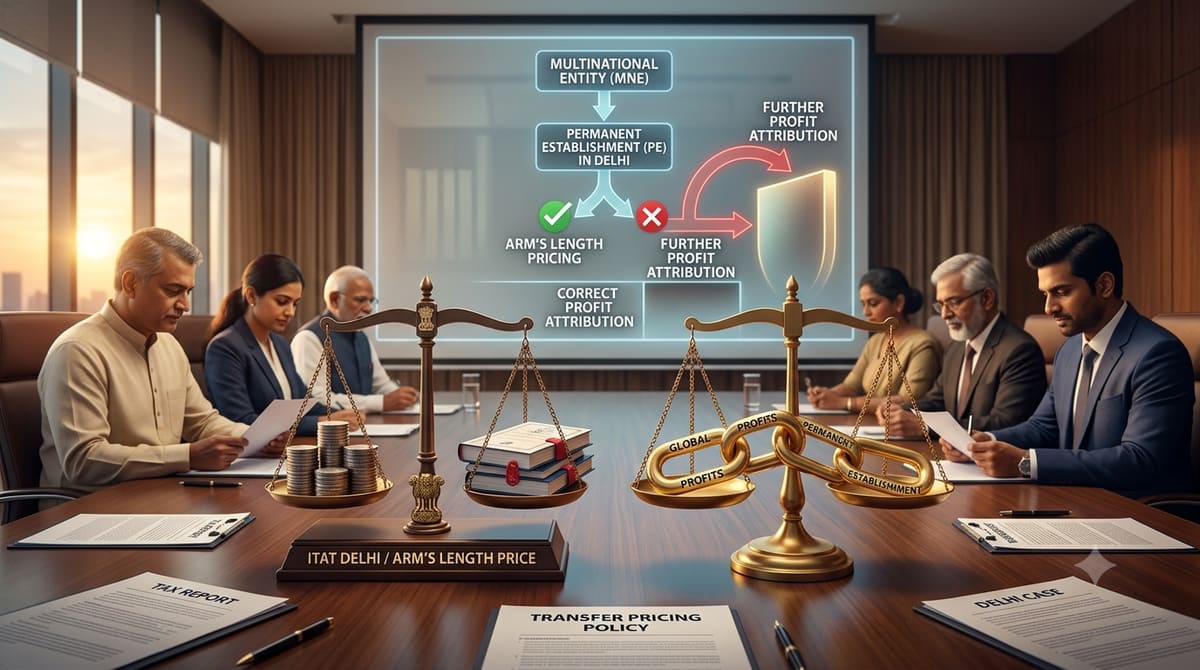
The Income Tax Appellate Tribunal, Delhi, has reaffirmed a foundational principle in international tax law: when an Indian associated enterprise is compensated on an arm's length basis for its functions, no additional profit can be attributed to the foreign enterprise’s alleged permanent establishment in India. This decision, grounded in precedent and statutory interpretation, brings clarity to a long-standing dispute involving Adobe Systems Software Ireland Ltd.
Background & Facts
The Dispute
The dispute centers on whether Adobe Systems Software Ireland Ltd. (the assessee), an Irish tax resident and wholly owned subsidiary of Adobe Inc. (USA), has a Permanent Establishment (PE) in India through its Indian affiliate, Adobe Systems India Private Limited (Adobe India). The Assessing Officer (AO) sought to attribute Rs. 3,80,15,01,653/- as business profits to the alleged PE, based on the argument that Adobe India performed core business functions beyond mere marketing support.
Key Facts
The assessee is incorporated in Ireland and is a tax resident under the India-Ireland Double Taxation Avoidance Agreement (DTAA).
Adobe India, an Indian subsidiary, provides marketing support services to the assessee.
For Assessment Year (AY) 2022-23, the assessee filed its return on 07.11.2022 declaring income of Rs. 89,16,46,169/- from services involving human intervention.
The assessee’s total revenue streams for AY 2022-23 were Rs. 12,42,17,52,814/-, comprising software sales, automated services, and human-intervention services.
The Transfer Pricing Officer (TPO) initially proposed adjustments of Rs. 197,95,83,194/- under Section 92CA of the Income-tax Act, 1961, covering software development, IT-enabled services, marketing support, and interest on receivables.
The Dispute Resolution Panel (DRP), by order dated 23.10.2024, deleted all adjustments except Rs. 11,58,39,661/- for interest on receivables.
Despite this, the AO proposed an additional addition of Rs. 3,80,15,01,653/- under the PE provisions of the India-Ireland DTAA, relying on findings from AY 2021-22.
The AO’s basis for the addition was that Adobe India functioned as a dependent agent PE and fixed place PE, and that its activities were not preparatory or auxiliary under Article 5 of the DTAA, as modified by the Multilateral Instrument (MLI).
The assessee submitted that the transactions with Adobe India were at arm’s length, as confirmed by the DRP’s deletion of all TP adjustments except interest.
Procedural History
07.11.2022: Assessee filed return for AY 2022-23.
31.05.2023: Notice under Section 143(2) issued for scrutiny.
04.01.2024: TPO issued order proposing adjustments of Rs. 197,95,83,194/-.
23.10.2024: DRP order deleted all TP adjustments except Rs. 11,58,39,661/- for interest on receivables.
19.11.2025: AO issued draft assessment order reducing adjustment to Rs. 11,58,39,661/-.
26.03.2024: Draft assessment order proposing PE addition of Rs. 3,80,15,01,653/- issued.
26.12.2024: DRP upheld the PE addition, relying on its prior order for AY 2021-22.
22.01.2025: Final assessment order passed by AO attributing Rs. 3,80,15,01,653/- as PE income.
09.02.2024: Coordinate Bench of ITAT, Delhi, in ITA No. 3672/Del/2023 (AY 2021-22), deleted the PE addition, holding that arm’s length pricing extinguished further attribution.
28.03.2025: Delhi High Court, in ITA No. 32/2025, dismissed the Revenue’s appeal against the ITAT’s order for AY 2021-22, holding no substantial question of law arose.
02.04.2026: Hearing held before ITAT Delhi.
29.06.2026: Judgment pronounced.
The Parties' Positions
Assessee’s Position:
The DRP’s deletion of all TP adjustments (except interest) confirmed that the transactions with Adobe India were at arm’s length.
The Supreme Court in DIT v. Morgan Stanley & Co. and E-Funds IT Solution Inc. holds that once an Indian AE is compensated on an arm’s length basis, no further profit can be attributed to the foreign enterprise’s PE.
The DRP’s reliance on the MLI is invalid, as no separate notification under Section 90(1) of the Act was issued to amend the India-Ireland DTAA.
The findings of the Coordinate Bench in prior years (AY 2010-11 to 2021-22) are binding and must be followed.
Revenue’s Position:
Adobe India performed core business functions beyond marketing support, constituting a PE under Article 5 of the DTAA as modified by MLI.
The MLI, notified under Notification No. 57/2019, modifies the application of the DTAA and does not require country-specific notifications.
The Supreme Court in Hyatt International Southwest Asia Ltd. (2025) has distinguished E-Funds and held that profit attribution is mandatory when core functions are performed, even if the AE is compensated at arm’s length.
The DRP’s findings on MLI’s applicability under Article 13(b) are legally sound.
Relief Sought
The assessee sought deletion of the addition of Rs. 3,80,15,01,653/- attributed as PE income, and allowance of TDS credit of Rs. 10,27,176/-. The Revenue sought to uphold the AO’s order.
The Legal Issue
The central question was whether profit attribution to a Permanent Establishment under the India-Ireland DTAA can be made when the associated enterprise in India has already been compensated on an arm’s length basis under transfer pricing rules, and whether the Multilateral Instrument (MLI) can modify the DTAA without a separate, treaty-specific notification under Section 90(1) of the Income-tax Act.
Arguments Presented
For the Appellant/Petitioner
The assessee relied on the binding precedents of the Supreme Court in DIT v. Morgan Stanley & Co. (2007) 292 ITR 416 and E-Funds IT Solution Inc. (2017) 399 ITR 34 (SC), which hold that once the transfer pricing analysis confirms that the Indian associated enterprise is compensated on an arm’s length basis for its functions and risks, no further profit can be attributed to the foreign enterprise’s PE. The assessee emphasized that the DRP had deleted all TP adjustments except interest, confirming arm’s length pricing. It further argued that the MLI cannot override the DTAA without a specific notification under Section 90(1), citing the ITAT’s own decision in Kosi Aviation Leasing Ltd. and the Delhi High Court’s ruling in Sky High Leasing. The assessee contended that the DRP’s reliance on Article 13(b) of the MLI was legally unsustainable without a separate notification.
For the Respondent/State
The Revenue argued that the MLI, notified under Notification No. 57/2019, operates as a special law modifying the application of the DTAA and does not require country-specific notifications. It relied on Hyatt International Southwest Asia Ltd. (2025) to contend that the Supreme Court has distinguished E-Funds and held that where core business functions are performed, profit attribution to the PE is mandatory, irrespective of arm’s length compensation. The Revenue asserted that Adobe India’s functions - technical oversight, operational control, and integration with global business - were not preparatory or auxiliary, and thus fell squarely under Article 13(b) of the MLI, negating the preparatory/auxiliary exemption under Article 5.
The Court's Analysis
The Tribunal conducted a meticulous review of the factual and legal matrix, beginning with the principle established in Morgan Stanley and E-Funds. It noted that the DRP had deleted all TP adjustments except interest on receivables, thereby confirming that the core transactions between the assessee and Adobe India were at arm’s length. The Tribunal emphasized that the Supreme Court’s holding in E-Funds is not confined to back-office functions but applies whenever the Indian AE’s compensation reflects its functions, assets, and risks.
The Tribunal then addressed the Revenue’s reliance on Hyatt International. It observed that Hyatt distinguished E-Funds on the ground that the Indian entity in Hyatt performed core functions, whereas in the present case, the DRP had already accepted that the marketing support services were adequately compensated. The Tribunal held that Hyatt does not override E-Funds where the TP adjustment confirms arm’s length pricing, as the facts here are indistinguishable from prior years where E-Funds was applied.
Regarding the MLI, the Tribunal relied on its own Coordinate Bench decision in Kosi Aviation Leasing Ltd. (173 taxmann.com 166), which held that the MLI, by altering the text and application of bilateral treaties, requires a separate notification under Section 90(1) for each treaty. The Tribunal rejected the Revenue’s argument that the omnibus notification under Notification No. 57/2019 suffices, noting that the MLI’s effect is not merely interpretive but substantive, and thus falls within the ambit of the Supreme Court’s ruling in Nestle SA.
"Once a transfer pricing analysis has been undertaken in respect of the Indian AE... that, accordingly, would automatically extinguish the need for attribution of any additional profits to the alleged PE."
The Tribunal further noted that the Delhi High Court had already affirmed the ITAT’s decision for AY 2021-22, and that the facts for AY 2022-23 were identical. The principle of consistency and stare decisis compelled the Tribunal to follow its own precedent.
The Verdict
The assessee succeeded. The Tribunal allowed the appeal and deleted the addition of Rs. 3,80,15,01,653/- attributed as income to the alleged Permanent Establishment. The Tribunal also directed the AO to allow the TDS credit of Rs. 10,27,176/- claimed by the assessee. The appeal was allowed on the merits, and the stay application was dismissed as infructuous. The Tribunal held that the MLI’s application to the India-Ireland DTAA is invalid in the absence of a separate notification under Section 90(1).
What This Means For Similar Cases
Arm's Length Pricing Extinguishes PE Attribution
Practitioners must argue that once transfer pricing adjustments confirm arm’s length pricing for an Indian AE, no further profit attribution to the foreign PE is permissible under Morgan Stanley and E-Funds.
The burden shifts to the Revenue to prove that the AE’s compensation does not reflect its functions, assets, and risks - mere allegations of "core functions" are insufficient without a TP adjustment.
Tax authorities cannot rely on hypothetical risk allocation or subjective interpretations of functions when TP analysis has been completed and accepted.
MLI Requires Treaty-Specific Notification
The ITAT’s reaffirmation of Kosi Aviation means that the MLI cannot be applied to any bilateral DTAA without a separate notification under Section 90(1) of the Act.
Revenue’s reliance on omnibus notifications (e.g., Notification No. 57/2019) is legally untenable for treaty modifications.
Practitioners should challenge any PE or anti-avoidance adjustment based on MLI provisions where no country-specific notification exists.
Precedent Binding Across Assessment Years
The Tribunal’s strict adherence to its own prior decisions for AY 2010-11 to 2021-22 establishes that identical factual matrices across years must be treated consistently.
Revenue cannot re-litigate settled issues merely by invoking new legal theories (e.g., MLI) without new facts.
Taxpayers with recurring international structures should document and preserve favorable ITAT rulings to invoke res judicata or stare decisis in subsequent years.