Custom, Excise & Service Tax Tribunal judgments

454 Custom, Excise & Service Tax Tribunal judgments explained in plain English: what was decided, the law applied and why it matters. Page 11 of 19.

CESTAT Hyderabad | Waste Mud from Bleaching Not 'Manufactured Goods' Under Central Excise Act : No Duty Liability on Spent Earth
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

CESTAT Hyderabad | Waste Mud from Bleaching Not 'Manufactured Goods' Under Central Excise Act : No Duty Liability on Spent Earth

CESTAT Hyderabad ruled that waste mud generated from crude palm oil bleaching is non-excisable waste, not manufactured goods, following the withdrawal of CBIC circulars and exemption notifications. The decision clarifies that spent earth lacks marketability and cannot be classified as excisable goods, relieving manufacturers from duty liability on such by-products.
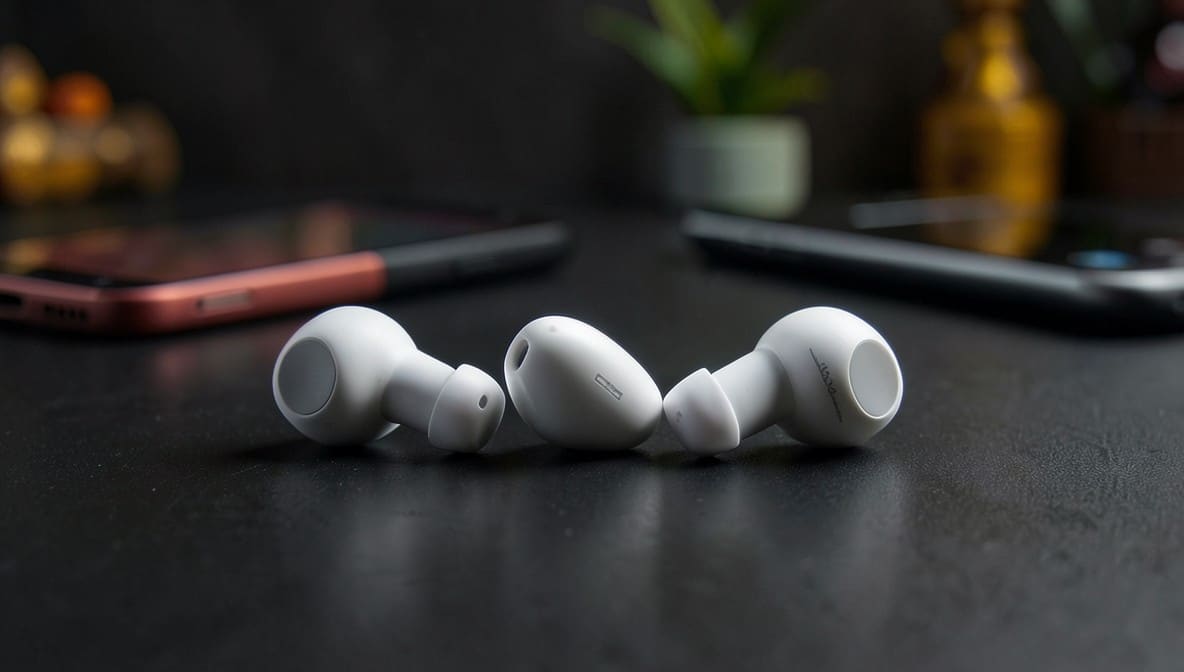
GRI 1 & Eo Nomine Rule | Bluetooth Earphones Classifiable as Audio Devices (CTI 8518), Not Data Transmission (CTI 8517) : CESTAT
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

GRI 1 & Eo Nomine Rule | Bluetooth Earphones Classifiable as Audio Devices (CTI 8518), Not Data Transmission (CTI 8517) : CESTAT

CESTAT rules that Bluetooth earphones' primary function is sound reproduction, not data transmission, classifying them under CTI 8518 (15% duty) instead of CTI 8517 (10% duty). The decision clarifies classification disputes under General Interpretative Rule 1 and the eo nomine provision, impacting importers of wireless audio devices.

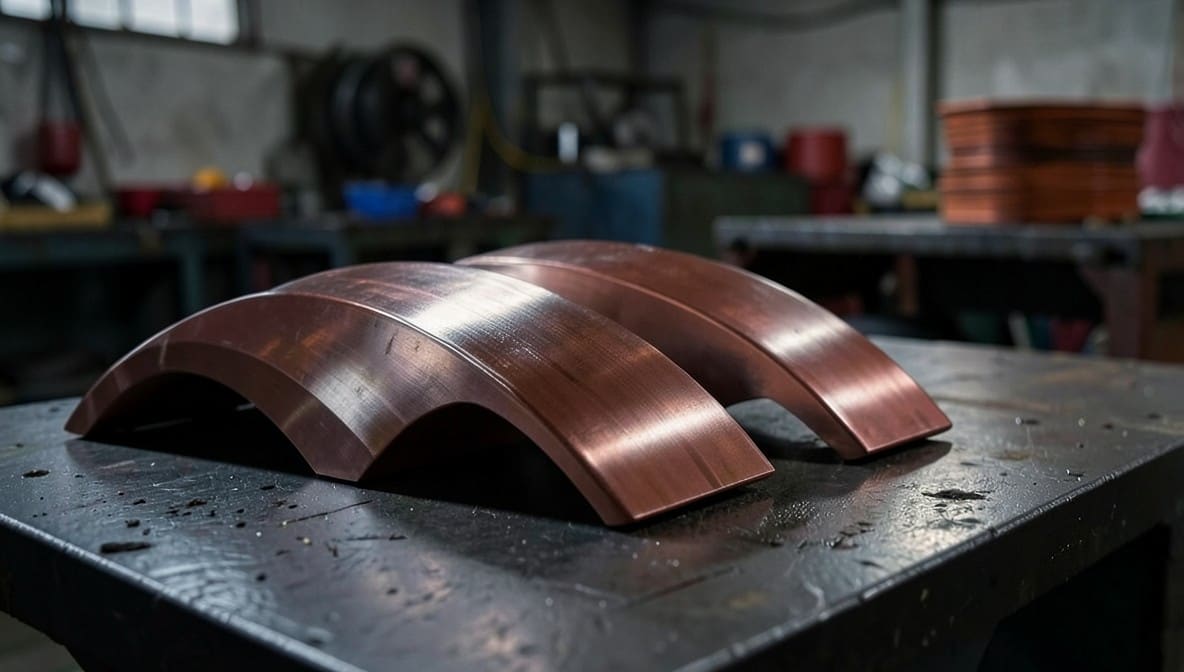
General Rules of Interpretation | Curved Molybdenum Mirrors/Shields Classifiable as 'Other Articles' Under CTH 81029900, Not Flat Sheets : CESTAT
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

General Rules of Interpretation | Curved Molybdenum Mirrors/Shields Classifiable as 'Other Articles' Under CTH 81029900, Not Flat Sheets : CESTAT

CESTAT rules that curved molybdenum mirrors/shields, despite being made from sheets, acquire a distinct functional identity and must be classified under CTH 81029900 at 10% BCD, not as flat sheets under CTH 810295. The decision underscores the application of the General Rules of Interpretation in customs law, impacting importers and tax authorities in tariff disputes.

Rule 26 Central Excise Rules | Penalty Imposition Void Without Prior Confiscation Finding : CESTAT Principal Bench
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

Rule 26 Central Excise Rules | Penalty Imposition Void Without Prior Confiscation Finding : CESTAT Principal Bench

CESTAT rules that penalties under Rule 26 of the Central Excise Rules cannot be imposed unless there is a prior finding that the goods are liable to confiscation. The tribunal invalidated penalties where the adjudicating authority failed to establish confiscation liability, setting a precedent for procedural compliance in excise penalty cases.

Service Tax Exemption for Residential Construction Under Nitesh Estates Doctrine; Extended Period Invocation Requires Proof of Suppression : CAT Allahabad
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

Service Tax Exemption for Residential Construction Under Nitesh Estates Doctrine; Extended Period Invocation Requires Proof of Suppression : CAT Allahabad

CAT Allahabad rules that construction of residential quarters for non-commercial use qualifies for service tax exemption under the Nitesh Estates doctrine. The tribunal further holds that the extended period of limitation cannot be invoked without concrete proof of intentional suppression of facts, setting a precedent for tax disputes involving residential projects.

Rule 6(3A) CENVAT Credit Rules | Reimbursement of Material Costs in BOOT Contracts Not 'Trading' or 'Exempt Service' : CESTAT Chennai
|Custom, Excise & Service Tax Tribunal

Rule 6(3A) CENVAT Credit Rules | Reimbursement of Material Costs in BOOT Contracts Not 'Trading' or 'Exempt Service' : CESTAT Chennai

CESTAT Chennai rules that reimbursement of material costs in a BOOT works contract does not constitute 'trading' or 'exempt service', invalidating mandatory CENVAT credit reversal under Rule 6(3A). The decision clarifies that input service credits can be availed without separate accounts, impacting infrastructure and service contractors under tax law.

Central Excise Valuation | Trade Discounts Without Indirect Consideration Cannot Be Added to Assessable Value : CESTAT Mumbai
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

Central Excise Valuation | Trade Discounts Without Indirect Consideration Cannot Be Added to Assessable Value : CESTAT Mumbai

CESTAT Mumbai rules that trade discounts extended to bulk buyers like NMMT cannot be treated as 'additional consideration' for excise valuation unless there is evidence of indirect benefit flowing from the buyer to the seller. The ruling clarifies that Rule 6 of the Central Excise Valuation Rules requires tangible proof of consideration beyond mere discounts to adjust assessable value, offering relief to suppliers in similar arrangements.

Finance Act, 1994 | Job Work Amounting to Manufacture Exempt from Service Tax Even If Expenses Reimbursed: CESTAT Hyderabad
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

Finance Act, 1994 | Job Work Amounting to Manufacture Exempt from Service Tax Even If Expenses Reimbursed: CESTAT Hyderabad

CESTAT Hyderabad rules that job work constituting manufacture of excisable goods under the Finance Act, 1994, is exempt from service tax, even if the principal reimburses expenses. The ruling clarifies that the nature of the activity-not the reimbursement mechanism-determines tax liability, providing relief to manufacturers engaged in job work agreements.

Cenvat Credit Rules | SEZ Services Exempt from Rule 6(3) Reversal; Input Credits for Rent-a-Cab & Insurance Upheld : CESTAT Chennai
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

Cenvat Credit Rules | SEZ Services Exempt from Rule 6(3) Reversal; Input Credits for Rent-a-Cab & Insurance Upheld : CESTAT Chennai

CESTAT Chennai ruled that services rendered to SEZ units are exempt from Rule 6(3) reversal under Cenvat Credit Rules, and input credits for rent-a-cab and insurance services are allowable if used for output services. This decision clarifies the entitlement of input service credits for businesses operating in SEZs, impacting tax compliance and credit claims under GST and excise laws.

Service Tax Not Applicable on Bareboat Charter Under 'Supply of Tangible Goods' : CESTAT Chennai
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

Service Tax Not Applicable on Bareboat Charter Under 'Supply of Tangible Goods' : CESTAT Chennai

CESTAT Chennai rules that bareboat charter agreements, which transfer possession and control of vessels to charterers, do not qualify as 'supply of tangible goods service' under service tax law. This decision exempts such arrangements from service tax liability, providing clarity for businesses engaged in vessel leasing and dredging operations.

Service Tax Under MRAS Not Leviable on Lump-Sum Work Contracts Without Manpower Specifications : CESTAT Hyderabad
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

Service Tax Under MRAS Not Leviable on Lump-Sum Work Contracts Without Manpower Specifications : CESTAT Hyderabad

CESTAT Hyderabad ruled that service tax under 'Manpower Recruitment or Supply Agency Services' (MRAS) is not applicable to lump-sum work contracts lacking manpower deployment clauses. The decision quashes a Rs. 1.12 crore demand, clarifying that contract terms-not labour deployment-determine tax liability under the Finance Act, 1994.

Ad Valorem Export Duty Must Follow Invoice Value Over Port Test Variations: CESTAT Hyderabad Upholds Transaction Value Under Customs Law
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

Ad Valorem Export Duty Must Follow Invoice Value Over Port Test Variations: CESTAT Hyderabad Upholds Transaction Value Under Customs Law

CESTAT Hyderabad rules that for ad valorem export duty, the transaction value per final invoice prevails over port test moisture variations, provided no higher payment is alleged. The ruling invalidates assessments failing to follow natural justice and reinforces invoice-based valuation for exporters under Customs Law.

HSN 7113 | Gold Chains in Running Length Classified as Jewellery, Not Semi-Manufactured Gold: CESTAT Bangalore
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

HSN 7113 | Gold Chains in Running Length Classified as Jewellery, Not Semi-Manufactured Gold: CESTAT Bangalore

CESTAT Bangalore rules that gold chains in running length, requiring only cutting and hook attachment, qualify as 'articles of jewellery' under HSN 7113, rejecting classification as semi-manufactured gold. The decision clarifies tariff classification for importers and customs authorities, impacting duty exemptions and valuation under the Customs Act 1962.

HSN 3302 | Odoriferous Substances Need Not Be Predominant for Classification: CESTAT Mumbai
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

HSN 3302 | Odoriferous Substances Need Not Be Predominant for Classification: CESTAT Mumbai

CESTAT Mumbai clarifies that goods containing trace amounts of odoriferous ingredients like paprika, garlic oil, or spearmint qualify under HSN 3302 even when not the primary component, overturning a restrictive interpretation by customs authorities. This ruling impacts snack food manufacturers, flavoring suppliers, and importers by providing clarity on tariff classification for complex blended seasonings.

SVLDRS 2019 | Redemption Fine Paid Under Illegal Demand Must Be Refunded as Payment Not Voluntary : CESTAT Ahmedabad
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

SVLDRS 2019 | Redemption Fine Paid Under Illegal Demand Must Be Refunded as Payment Not Voluntary : CESTAT Ahmedabad

CESTAT Ahmedabad rules that redemption fines paid under coercive departmental directions do not qualify as voluntary payments under SVLDRS 2019, entitling assessees to refunds. The decision protects taxpayers from unlawful administrative demands and reinforces the scheme’s intent to provide finality without duress.

Trade Discounts & Manufacturer Incentives Not Taxable as Business Auxiliary Service | CESTAT Kolkata Clarifies Trading Profit Distinction
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

Trade Discounts & Manufacturer Incentives Not Taxable as Business Auxiliary Service | CESTAT Kolkata Clarifies Trading Profit Distinction

CESTAT Kolkata rules that incentives and trade discounts received by car dealers from manufacturers constitute trading profits, not taxable services under Business Auxiliary Service. This removes a major compliance burden on auto dealers and invalidates extended limitation demands where no suppression of facts is proven, setting a critical precedent for dealer-tax disputes across India.

Cenvat Credit Rules 2004 | Insurance, Forex Hedging Fees & HR Training Services Are Input Services for Manufacturers : CESTAT
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

Cenvat Credit Rules 2004 | Insurance, Forex Hedging Fees & HR Training Services Are Input Services for Manufacturers : CESTAT

CESTAT rules that insurance, professional fees for forex hedging, and HR training services qualify as input services under Rule 2(l) of the Cenvat Credit Rules, 2004, entitling manufacturers to credit. The decision clarifies the scope of 'input service' for indirect tax credit eligibility, impacting manufacturers availing such services.

Customs Act Sections 114(iii) & 114AA | Penalty Invalid Without Direct Evidence of Knowledge or Collusion in Fraudulent Export : CESTAT Kolkata
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

Customs Act Sections 114(iii) & 114AA | Penalty Invalid Without Direct Evidence of Knowledge or Collusion in Fraudulent Export : CESTAT Kolkata

CESTAT Kolkata has ruled that penalties under Customs Act Sections 114(iii) and 114AA cannot be imposed on customs brokers without direct evidence linking them to the intent or active participation in fraudulent export schemes. This reinforces the principle that mere association with defaulting exporters is insufficient - the burden of proving collusion rests squarely on the Revenue, safeguarding brokers from speculative liability.

Rule 3(1)(vii) CENVAT Credit Rules | Concessional CVD Eligible for Credit Regardless of Rate: CESTAT Chennai
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

Rule 3(1)(vii) CENVAT Credit Rules | Concessional CVD Eligible for Credit Regardless of Rate: CESTAT Chennai

CESTAT Chennai rules that CENVAT credit on concessional Countervailing Duty (CVD) paid on imported goods is admissible under Rule 3(1)(vii) of the CENVAT Credit Rules, 2004, irrespective of the rate applied. The decision clarifies that credit eligibility depends on the nature of the levy, not the quantum or rate, impacting manufacturers availing concessional duty benefits.

Section 28 Customs Act | Revenue Cannot Reopen IGST Classification Post-Clearance Without Alleging Suppression: CESTAT Kolkata
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

Section 28 Customs Act | Revenue Cannot Reopen IGST Classification Post-Clearance Without Alleging Suppression: CESTAT Kolkata

CESTAT Kolkata ruled that the revenue cannot invoke extended limitation to reassess IGST classification if the importer self-assessed the duty and no suppression was alleged during import clearance. The ruling bars post-clearance demands unless fraud or misdeclaration is proven, protecting importers from retrospective duty adjustments.