The Customs Appellate Tribunal has clarified a critical boundary in tariff classification, holding that gold chains imported in running lengths - though requiring minor finishing - are articles of jewellery under Chapter 71, not semi-manufactured gold. This decision resolves longstanding ambiguity for importers of finished jewellery components and reinforces the principle that essential character, not post-import processing, governs classification.
Background & Facts
The Dispute
The appellant, M/s. Ram Aabhoshan, a proprietary jewellery trading firm based in Agra, imported '22K Assorted Jewellery' consisting of gold chains in running lengths ranging from 2.8 feet to 206 feet. The goods were imported via Bill of Entry No. 3552165 dated 09.10.2017, classified under Customs Tariff Item (CTI) 7113 1990, which covers 'other articles of jewellery of precious metal'. The appellant claimed exemption from Basic Customs Duty under Sl. No. 966(I) of Notification No. 46/2011-Cus. (FTA Notification) and paid IGST at 3% under Sl. No. 13 of Schedule V of Notification No. 1/2017-IGST (Rate) dated 28.06.2017. A Certificate of Origin dated 06.10.2017 certified the goods originated in Indonesia.
Key Facts
- The imported goods were gold chains of uniform thickness, uncut, and without attached clasps or hooks.
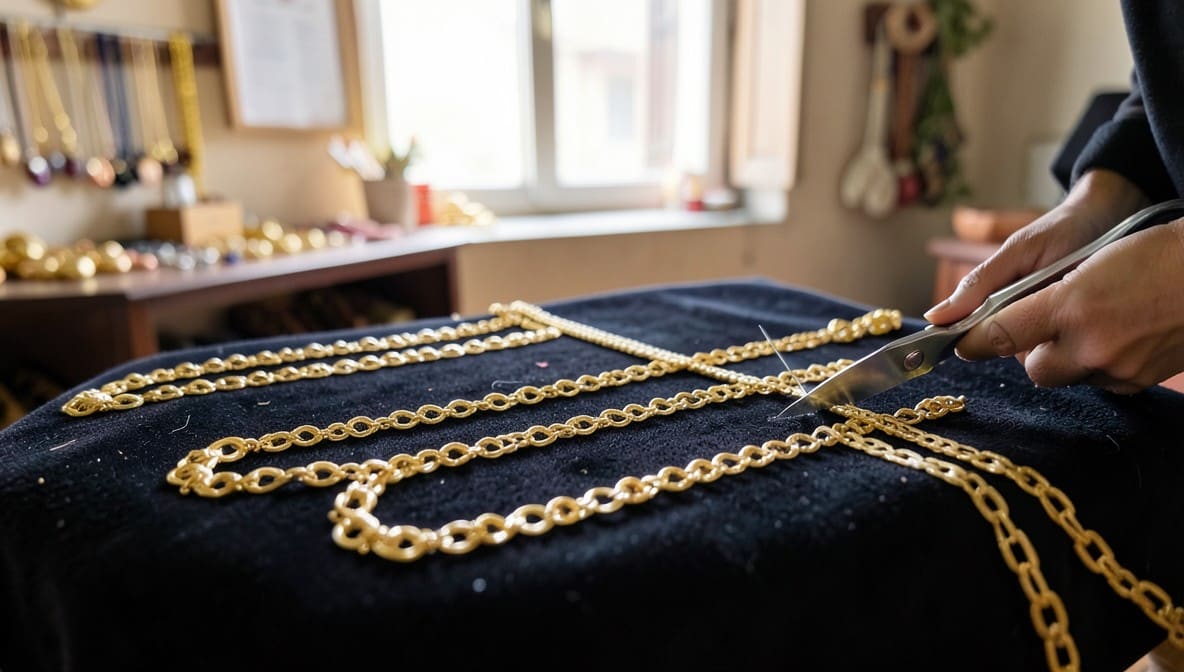
- The appellant intended to cut the chains into customer-specified lengths (e.g., 16 inches, 18 inches) and attach hooks for use as necklaces.
- No melting, alloying, soldering, or polishing of the gold itself was performed; only mechanical cutting and attachment of pre-manufactured hooks.
- The goods were accompanied by sample photographs (Annexure-A) showing the chains in their imported state.
- The Jewellers' Association of India, on 06.11.2017, certified that the goods matched the declared weight, purity, and value.
- The Shed Officer’s report dated 07.11.2017 confirmed the goods were 'gold chains of running lengths varying from 2.8 ft. to 206 ft.'
- The appellant submitted representations on 03.01.2018 and 05.01.2018, requesting re-export without a Show Cause Notice.
Procedural History
- 09.10.2017: Import via Bill of Entry No. 3552165, classification under CTI 7113 1990.
- 03.11.2017: Customs examination order issued; referral to Jewellers' Association.
- 06.11.2017: Jewellers' Association certification received.
- 07.11.2017: Shed Officer’s report confirming nature of goods.
- 05.01.2018: Show Cause Notice issued by Additional Commissioner of Customs proposing reclassification under CTI 7108 1300, confiscation under Section 111(d) and (m), and penalty under Section 112(a).
- 12.02.2018: Order-in-Original passed, confirming reclassification, confiscation, redemption fine of Rs. 15,00,000, and penalty of Rs. 15,00,000.
- 14.02.2018: Appellant paid redemption fine and penalty via challan.
- 16.02.2018: Appellant re-exported goods via Shipping Bill, classifying under CTI 7113 1990.
- 20.02.2018: 'Let Export Order' granted by Customs.
- 05.10.2018: Commissioner of Customs (Appeals) dismissed appeal, upholding reclassification and penalties.
- 21.11.2025: Hearing before Customs Appellate Tribunal, Bangalore Regional Bench.
- 27.04.2026: Final Order issued by Tribunal.
Relief Sought
The appellant sought: (1) setting aside of the Order-in-Appeal dated 05.10.2018; (2) restoration of classification under CTI 7113 1990; (3) refund of redemption fine of Rs. 15,00,000 and penalty of Rs. 15,00,000; and (4) cancellation of confiscation orders under Sections 111(d) and 111(m).
The Legal Issue
The central question was whether gold chains imported in running lengths, requiring only cutting to size and attachment of hooks for wear as necklaces, constitute 'articles of jewellery' classifiable under Customs Tariff Heading 7113, or whether they are 'semi-manufactured forms of gold' classifiable under Heading 7108.
Arguments Presented
For the Appellant
The appellant argued that the impugned goods are finished articles of jewellery under HTH 7113, relying on Chapter Note 9(a) to Chapter 71, which explicitly includes 'necklaces' and uses the term 'such as' to indicate illustrative, not exhaustive, examples. The appellant cited Rule 2(a) of the General Rules of Interpretation (GRI), asserting that the chains had attained the essential character of finished necklaces. Precedents from the Supreme Court (S.R. Tissues Pvt. Ltd., Faridabad Iron and Steel Traders) and CESTAT rulings were cited to establish that mere cutting or slitting without altering the essential character does not constitute manufacture or change classification. The appellant emphasized that the goods were not unwrought, powdered, or semi-manufactured as defined under HSN Explanatory Notes for HTH 7108.
For the Respondent
The Revenue contended that the chains were incomplete and required substantial further processing - cutting, soldering, and polishing - to become wearable necklaces. It argued that the length (up to 206 feet) rendered them unsuitable for direct use and thus fell under HTH 7108 as 'other semi-manufactured forms'. The Revenue also relied on the Foreign Trade Policy restriction limiting gold imports to nominated agencies, arguing the appellant was not authorized. It maintained that misclassification warranted confiscation under Section 111(d) and (m), and that redemption fine and penalty were justified.
The Court's Analysis
The Tribunal undertook a detailed examination of the Customs Tariff Act, the Harmonised System of Nomenclature (HSN), and relevant judicial precedents. It emphasized that classification must be determined by the terms of the headings and Chapter Notes under Rule 1 of the GRI.
"The expression 'articles of jewellery' means (a) any small objects of personal adornment... (for example, rings, bracelets, necklaces...)."
The Tribunal noted that the term 'such as' in Chapter Note 9(a) is interpretative and expansive, not restrictive. It held that the imported gold chains, despite being in running lengths, were designed and intended for use as necklaces, and the only post-import steps - cutting and attaching hooks - were minor, mechanical, and customer-specific adaptations that did not alter the essential character of the goods.
The Tribunal further rejected the Revenue’s reliance on HTH 7108, observing that the Explanatory Notes for that heading describe 'unwrought, semi-manufactured, or powder forms' such as ingots, bars, rods, or foil - none of which matched the nature of the imported chains. The chains were not raw material; they were pre-formed, uniform, and ready for end-use.
The Tribunal also distinguished the case from those involving manufacture, citing S.R. Tissues and Faridabad Iron and Steel Traders, where cutting or slitting was held not to constitute manufacture because the identity and use of the product remained unchanged. Here, the gold chains retained their identity as 'neck chains' before and after cutting.
Regarding confiscation and penalty, the Tribunal held that since the appellant had correctly declared the description and value of the goods, and the dispute was purely one of classification - not misdeclaration or prohibited import - the imposition of confiscation under Section 111(d) and (m), redemption fine under Section 125, and penalty under Section 112(a) was unsustainable. It relied on Vodafone Essar Gujarat and Kores (India) Ltd., which held that classification disputes alone do not justify penal action.
The Verdict
The appellant succeeded. The Tribunal set aside the Order-in-Appeal dated 05.10.2018 and the Order-in-Original dated 12.02.2018 to the extent of reclassification, confiscation, redemption fine, and penalty. The impugned goods are classified under Customs Tariff Item 7113 1990. The appellant is entitled to a refund of Rs. 15,00,000 paid as redemption fine and Rs. 15,00,000 paid as penalty. The Tribunal directed the Revenue to process the refund within 8 weeks of the order date.
What This Means For Similar Cases
Classification Turns on Essential Character, Not Post-Import Processing
- Practitioners must argue that minor, customer-specific finishing steps (cutting, attaching clasps, polishing) do not alter the essential character of jewellery components.
- Importers of semi-finished jewellery items (e.g., chains, beads, settings) can now rely on HTH 7113 if the goods are designed for direct use as adornments.
- The burden shifts to the Revenue to prove the goods lack the essential character of finished articles, not merely that they require minor assembly.
Classification Disputes Do Not Justify Confiscation or Penalty
- Where the description, value, and origin are correctly declared, and the dispute is solely on tariff classification, confiscation under Section 111(d)/(m) and penalty under Section 112(a) are legally untenable.
- Redemption fine under Section 125 cannot be imposed where confiscation is not sustainable.
- Practitioners should immediately challenge punitive actions in classification disputes, citing Vodafone Essar Gujarat and Kores (India) Ltd.
HSN Explanatory Notes and Chapter Notes Are Binding Interpretative Tools
- The use of 'such as' in Chapter Notes is not limiting; it expands the scope of the heading.
- Explanatory Notes to HSN are authoritative for interpreting tariff headings and must be applied consistently.
- Importers should routinely reference HSN Explanatory Notes in classification arguments, especially when goods fall near the boundary between headings.