Custom, Excise & Service Tax Tribunal judgments

454 Custom, Excise & Service Tax Tribunal judgments explained in plain English: what was decided, the law applied and why it matters. Page 15 of 19.

CENVAT Credit Rules 2004 | Input Service Credit Allowable for Import-Only Businesses Without Output Services : CESTAT Chennai
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

CENVAT Credit Rules 2004 | Input Service Credit Allowable for Import-Only Businesses Without Output Services : CESTAT Chennai

CESTAT Chennai rules that businesses engaged solely in imports can avail CENVAT credit on input services like freight and network management charges, even without providing taxable output services. The Tribunal overturned the Revenue's denial, clarifying that the definition of 'input service' under Rule 2(l) of CENVAT Credit Rules, 2004 includes services used for business operations, regardless of output service provision.

Rule 2(l) CENVAT Credit Rules | Recovery Agent Services Qualify as Input Services for NBFCs : CESTAT Chennai
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

Rule 2(l) CENVAT Credit Rules | Recovery Agent Services Qualify as Input Services for NBFCs : CESTAT Chennai

CESTAT Chennai rules that recovery agent services are integral to money lending operations of NBFCs, entitling them to CENVAT credit under Rule 2(l) of the CENVAT Credit Rules, 2004. The decision clarifies input service eligibility for financial institutions availing reverse charge credit, impacting tax compliance and credit claims in the banking and finance sector.

Section 108 Customs Act | Statements Without Section 138B Compliance Are Inadmissible Evidence : CESTAT Chennai
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

Section 108 Customs Act | Statements Without Section 138B Compliance Are Inadmissible Evidence : CESTAT Chennai

CESTAT Chennai ruled that statements recorded under Section 108 of the Customs Act cannot be relied upon for customs valuation or penalty imposition unless the mandatory procedure under Section 138B is followed. This holding reinforces procedural safeguards for importers and beneficial owners, limiting arbitrary reliance on uncorroborated statements in customs disputes.

CENVAT Credit | Indirect Nexus to Output Services Qualifies as Input Services; Parent-Subsidiary Entities Distinct for Export of Services : CESTAT
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

CENVAT Credit | Indirect Nexus to Output Services Qualifies as Input Services; Parent-Subsidiary Entities Distinct for Export of Services : CESTAT

CESTAT rules that input services with an indirect nexus to output services are eligible for CENVAT credit, and parent-subsidiary entities remain distinct legal persons for export of services, even across borders. The ruling impacts multinational corporations claiming tax credits on shared services and clarifies corporate distinctness under service tax law.

Section 4A Central Excise Act | Strapped Tyres Not 'Pre-Packaged Commodities' Under Legal Metrology Act : CESTAT Chennai
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

Section 4A Central Excise Act | Strapped Tyres Not 'Pre-Packaged Commodities' Under Legal Metrology Act : CESTAT Chennai

CESTAT Chennai rules that tyres secured with plastic straps do not qualify as 'pre-packaged commodities' under the Legal Metrology Act, 2009, exempting them from valuation under Section 4A of the Central Excise Act. The ruling quashes a ₹221 crore demand, interest, and penalty, setting a precedent for similar valuation disputes in the tyre industry.

Section 73 Finance Act | 18-Month Limitation Period Mandatory; Tribunal's 'One Year' Reference in Remand Order Overridden : CESTAT
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

Section 73 Finance Act | 18-Month Limitation Period Mandatory; Tribunal's 'One Year' Reference in Remand Order Overridden : CESTAT

CESTAT reaffirms that the statutory 18-month limitation under Section 73 of the Finance Act, 1994 is non-negotiable, even if a tribunal's remand order erroneously refers to a shorter period. The ruling clarifies that clerical errors in judicial orders cannot override statutory timelines, impacting service tax assessments and appeals.

Section 67 Finance Act | Salaries of Hotel Staff Not Part of Operator Fee for Service Tax Valuation : CESTAT
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

Section 67 Finance Act | Salaries of Hotel Staff Not Part of Operator Fee for Service Tax Valuation : CESTAT

CESTAT rules that salaries paid by hotel owners to key managerial staff under a hotel operating agreement are not includible in the 'operator fee' for service tax valuation under Section 67 of the Finance Act. The decision clarifies that only amounts directly linked to the provision of taxable services can be taxed, protecting hotel owners from inflated tax liabilities.

Pre-2015 Service Tax Valuation | Ocean Freight Collected as Principal Not Taxable Under Section 67: CESTAT Chennai
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

Pre-2015 Service Tax Valuation | Ocean Freight Collected as Principal Not Taxable Under Section 67: CESTAT Chennai

CESTAT Chennai rules that ocean freight charges collected by multimodal transporters on a principal-to-principal basis between 2013-2015 are not includible in taxable value under the unamended Section 67 of the Finance Act. The ruling clarifies that reimbursable expenditures, when not billed to the end customer, escape service tax liability, offering relief to logistics service providers in pre-GST disputes.

Section 65B(44) Finance Act | Transfer of Development Rights Exempt from Service Tax as Immovable Property Transfer : CESTAT
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

Section 65B(44) Finance Act | Transfer of Development Rights Exempt from Service Tax as Immovable Property Transfer : CESTAT

CESTAT rules that transfer of development rights, where it constitutes transfer of immovable property interest, falls outside the definition of 'service' under Section 65B(44) of the Finance Act, 1994. The ruling shields landowners and developers from service tax liability on joint development agreements, clarifying a critical tax exemption for real estate transactions.

CENVAT Credit Eligible for Telecom Towers as 'Goods' Under Rule 2(k); Unutilized Credit Transferable on Centralized Registration Shift : CESTAT Chandigarh
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

CENVAT Credit Eligible for Telecom Towers as 'Goods' Under Rule 2(k); Unutilized Credit Transferable on Centralized Registration Shift : CESTAT Chandigarh

CESTAT Chandigarh rules telecom towers qualify as 'goods' under CENVAT Credit Rules, enabling taxpayers to claim input credit. The tribunal also permits transfer of unutilized credit upon shifting to centralized registration, clarifying substantive rights for telecom infrastructure providers.

Chapter 30 vs Chapter 33 | CESTAT Classifies Ayurvedic P&P Medicines with Excipients as Medicaments, Not Cosmetics : CESTAT
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

Chapter 30 vs Chapter 33 | CESTAT Classifies Ayurvedic P&P Medicines with Excipients as Medicaments, Not Cosmetics : CESTAT

CESTAT rules that Ayurvedic Patent & Proprietary medicines containing permitted excipients must be classified under Chapter 30 (medicaments) of the Central Excise Tariff, not Chapter 33 (cosmetics). The decision sets a precedent for manufacturers, ensuring duty benefits and regulatory clarity for similar products.

Pre-July 2010 Residential Construction Exempt from Service Tax; CESTAT Hyderabad Invalidates Penalty & Mandates Composition Scheme Reconsideration
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

Pre-July 2010 Residential Construction Exempt from Service Tax; CESTAT Hyderabad Invalidates Penalty & Mandates Composition Scheme Reconsideration

CESTAT Hyderabad ruled that construction of residential complexes before 01.07.2010 is not taxable under service tax, quashing penalties imposed for interpretational disputes. The tribunal directed reconsideration of demands under the composition scheme, offering relief to contractors facing retrospective tax liabilities.

CESTAT Hyderabad | Bona Fide Tariff Classification Disputes Exempt from Penalty; Retrospective Circulars Invalid Against Importers
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

CESTAT Hyderabad | Bona Fide Tariff Classification Disputes Exempt from Penalty; Retrospective Circulars Invalid Against Importers

CESTAT Hyderabad ruled that importers cannot be penalized for genuine disputes over customs tariff classification, shifting the burden of proof to the department. The tribunal also invalidated retrospective application of circulars that are adverse to importers, reinforcing natural justice in customs adjudication.

SAD Exemption Under Notification 45/2005 | Stock Transfer from FTWZ to DTA Eligible Despite VAT Payable : CESTAT Mumbai
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

SAD Exemption Under Notification 45/2005 | Stock Transfer from FTWZ to DTA Eligible Despite VAT Payable : CESTAT Mumbai

CESTAT Mumbai rules that Special Additional Duty (SAD) exemption under Notification 45/2005 applies to stock transfers from Free Trade Warehousing Zones (FTWZ) to Domestic Tariff Areas (DTA) even if VAT is payable on final sale. The tribunal also bars invocation of the extended limitation period without legal basis, reinforcing compliance clarity for importers and manufacturers.

Works Contract Service Exemption | CESTAT Hyderabad Rules RailTel's OFC Project Not Taxable as Business Support Service
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

Works Contract Service Exemption | CESTAT Hyderabad Rules RailTel's OFC Project Not Taxable as Business Support Service

CESTAT Hyderabad clarifies that RailTel's Optical Fibre Cable (OFC) laying project under a composite contract with Indian Railways qualifies as a Works Contract Service, exempt from service tax. The ruling rejects the department's classification as Business Support Service, saving RailTel ₹1.6 crore in tax demands and setting a precedent for infrastructure projects with similar contractual structures.

Section 65(105)(zzp) Finance Act | Consignment Note Mandatory for Goods Transport Agency Service Tax Liability: CESTAT Hyderabad
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

Section 65(105)(zzp) Finance Act | Consignment Note Mandatory for Goods Transport Agency Service Tax Liability: CESTAT Hyderabad

CESTAT Hyderabad rules that service tax under Goods Transport Agency Service (GTAS) cannot be levied without a valid consignment note as defined under Rule 4B of Service Tax Rules. The absence of such a note negates tax liability, reinforcing precedent that documentary evidence is essential for GTAS classification.

Finance Act 1994 | Despatch Money for Expedited Cargo Unloading Not Taxable as 'Port Service' : CESTAT Hyderabad
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

Finance Act 1994 | Despatch Money for Expedited Cargo Unloading Not Taxable as 'Port Service' : CESTAT Hyderabad

CESTAT Hyderabad rules that despatch money received for expedited cargo unloading under charter agreements does not constitute a 'port service' under Section 65(105)(zn) of the Finance Act, 1994. The tribunal sets aside a Rs. 2.58 crore service tax demand, clarifying that contractual incentives for operational efficiency are not taxable services.

Service Tax on Co-Owners | CESTAT Chennai Rules Co-Owners Not an 'Association of Persons' Without Volitional Joint Enterprise
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

Service Tax on Co-Owners | CESTAT Chennai Rules Co-Owners Not an 'Association of Persons' Without Volitional Joint Enterprise

CESTAT Chennai clarifies that co-owners renting property individually, without joint management or shared income pooling, cannot be taxed as an 'Association of Persons' under service tax laws. This ruling protects individual co-owners from collective tax liability, reinforcing the need for volitional joint enterprise to trigger AOP classification.

Service Tax Exemption | Tobacco Threshing & Redrying on Job Work is Agricultural Processing, Not Taxable BAS : CESTAT Hyderabad
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

Service Tax Exemption | Tobacco Threshing & Redrying on Job Work is Agricultural Processing, Not Taxable BAS : CESTAT Hyderabad

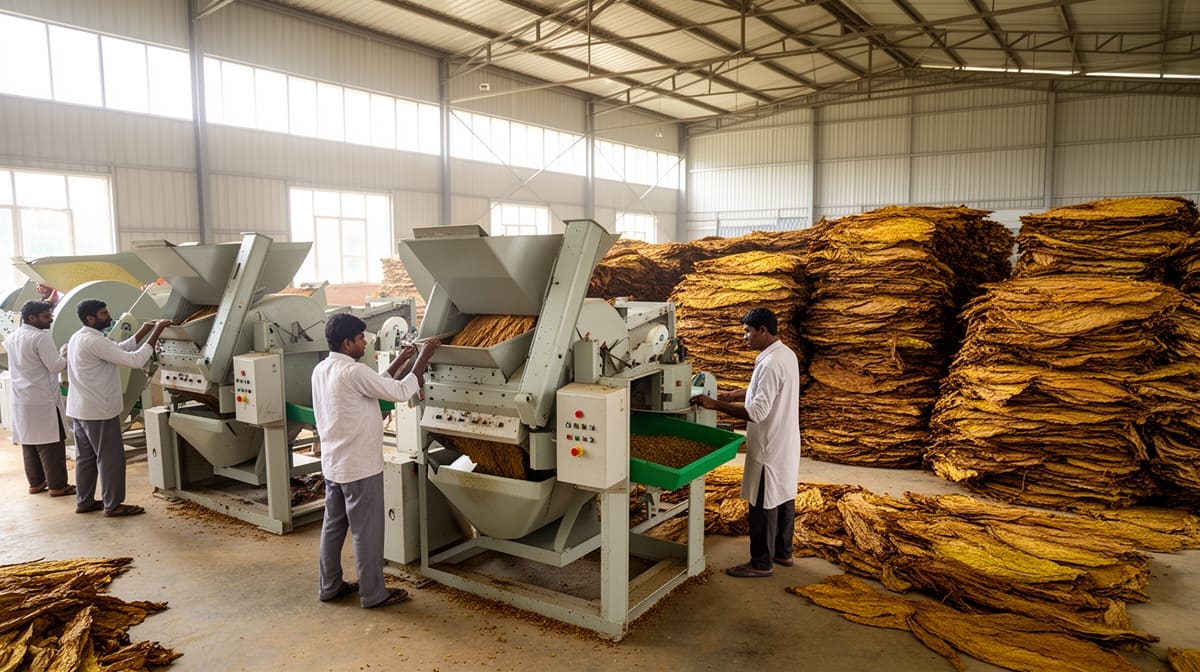
CESTAT Hyderabad rules that threshing and redrying of tobacco leaves on a job work basis qualifies as processing of agricultural produce, exempting it from service tax under Notification 14/2004-ST. The decision clarifies that such activities do not fall under 'Business Auxiliary Services', providing relief to tobacco processors and traders from retrospective tax demands.

Service Tax on GSA Commissions Exempt Under Business Auxiliary Services: CESTAT Hyderabad Sets Precedent
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

Service Tax on GSA Commissions Exempt Under Business Auxiliary Services: CESTAT Hyderabad Sets Precedent

CESTAT Hyderabad ruled that commissions received by air travel agents from General Sales Agents (GSAs) and their own branches are not taxable under Business Auxiliary Services (BAS). The decision quashes service tax demands and penalties, reinforcing that GSA commissions fall outside BAS purview, offering relief to travel agents and similar service providers.