The Chennai Regional Bench of the Customs, Excise and Service Tax Appellate Tribunal has delivered a landmark ruling clarifying the boundary between commercial packaging and logistical securing under the Central Excise Act, 1944. The decision decisively rejects the Revenue’s attempt to impose valuation under Section 4A on tyres, tubes and flaps secured with plastic straps, reinforcing that statutory preconditions for deeming valuation must be strictly construed.
Background & Facts
The Dispute
The dispute arose over the valuation methodology applied by M/s. MRF Limited for clearance of tyres, tubes and flaps to the replacement market. The Department contended that when these components were inserted together and secured with two or three plastic carry straps, they constituted "pre-packaged commodities" under the Legal Metrology Act, 2009, thereby mandating valuation under Section 4A of the Central Excise Act, 1944. The Appellant maintained that such strapping was purely for transportation safety and did not amount to packaging under the law.
Key Facts
- MRF Limited manufactures tyres, tubes and flaps falling under Chapter 40 of the Central Excise Tariff Act, 1985
- Certain high-end tyres were fully wrapped and bore MRP stickers and were assessed under Section 4A - this was not disputed
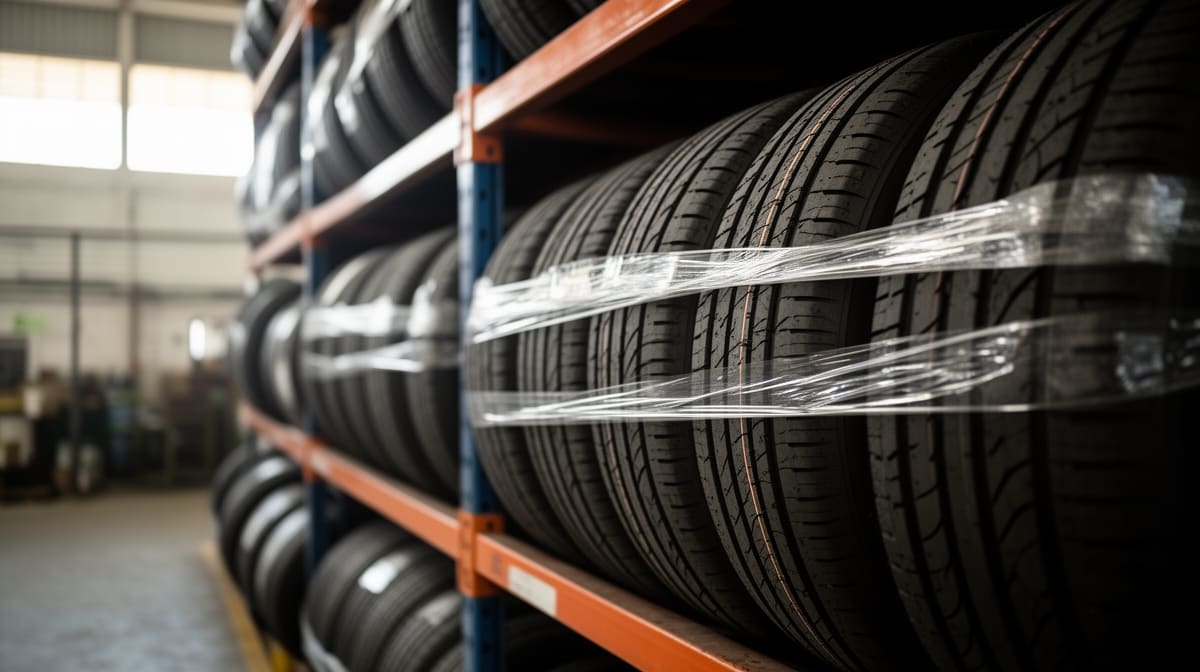
- The impugned goods were tyres, tubes and flaps inserted together and secured with thin plastic carry straps at two or three points
- The straps covered only 1.4% to 3.3% of the tyre surface area and did not enclose, wrap or contain the goods
- The goods remained fully visible, unsealed and unwrapped
- The strapping was done solely to prevent displacement during handling and transport
- The Appellant filed ER-1 monthly returns disclosing the nature of clearance and valuation under Section 4
- Correspondence dated 26.02.2013 was sent to jurisdictional authorities explaining the strapping process
- Notification No. 49/2008-CE (NT) dated 24.12.2008 included "parts, components and assemblies of automobiles" - which the Department claimed covered the impugned goods
- Board Letter No. 167/38/2008-CX-4 dated 16.12.2008 clarified that tyres, tubes and flaps fell within the scope of Notification No. 49/2008-CE (NT)
- Internal marketing circulars fixed recommended retail prices (MRPs) for various states, but these were not printed on the strapped goods
- The Ministry of Consumer Affairs, in communication dated 04.04.2016, stated that tyre-tube-flap combinations "may" be considered pre-packaged, indicating ambiguity
Procedural History
- 01.03.2012 to 30.06.2017: Period of clearance under dispute
- 06.04.2019: Show Cause Notice issued under Section 11A(4) proposing revaluation under Section 4A and demand of differential duty
- 31.05.2023: Order-in-Original No. 26/2023 (Commr.) passed by Commissioner of GST and Central Excise, Chennai, confirming demand of ₹221,31,60,075/- for differential duty, interest under Section 11AA, and penalty under Section 11AC
- 29.09.2025: Hearing before CESTAT Chennai
- 16.03.2026: Final Order No. 40364/2026 issued by CESTAT Chennai
Relief Sought
The Appellant sought:
- Setting aside of the Order-in-Original dated 31.05.2023
- Declaration that the strapped tyre-tube-flap combinations are not pre-packaged commodities
- Cancellation of the demand of ₹221,31,60,075/- for differential duty
- Cancellation of interest under Section 11AA
- Cancellation of penalty under Section 11AC
The Legal Issue
The central question was whether tyres, tubes and flaps secured with plastic carry straps constitute "pre-packaged commodities" under Section 2(l) of the Legal Metrology Act, 2009, thereby triggering valuation under Section 4A of the Central Excise Act, 1944, and whether the extended period of limitation under Section 11A(4) and consequent penalty under Section 11AC are sustainable in the absence of wilful suppression.
Arguments Presented
For the Appellant
The Appellant argued that the strapping of tyres, tubes and flaps with plastic carry straps does not meet the definition of "pre-packaged commodity" under Section 2(l) of the Legal Metrology Act, 2009. The term "placed in a package" requires enclosure or containment - a carton, bag, box or wrapper - not mere securing. The plastic straps cover less than 3.3% of the surface and do not enclose the goods. Reliance was placed on clarifications issued under the Standards of Weights and Measures Act, 1976, dated 01.05.1991 and 16.11.1992, which explicitly stated that tyres tied with polythene strips do not constitute pre-packaged commodities. Section 57 of the Legal Metrology Act preserves such clarifications unless inconsistent, and no inconsistency was shown. The Appellant further cited M/s. Apollo Tyres Ltd. v. Commissioner of GST & Central Excise, Chennai, 2025 (10) TMI 1128 (CESTAT Chennai), on identical facts, which held that such goods are not assessable under Section 4A. On limitation, it was submitted that the valuation methodology was consistently disclosed in ER-1 returns and correspondence, and the dispute was purely interpretational - not suppression. Reliance was placed on Pahwa Chemicals Pvt. Ltd., Anand Nishikawa Co. Ltd., and Gokak Patel Volkart to argue that mere legal interpretation does not amount to wilful suppression.
For the Respondent
The Revenue contended that the strapped tyre-tube-flap combinations are sold as a unit in predetermined quantity and therefore satisfy the definition of "pre-packaged commodity" under Rule 2(k) and Rule 6 of the Packaged Commodities Rules, 2011. It argued that the expression "or otherwise" in Rule 2(g) is wide enough to include strapping. The Revenue relied on Jayanti Food Processing (P) Ltd. v. CCE and Whirlpool India Ltd. v. Union of India to assert that once goods are notified under Notification No. 49/2008-CE (NT), Section 4A applies. It alleged suppression due to "double standards" - applying Section 4A to fully wrapped tyres and Section 4 to strapped ones - and claimed that internal MRP fixation evidenced intent to evade duty. The Revenue further argued that the Appellant’s consistent use of Section 4 for strapped goods, despite internal MRPs, demonstrated deliberate concealment.
The Court's Analysis
The Tribunal undertook a rigorous statutory and precedential analysis to determine whether the impugned goods met the cumulative conditions for Section 4A valuation as laid down in Jayanti Food Processing (P) Ltd. v. CCE and reaffirmed in Whirlpool India Ltd. v. Union of India. The Court emphasized that Section 4A is an exception to the general rule of transaction value under Section 4 and must be strictly construed.
"Section 4A is not an independent charging provision. It is contingent upon the Legal Metrology regime. Being an exception to the general rule under Section 4, it must be applied strictly within the statutory contours."
The Court held that the definition of "pre-packaged commodity" under Section 2(l) of the Legal Metrology Act requires three elements: placement in a package, absence of the purchaser at the time of packing, and pre-determined quantity. The dispute centered on the first element - "placed in a package." The Tribunal rejected the Revenue’s expansive interpretation, noting that the Legislature deliberately used the term "package," not "bundled," "tied," or "grouped." The natural and commercial meaning of "package" connotes enclosure or containment - a carton, bag, box or wrapper - not a plastic strap covering 1.4% to 3.3% of the surface.
"A plastic carry strap does not enclose, contain, wrap or box the goods. It merely secures."
The Court distinguished Jayanti Food Processing and Whirlpool, noting that in those cases, goods were sold in conventional packaging such as cartons or shrink-wrap bearing MRP. The Supreme Court had never held that strapping without enclosure constitutes packaging. The Tribunal also upheld the continued validity of clarifications issued under the repealed Standards of Weights and Measures Act, 1976, under Section 57 of the Legal Metrology Act, 2009, which explicitly excluded tied tyres from the definition of pre-packaged commodities.
On limitation, the Court held that the Department failed to establish wilful suppression. The Appellant disclosed all facts in statutory returns and correspondence. The dispute was purely interpretational - whether Section 4A applied to strapped goods - not concealment. The Court cited Pahwa Chemicals and Anand Nishikawa to affirm that where facts are disclosed and the issue is one of legal interpretation, extended limitation under Section 11A(4) cannot be invoked. The Revenue’s reliance on "double standards" was rejected as illogical: if the Appellant intended to evade Section 4A, it would not have applied it to fully wrapped tyres.
"The selective application based on packaging status indicates a bona fide understanding rather than a device to evade duty."
The Court further held that internal MRP fixation does not create a statutory obligation under the Legal Metrology Act. The Ministry of Consumer Affairs itself had used the tentative term "may" in its 2016 communication, underscoring the ambiguity in the law. The Tribunal concluded that the Appellant’s conduct was bona fide and that penalty under Section 11AC and interest under Section 11AA could not survive where the underlying demand was unsustainable.
The Verdict
The Appellant succeeded on all grounds. The Tribunal set aside the Order-in-Original No. 26/2023 dated 31.05.2023. The demand of ₹221,31,60,075/- for differential duty, interest under Section 11AA, and penalty under Section 11AC were cancelled in full. The impugned goods are to be valued under Section 4 of the Central Excise Act, 1944. The extended period under Section 11A(4) was held inapplicable. No interest or penalty is payable. The appeal was allowed with consequential relief.
What This Means For Similar Cases
Packaging Requires Enclosure, Not Just Securing
- Practitioners must distinguish between logistical securing (strapping, banding, tying) and true packaging (enclosure in cartons, bags, shrink-wrap)
- Goods that remain fully exposed, even if bundled, cannot be treated as pre-packaged commodities under the Legal Metrology Act
- The 1.4% to 3.3% coverage threshold in this case provides a practical benchmark - any securing that leaves the product substantially visible and uncontained is unlikely to qualify
Interpretational Disputes Shield Against Extended Limitation
- Where the assessee discloses all factual details in returns and correspondence, and the dispute is over legal interpretation, extended limitation under Section 11A(4) cannot be invoked
- Revenue cannot allege suppression merely because its view differs from the assessee’s - even if the assessee’s view is later found incorrect
- Internal pricing policies or MRP fixation without statutory declaration do not constitute suppression
Clarifications Under Repealed Laws Remain Valid
- Clarifications issued under the Standards of Weights and Measures Act, 1976, continue to apply under Section 57 of the Legal Metrology Act, 2009, unless expressly inconsistent
- Practitioners should cite such clarifications as binding guidance, especially in industries like tyres, automotive parts, and consumer goods
- The Revenue bears the burden to prove inconsistency - mere disagreement is insufficient
Judicial Precedent Is Binding on Coordinate Benches
- The decision in Apollo Tyres Ltd. (2025) on identical facts was followed as binding precedent
- Coordinate Benches of CESTAT must follow each other unless shown to be per incuriam
- Practitioners should cite consistent tribunal rulings to reinforce arguments on valuation disputes
Penalty and Interest Are Consequential, Not Automatic
- Penalty under Section 11AC requires proof of fraud, wilful misstatement, or suppression with intent to evade - mere non-payment is insufficient
- Interest under Section 11AA is compensatory and cannot survive if the underlying duty demand is set aside
- Where the valuation methodology is disclosed and the dispute is interpretational, both penalty and interest collapse