The Central Excise and Service Tax Appellate Tribunal (CESTAT), Hyderabad, has definitively held that threshing and redrying of tobacco leaves on a job work basis does not constitute a taxable Business Auxiliary Service under the Service Tax regime. This ruling reaffirms the exemption for post-harvest agricultural processing that preserves the essential character of the produce, providing critical clarity for agro-processing industries.
Background & Facts
The Dispute
The dispute arose over whether M/s Premier Tobacco Packers, a company engaged in threshing and re-drying of cured tobacco leaves on a job work basis, was liable to pay service tax under the category of Business Auxiliary Services (BAS). The Department of Central Tax & Customs assessed the company for service tax of Rs.1,66,98,271/-, along with interest and penalties, on the ground that the services rendered constituted BAS under Section 65(105)(zzb) of the Finance Act, 1994. The company contested this, asserting that its activities were integral to the processing of agricultural produce and thus exempt under Notification No.14/2004-ST, as amended.
Key Facts
- The respondent, M/s Premier Tobacco Packers, operates in Karedu, Prakasam District, Andhra Pradesh, and provides job work services to buyers/exporters of cured tobacco.
- Tobacco is cultivated by farmers, cured in barns, and auctioned through Tobacco Board-designated platforms.
- After auction, buyers transport cured tobacco to godowns and engage third parties like the respondent for threshing and re-drying.
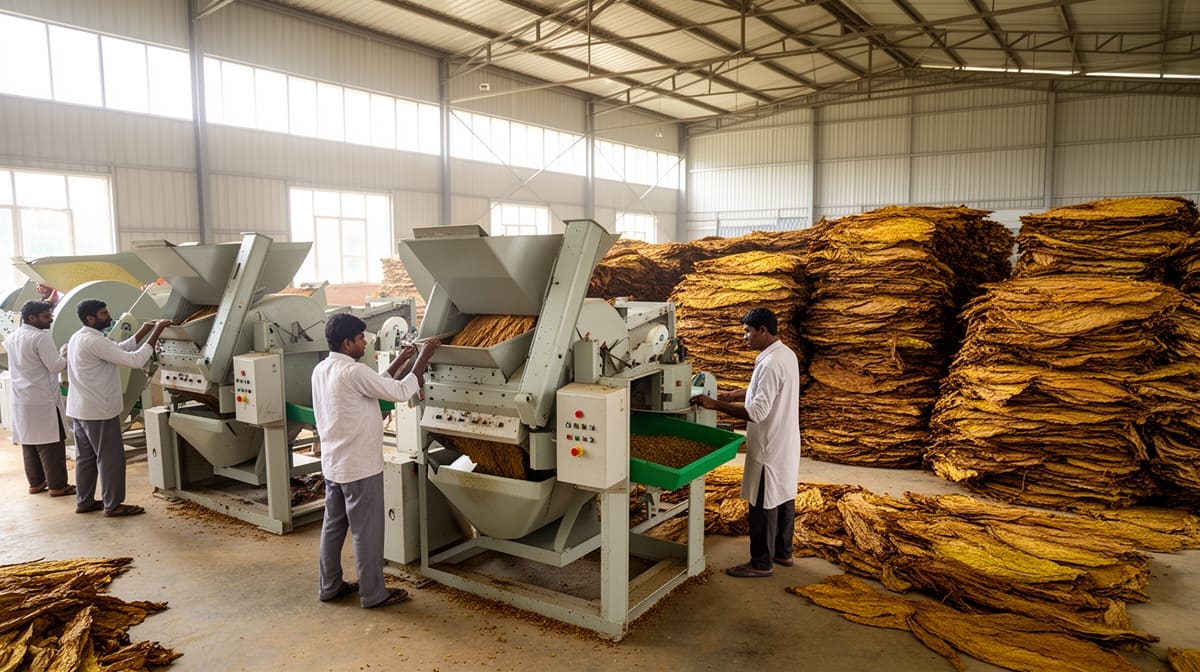
- The respondent’s process involves mechanical separation of leaves from stems, moisture control, and packing - none of which alter the essential character of tobacco.
- The Department relied on Board’s Circular No.143/12/2011, dated 26.05.2011, but argued that the tobacco processed was no longer ‘primary agricultural produce’.
- The respondent’s processing was distinguished from manufacturing, as no new product was created; tobacco remained tobacco.
- The Ministry of Agriculture, through its Directorate of Marketing and Inspection, confirmed in a letter dated 20.10.2010 that threshing is a post-harvest agricultural quality control operation that does not change the product’s identity.
Procedural History
- 21.12.2016: Adjudicating Authority issued Order-in-Original (OIO) confirming service tax demand of Rs.1,66,98,271/-, interest, and penalty.
- 31.01.2018: Commissioner (Appeals) set aside the OIO, holding the activity exempt as processing of agricultural produce.
- 25.11.2025: Hearing before CESTAT Hyderabad.
- 13.03.2026: Final Order passed by CESTAT dismissing the Department’s appeal.
Relief Sought
The Department sought to set aside the Commissioner (Appeals)’s order dated 31.01.2018 and restore the adjudicating authority’s demand of Rs.1,66,98,271/-, along with interest and penalty. The respondent sought dismissal of the appeal, affirming the exemption.
The Legal Issue
The central question was whether the threshing and re-drying of cured tobacco leaves on a job work basis qualifies as Business Auxiliary Service liable to service tax, or whether it constitutes processing of agricultural produce exempt under Notification No.14/2004-ST.
Arguments Presented
For the Appellant
The Department contended that:
- The tobacco processed by the respondent was no longer ‘primary agricultural produce’ as it had undergone curing and fermentation, which altered its essential character.
- The activity involved large machinery, skilled labor, and value addition, making it commercial processing.
- The Board’s Circular No.143/12/2011 was inapplicable because it applied only to threshing and drying of raw tobacco, not cured tobacco.
- The Service Tax (Removal of Difficulty) Order, 2002, excluded processed tobacco from the definition of agricultural produce.
- The respondent’s services were essential for cigarette manufacturing and thus fell under commercial activity.
For the Respondent
The respondent argued that:
- The activity was squarely covered by the Tribunal’s earlier decision in Green Leaf Tobacco Threshers Ltd v. CCE & ST, Guntur (Common Order No. A/30302-30350/2017), which held such processing exempt.
- The Supreme Court had dismissed the Department’s appeal against that order, making it binding precedent.
- The process did not alter the essential character of tobacco; it merely stabilized it for storage and export.
- The Ministry of Agriculture’s letter confirmed threshing as a post-harvest agricultural operation.
- Revenue authorities cannot override Board circulars.
The Court's Analysis
The Tribunal emphasized that the issue had been conclusively settled in its own coordinate bench decision in Green Leaf Tobacco Threshers Ltd, which was affirmed by the Supreme Court in [2018 (18) GSTL J38 (SC)]. The Court held that judicial discipline required adherence to binding precedent unless facts were materially distinguishable.
"The activity of threshing and redrying of tobacco leaves does not result in manufacture of any new product. The essential characteristic of tobacco remains unchanged. The activity is in relation to agricultural produce and such activity is not liable to service tax under BAS."
The Court examined the definition of ‘agricultural produce’ under the Service Tax (Removal of Difficulty) Order, 2002, which includes produce on which no further processing is done, or processing done by the cultivator that does not alter its essential characteristics. The Tribunal found that the respondent’s activities - mechanical separation, drying, and packing - were consistent with post-harvest operations aimed at market readiness, not commercial manufacturing.
The Department’s reliance on the distinction between ‘processed’ and ‘manufactured’ goods was rejected, as the product remained tobacco. The Ministry of Agriculture’s confirmation that threshing was an agricultural quality control measure further supported the exemption.
The Court also noted that the Department failed to demonstrate any factual distinction between the present case and Green Leaf Tobacco Threshers Ltd. Absent such distinction, the earlier precedent governed.
The Verdict
The appeal filed by the Commissioner of Central Tax was dismissed. The order of the Commissioner (Appeals) dated 31.01.2018, which set aside the service tax demand of Rs.1,66,98,271/-, interest, and penalty, was upheld. The Tribunal confirmed that threshing and re-drying of cured tobacco leaves on job work basis is exempt from service tax as processing of agricultural produce under Notification No.14/2004-ST.
What This Means For Similar Cases
Processing of Agricultural Produce Is Exempt Even After Auction
- Practitioners can now confidently argue that post-auction processing of agricultural commodities like tobacco, cashew, or cotton by third parties remains exempt if it preserves essential character.
- The auction process does not convert agricultural produce into a commercial commodity for tax purposes.
- Any attempt to tax such services under BAS must overcome the presumption of exemption under Notification 14/2004-ST.
Precedent Binding Even Without Direct Citation
- When a coordinate bench has ruled on identical facts and the Supreme Court has affirmed it, subsequent benches must follow the precedent.
- Revenue authorities cannot re-litigate settled issues merely by re-arguing statutory interpretation.
- Tax officers must review existing tribunal and Supreme Court rulings before initiating reassessments.
Clarification on ‘Essential Character’ in Agro-Processing
-
The test is not whether value is added, but whether the product’s identity changes.
-
Stabilization, drying, and packing for export do not constitute manufacturing.
-
Industry players in agro-processing (e.g., tea, coffee, spices) may rely on this ruling to challenge BAS assessments.
-
If a process is recognized by the Ministry of Agriculture as post-harvest quality control, it is likely exempt.
-
Documentation from agricultural authorities should be proactively submitted in tax disputes.