Topic

Insurance Claim

An insurance claim in India involves seeking compensation from an insurer for losses covered under a policy, governed by the Insurance Act, Consumer Protection Act, and judicial precedents.

28 articlesLatest 3 weeks ago
17-Year Dependency Multiplier Upheld Using Post-Mortem Income-Tax Returns in Motor Accident Compensation | Motor Vehicles Act : JHHC
Case Law Analysis
|Jharkhand High Court

17-Year Dependency Multiplier Upheld Using Post-Mortem Income-Tax Returns in Motor Accident Compensation | Motor Vehicles Act : JHHC

Jharkhand High Court affirmed that the claimant is entitled to a loss-of-dependency award calculated on a 17-year multiplier, relying on the deceased’s post-mortem income-tax returns. The ruling clarifies that tax returns can be admitted as proof of earnings for dependency calculations under the Motor Vehicles Act, raising the compensation ceiling for families of road-accident victims.

Special Purpose Vehicle Exempt from Periodical Inspection Certificate; Insurer Must Pay 75% of IDV with Interest | Gujarat Motor Vehicles Rules : Gujarat CDC
Case Law Analysis

Special Purpose Vehicle Exempt from Periodical Inspection Certificate; Insurer Must Pay 75% of IDV with Interest | Gujarat Motor Vehicles Rules : Gujarat CDC

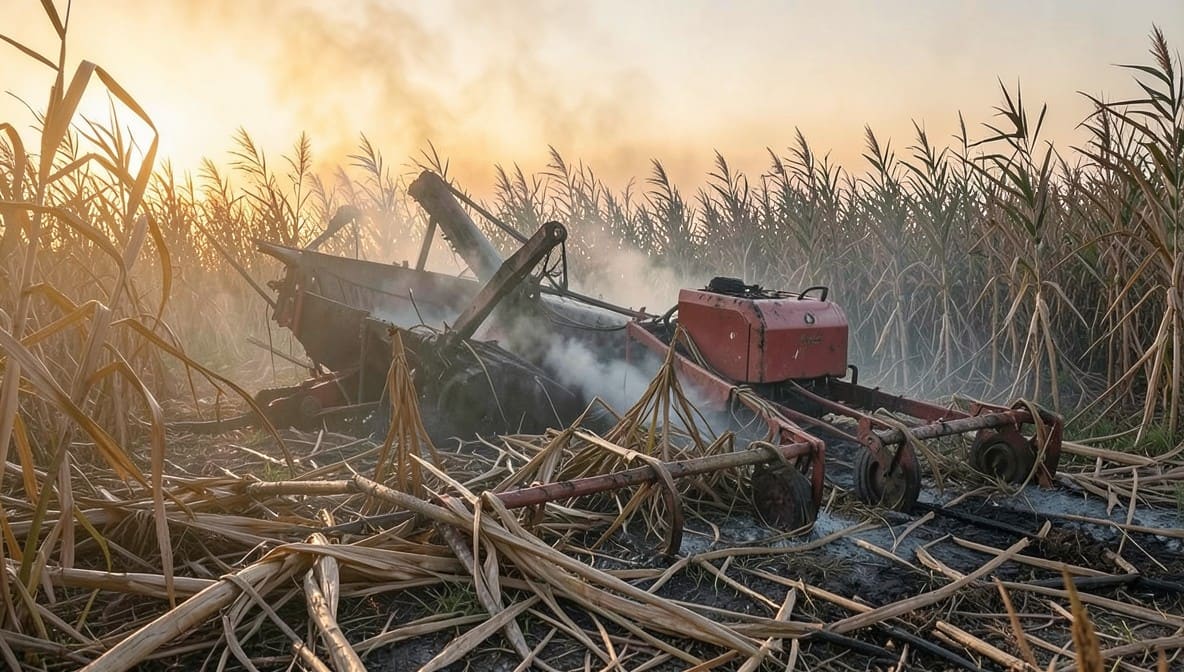
The Gujarat CDC ruled that a sugar-cane harvester, classified as a special-purpose vehicle, is not required to obtain a periodical inspection certificate under the Gujarat Motor Vehicles Rules. Consequently, the insurer must settle 75 % of the Insured Declared Value with interest, clarifying claim-settlement obligations for owners of similar agricultural equipment.

Clause 5.16 diagnostic exclusion not applicable to invasive electrophysiological study | Consumer Protection Act 2019 - Insurance claim : W.B. SCDRC
Case Law Analysis

Clause 5.16 diagnostic exclusion not applicable to invasive electrophysiological study | Consumer Protection Act 2019 - Insurance claim : W.B. SCDRC

The West Bengal State Consumer Disputes Redressal Commission ruled that an electrophysiological study (EPS) is an invasive procedure and therefore falls outside the policy’s diagnostic exclusion clause. It ordered the insurer to pay the cashless claim of Rs 49,119, plus Rs 50,000 compensation and Rs 5,000 costs, signalling that insurers must honour coverage for such invasive diagnostics.

Functional disability assessed against earning capacity; unsubstantiated future medical expenses struck down in motor accident compensation : JKHC
Case Law Analysis
|Jammu & Kashmir and Ladakh High Court

Functional disability assessed against earning capacity; unsubstantiated future medical expenses struck down in motor accident compensation : JKHC

The JK High Court cut the motor-accident award by mandating that functional disability be measured against the claimant’s earning capacity, rejecting a 100 % disability assumption. It also struck a Rs 1 lakh future-medical expense claim with no proof. Insurers and claimants must now base compensation on realistic loss of earnings.

Flawed Surveyor Report Invalidates Insurer's Settlement Offer | Authorized Dealer Estimate Validated as Reasonable Claim Basis : Punjab SCDRC
Case Law Analysis
|Punjab and Haryana High Court

Flawed Surveyor Report Invalidates Insurer's Settlement Offer | Authorized Dealer Estimate Validated as Reasonable Claim Basis : Punjab SCDRC

The Punjab State Consumer Commission ruled that insurers cannot rely on defective surveyor reports to deny full claims. When the authorized dealer's repair estimate is reasonable and substantiated, it forms the valid basis for settlement - reinforcing consumer rights under the Consumer Protection Act and setting a precedent against arbitrary insurer assessments.

Carriers Act 1865, Section 7 | Absolute Liability for Transit Damage + Automatic Subrogation Valid Without Formal Assignment : Kerala HC
Case Law Analysis
|Kerala High Court

Carriers Act 1865, Section 7 | Absolute Liability for Transit Damage + Automatic Subrogation Valid Without Formal Assignment : Kerala HC

The Kerala High Court affirmed that common carriers are absolutely liable for goods damage during transit under Section 7 of the Carriers Act 1865, and that insurers automatically acquire subrogation rights upon indemnifying the consignor -无需 formal subrogation letters. This clarifies a critical procedural shortcut for insurance claims in logistics disputes, reducing litigation barriers for carriers and insurers alike.

Insurance Claim | Pre-existing Condition Does Not Bar Payout If Accident Is Proximate Cause: Rajasthan HC | Burden of Proof on Insurer
Case Law Analysis
|Rajasthan High Court

Insurance Claim | Pre-existing Condition Does Not Bar Payout If Accident Is Proximate Cause: Rajasthan HC | Burden of Proof on Insurer

The Rajasthan High Court held that an insurer cannot deny a death claim merely because the deceased had a pre-existing heart condition - the burden lies squarely on the insurer to prove the condition, not the accident, caused death. Without corroborative medical evidence linking the condition to the fatality, the claim must be upheld, reinforcing protections for beneficiaries under accident-based policies.

Consumer Protection Act | Delay in FIR Not Sole Ground for Insurance Claim Repudiation : Maharashtra State Consumer Commission
Case Law Analysis

Consumer Protection Act | Delay in FIR Not Sole Ground for Insurance Claim Repudiation : Maharashtra State Consumer Commission

The Maharashtra State Consumer Commission ruled that insurers cannot reject genuine vehicle theft claims solely due to delayed FIR filing or late intimation, unless fraud is proven. The decision reinforces that procedural lapses alone do not constitute deficiency in service under the Consumer Protection Act, 1986, protecting policyholders from arbitrary claim denials.

Section 22C LSA | No Prior Notice Required to File Claim Before Permanent Lok Adalat; Participation Waives Procedural Defects : Punjab & Haryana HC
Case Law Analysis
|Punjab and Haryana High Court

Section 22C LSA | No Prior Notice Required to File Claim Before Permanent Lok Adalat; Participation Waives Procedural Defects : Punjab & Haryana HC

The Punjab & Haryana High Court has ruled that filing a claim before a Permanent Lok Adalat under Section 22C of the Legal Services Authorities Act does not require a prior notice to the insurer, and any procedural objections are deemed waived if the party actively participates in the proceedings. This empowers claimants to bypass pre-filing formalities while holding insurers accountable for engaging in the process, significantly streamlining insurance claim resolution under consumer protection frameworks.

Counsel’s Factual Concession Binds Client in Consumer Proceedings: NCDRC Upholds Remand Despite Procedural Irregularities
Case Law Analysis

Counsel’s Factual Concession Binds Client in Consumer Proceedings: NCDRC Upholds Remand Despite Procedural Irregularities

The National Consumer Disputes Redressal Commission (NCDRC) ruled that a counsel’s concession on factual matters during consumer proceedings is binding on the client, even if it leads to a remand order. This decision underscores the finality of counsel’s admissions in consumer disputes, limiting the client’s ability to challenge procedural irregularities post-concession.

Arbitration Clause | Partial Payment of Insurance Claim Admits Liability; Dispute Over Balance Is Quantum, Not Arbitrability : Bombay HC
Case Law Analysis
|Bombay High Court

Arbitration Clause | Partial Payment of Insurance Claim Admits Liability; Dispute Over Balance Is Quantum, Not Arbitrability : Bombay HC

The Bombay High Court has ruled that when an insurer pays part of an insurance claim, it constitutes an admission of liability for the entire claim, and any dispute over the unpaid balance relates only to quantum-not arbitrability. This clarifies that policyholders can compel arbitration for residual amounts even when insurers attempt to sever liability from payment, reinforcing the enforceability of arbitration clauses in commercial insurance disputes.