Tribunals and Commissions judgments

1770 Tribunals and Commissions judgments explained in plain English: what was decided, the law applied and why it matters. Page 56 of 74.

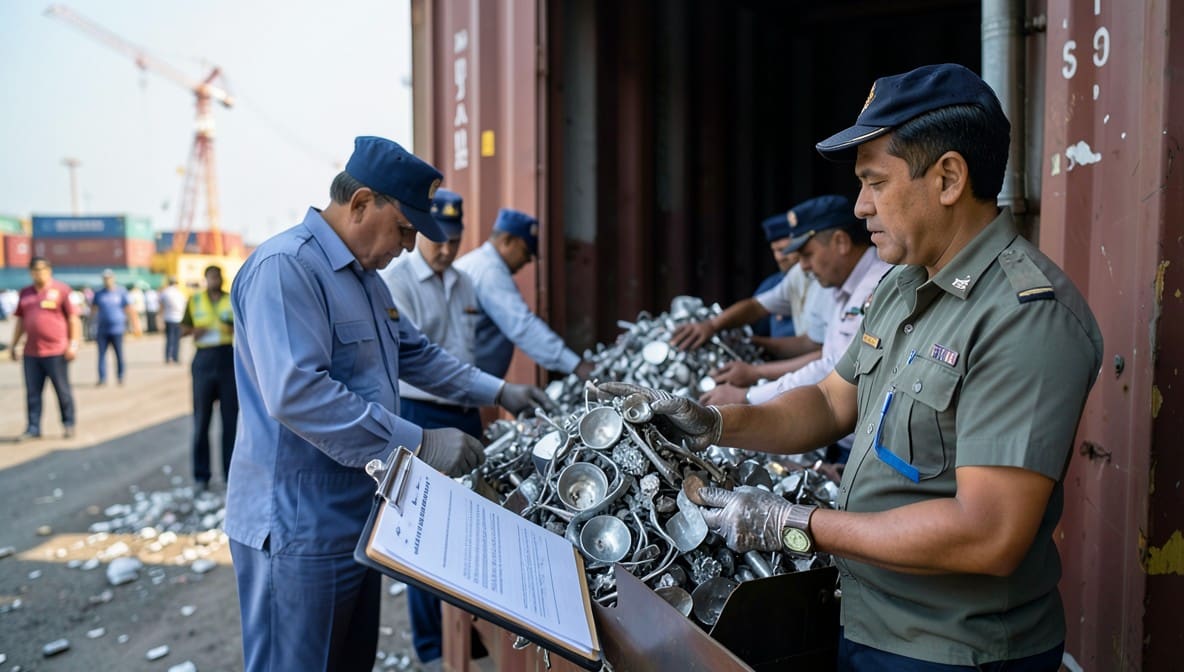
ASEAN-India FTA Rules of Origin | Substantial Compliance Suffices for Duty Exemption Despite Missing COO Markings on Scrap : CESTAT Chennai
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

ASEAN-India FTA Rules of Origin | Substantial Compliance Suffices for Duty Exemption Despite Missing COO Markings on Scrap : CESTAT Chennai

CESTAT Chennai rules that the absence of Country of Origin (COO) markings on aluminium scrap does not invalidate preferential duty exemption under the ASEAN-India FTA if all documentary evidence is verified. The Tribunal emphasizes that physical markings are not mandatory for scrap goods, reinforcing the principle of substantial compliance in trade agreements.
Section 80IA Deduction | 1789-Day Delay Condoned for Bonafide Reliance on Wrong Legal Advice : ITAT Nagpur
Case Law Analysis
|Income Tax Appellate Tribunal

Section 80IA Deduction | 1789-Day Delay Condoned for Bonafide Reliance on Wrong Legal Advice : ITAT Nagpur

ITAT Nagpur condoned a 1789-day delay in filing an appeal under Section 80IA, holding that bonafide reliance on incorrect legal advice constitutes 'sufficient cause' for condonation. The Tribunal restored the case to the Assessing Officer for merits-based adjudication, emphasizing that procedural lapses should not bar substantive justice when the assessee acted in good faith.

Quashed Suspension Period Must Be Regularized as Duty for Pension & Service Benefits: CAT Ernakulam
Case Law Analysis
|Central Administrative Tribunal

Quashed Suspension Period Must Be Regularized as Duty for Pension & Service Benefits: CAT Ernakulam

CAT Ernakulam rules that once a suspension order is quashed and not revived, the period of unauthorized absence must be treated as duty for pension and service benefits. The ruling reinforces that disciplinary proceedings, if invalidated, cannot deprive employees of retiral dues, setting a precedent for service law disputes involving government servants.

Retrospective Effect of Beneficial DGFT Notifications | CESTAT Chennai Allows Home Consumption of Prohibited Goods Post-Redemption Under Customs Act
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

Retrospective Effect of Beneficial DGFT Notifications | CESTAT Chennai Allows Home Consumption of Prohibited Goods Post-Redemption Under Customs Act

CESTAT Chennai ruled that beneficial amendments to DGFT notifications apply retrospectively, permitting importers to clear goods for home consumption even if they were prohibited at the time of import. The decision clarifies that redemption fines paid under protest do not bar subsequent relief under amended notifications, impacting importers facing similar disputes.

Foreign Origin Markings Insufficient to Prove Smuggling Under Section 111(b) Customs Act | CESTAT Allahabad Sets Stricter Burden of Proof Standard
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

Foreign Origin Markings Insufficient to Prove Smuggling Under Section 111(b) Customs Act | CESTAT Allahabad Sets Stricter Burden of Proof Standard

CESTAT Allahabad rules that mere foreign origin markings on goods do not constitute sufficient evidence for smuggling charges under the Customs Act. The revenue must provide corroborative proof, including seizure at a customs station or direct linkage to illegal import, to sustain confiscation and penalties. The judgment reinforces the need for substantive evidence beyond labeling to establish smuggling allegations.

Compensatory Afforestation Mandatory for Illegal Tree Felling Under Solid Waste Management Rules 2016 : NGT Directs 1800 Trees Plantation for Faridabad Violations
Case Law Analysis
|National Green Tribunal

Compensatory Afforestation Mandatory for Illegal Tree Felling Under Solid Waste Management Rules 2016 : NGT Directs 1800 Trees Plantation for Faridabad Violations

NGT holds that illegal tree felling for solid waste management projects triggers mandatory compensatory afforestation, even if the facility is not a landfill. The Tribunal directed Municipal Corporation Faridabad to plant 1800 trees and tasked HSPCB with compliance assessment within three months, reinforcing environmental accountability under the Solid Waste Management Rules 2016.

Section 87A Rebate Applies to STCG Taxed Under Section 111A for New Tax Regime Assessees : ITAT Surat
Case Law Analysis
|Income Tax Appellate Tribunal

Section 87A Rebate Applies to STCG Taxed Under Section 111A for New Tax Regime Assessees : ITAT Surat

ITAT Surat rules that rebate under Section 87A is available on short-term capital gains taxed at 15% under Section 111A, even for assessees opting for the new tax regime (Section 115BAC), provided total income does not exceed ₹7 lakh. This clarifies a critical ambiguity for taxpayers navigating the interplay between rebate provisions and capital gains taxation.

NGT Mandates Bio-Mining & Rs. 60 Lakh Compensation for Legacy Waste Dumping in Abandoned Quarry Under SWM Rules 2016 : NGT Southern Zone
Case Law Analysis
|National Green Tribunal

NGT Mandates Bio-Mining & Rs. 60 Lakh Compensation for Legacy Waste Dumping in Abandoned Quarry Under SWM Rules 2016 : NGT Southern Zone

NGT Southern Zone directs immediate bio-mining of 18-year-old unsegregated waste dumped in a Kerala quarry, holding the local panchayat and state authorities liable for environmental restoration. The Rs. 60 lakh compensation must be utilized strictly for remediation, reinforcing compliance with Solid Waste Management Rules 2016 and local body accountability for legacy dumping sites.

Service Tax Exemption for Residential Construction of Fewer Than 12 Units | CESTAT Kolkata Invalidates Demand Based on Bank-ST-3 Comparison Alone
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

Service Tax Exemption for Residential Construction of Fewer Than 12 Units | CESTAT Kolkata Invalidates Demand Based on Bank-ST-3 Comparison Alone

CESTAT Kolkata rules that residential construction projects with fewer than 12 units are exempt from service tax under the Finance Act, 1994. The tribunal quashed the demand, holding that reliance solely on ST-3 form and bank statement comparisons without substantive evidence lacks legal basis, setting a precedent for audit compliance challenges.

Nomination Under CCS Pension Rules Does Not Override Legal Heir Rights | Family Pension Entitlement Based on SDM Certificate: CAT
Case Law Analysis
|Central Administrative Tribunal

Nomination Under CCS Pension Rules Does Not Override Legal Heir Rights | Family Pension Entitlement Based on SDM Certificate: CAT

Central Administrative Tribunal rules that a nomination for family pension under CCS Pension Rules is not absolute; the legal heir (spouse) proven by an SDM certificate is entitled to the pension, even if the deceased nominated others. The ruling clarifies that nomination merely facilitates disbursement but does not extinguish the rights of legal heirs under succession laws.

Section 148A Income Tax Act | Notice Issued Post-01-04-2021 Must Follow New Procedure: ITAT Agra Quashes Reassessment for Non-Compliance
Case Law Analysis
|Income Tax Appellate Tribunal

Section 148A Income Tax Act | Notice Issued Post-01-04-2021 Must Follow New Procedure: ITAT Agra Quashes Reassessment for Non-Compliance

ITAT Agra rules that reassessment notices issued under Section 148 of the Income Tax Act on or after 01-04-2021 must strictly comply with the amended Section 148A procedure. Failure to do so renders the notice invalid, quashing the entire reassessment proceedings. This decision reinforces procedural safeguards for taxpayers against arbitrary reopening of assessments.

Section 148 IT Act | Reassessment Notice Issued Beyond Limitation Period Void After Supreme Court's Rajeev Bansal Ruling : ITAT Agra
Case Law Analysis
|Income Tax Appellate Tribunal

Section 148 IT Act | Reassessment Notice Issued Beyond Limitation Period Void After Supreme Court's Rajeev Bansal Ruling : ITAT Agra

ITAT Agra quashed reassessment notices issued on 30.07.2022 for AYs 2013-14 and 2014-15, holding that the notices exceeded the limitation period under Section 148 of the IT Act post the Supreme Court's decision in Rajeev Bansal. The tribunal ruled that the legal fiction expiry bars reassessment notices issued beyond the prescribed timeline, reinforcing the binding precedent on tax authorities.

NGT Southern Zone | One-Time Effluent Discharge Rectification Does Not Absolve Ongoing Pollution Liability : NGT Mandates Continuous Compliance Monitoring
Case Law Analysis
|National Green Tribunal

NGT Southern Zone | One-Time Effluent Discharge Rectification Does Not Absolve Ongoing Pollution Liability : NGT Mandates Continuous Compliance Monitoring

The National Green Tribunal (Southern Zone) ruled that a polluter’s isolated corrective action after effluent discharge does not exempt it from penalties if ongoing violations persist. The judgment underscores TNPCB’s duty to enforce continuous environmental compliance, not just post-facto remediation, impacting industries and pollution control boards across India.

Section 69 IT Act | Cash Deposits Taxable Only on Proof of Beneficial Ownership : ITAT Ahmedabad Limits Tax Addition to Peak Balance & Commission Income
Case Law Analysis
|Income Tax Appellate Tribunal

Section 69 IT Act | Cash Deposits Taxable Only on Proof of Beneficial Ownership : ITAT Ahmedabad Limits Tax Addition to Peak Balance & Commission Income

ITAT Ahmedabad rules that unexplained cash deposits under Section 69 IT Act cannot be taxed in full without evidence linking the assessee to beneficial ownership. The tribunal directed reassessment based on peak balance and permissible commission income, narrowing the scope of tax additions for accommodation entries.

Section 27 Customs Act | 12% Interest Mandatory on Refund of Deposits Made Under Mistaken Liability : CESTAT Kolkata
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

Section 27 Customs Act | 12% Interest Mandatory on Refund of Deposits Made Under Mistaken Liability : CESTAT Kolkata

CESTAT Kolkata reaffirms that refunds of customs deposits made under a mistaken notion of liability attract 12% interest from the date of deposit to refund. The ruling underscores the government’s obligation to compensate importers for unlawful retention of funds, reinforcing judicial precedent on restitution under Section 27 of the Customs Act.

Section 12A(1)(ac)(iii) IT Act | Registration Cannot Be Denied for Missing MOA Clauses If Society Is Genuine and Willing to Amend: ITAT Amritsar
Case Law Analysis
|Income Tax Appellate Tribunal

Section 12A(1)(ac)(iii) IT Act | Registration Cannot Be Denied for Missing MOA Clauses If Society Is Genuine and Willing to Amend: ITAT Amritsar

ITAT Amritsar rules that registration under Section 12A(1)(ac)(iii) of the Income Tax Act cannot be denied solely for missing clauses in the Memorandum of Association if the society's activities are genuine and it undertakes to incorporate the required clauses. This decision clarifies procedural compliance requirements for tax exemptions, impacting religious and charitable societies seeking registration.

Section 250 IT Act | CIT(A) Must Adjudicate Appeals on Merits, Not Dismiss for Non-Prosecution : ITAT Amritsar
Case Law Analysis
|Income Tax Appellate Tribunal

Section 250 IT Act | CIT(A) Must Adjudicate Appeals on Merits, Not Dismiss for Non-Prosecution : ITAT Amritsar

ITAT Amritsar rules that the Commissioner of Income Tax (Appeals) cannot dismiss an appeal under Section 250 of the Income Tax Act merely for non-prosecution. The appellate authority must decide the case on merits, ensuring compliance with principles of natural justice and statutory duty. This ruling reinforces the obligation of CIT(A) to adjudicate appeals substantively, impacting taxpayers facing procedural dismissals.

CRZ Notification 2011 | Demolition Orders Void Outside CRZ Boundaries: NGT Western Zone Upholds Natural Justice
Case Law Analysis
|National Green Tribunal

CRZ Notification 2011 | Demolition Orders Void Outside CRZ Boundaries: NGT Western Zone Upholds Natural Justice

NGT Western Zone rules that demolition orders under the CRZ Notification 2011 are invalid if structures lie outside designated CRZ boundaries, even if adjacent to illegal constructions. The tribunal emphasized adherence to natural justice, quashing orders that failed to consider pre-1991 existence proofs or provide reasoned decisions. The ruling sets a precedent for territorial jurisdiction limits in coastal regulation enforcement.

Natural Justice in Tax Proceedings | Failure to Serve Notice Invalidates Cash Addition Under Section 147 : ITAT Amritsar
Case Law Analysis
|Income Tax Appellate Tribunal

Natural Justice in Tax Proceedings | Failure to Serve Notice Invalidates Cash Addition Under Section 147 : ITAT Amritsar

ITAT Amritsar ruled that an unexplained cash addition under Section 147 of the Income Tax Act is invalid if the assessee was not served proper notice or given an opportunity to be heard. The tribunal remanded the case for fresh adjudication, reinforcing that procedural fairness is mandatory in tax assessments, impacting all taxpayers facing similar disputes.