Tribunals and Commissions judgments

1770 Tribunals and Commissions judgments explained in plain English: what was decided, the law applied and why it matters. Page 39 of 74.

Section 68 IT Act | ITAT Delhi Mandates Corroborative Evidence & Cross-Examination Rights for Unexplained Cash Credits : ITAT Delhi
Case Law Analysis
|Income Tax Appellate Tribunal

Section 68 IT Act | ITAT Delhi Mandates Corroborative Evidence & Cross-Examination Rights for Unexplained Cash Credits : ITAT Delhi

ITAT Delhi quashed Rs. 49.5L and Rs. 54.5L additions under Section 68, ruling that additions cannot stand without incriminating material or opportunity for cross-examination. The decision reinforces natural justice principles in income tax assessments, impacting taxpayers facing similar allegations of accommodation entries.
IBC | Late Expression of Interest Invalid Without Fresh CoC Invitation: NCLAT Reaffirms Strict Procedural Compliance in CIRP
Case Law Analysis
|National Company Law Appellate Tribunal

IBC | Late Expression of Interest Invalid Without Fresh CoC Invitation: NCLAT Reaffirms Strict Procedural Compliance in CIRP

NCLAT rules that resolution applicants excluded from Form G’s final list cannot participate in CIRP, even if their delayed EOI is condoned, unless the Committee of Creditors issues a fresh invitation. The decision underscores the IBC’s zero-tolerance approach to procedural lapses, impacting distressed asset resolution timelines and stakeholder rights.

Section 95 IBC | Non-Est Petition During Interim Moratorium Cannot Trigger Fresh Moratorium: NCLAT
Case Law Analysis
|National Company Law Appellate Tribunal

Section 95 IBC | Non-Est Petition During Interim Moratorium Cannot Trigger Fresh Moratorium: NCLAT

NCLAT rules that a petition filed during an existing interim moratorium under Section 95 IBC is non-est and incapable of initiating a fresh moratorium, reinforcing procedural safeguards against abuse of process in personal guarantor insolvency cases. The decision clarifies that only a validly admitted petition can trigger moratorium protections.

NGT Southern Zone Mandates Ballast Water Regulation & Dredging to Combat Invasive Mussel Infestation : NGT Sets Precedent for Ecological Restoration
Case Law Analysis
|National Green Tribunal

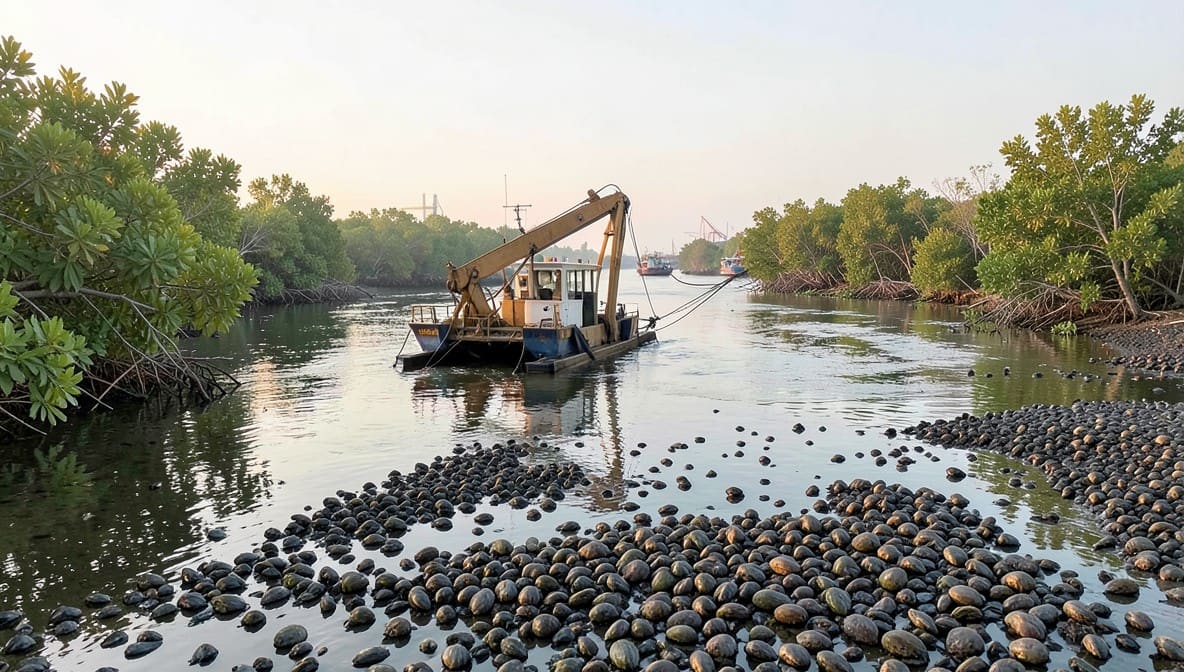
NGT Southern Zone Mandates Ballast Water Regulation & Dredging to Combat Invasive Mussel Infestation : NGT Sets Precedent for Ecological Restoration

The National Green Tribunal Southern Zone directed comprehensive measures, including ballast water regulation, dredging, and bioresource utilization, to control the invasive Mytella strigata mussel in Ennore-Pulicat wetlands. The ruling protects native fisheries and traditional livelihoods by addressing ecological imbalance caused by unchecked invasive species proliferation.

DoPT Guidelines | Recovery from Retired Group-D Employee’s DCRG Impermissible Without Pre-Retirement Scrutiny: CAT Patna
Case Law Analysis
|Central Administrative Tribunal

DoPT Guidelines | Recovery from Retired Group-D Employee’s DCRG Impermissible Without Pre-Retirement Scrutiny: CAT Patna

CAT Patna quashed the recovery of Rs. 1,62,473 from a retired Group-D employee’s DCRG, ruling that pre-retirement pay fixation errors cannot be rectified post-retirement without following DoPT O.M. dated 02.03.2016. The tribunal emphasized that recoveries from pensionary benefits violate natural justice and statutory protections for retired employees.

Doctrine of Proportionality | CAT Ahmedabad Quashes Dismissal of Postman for Undelivered Mail Amid Staff Shortage & Medical Leave : CAT Ahmedabad
Case Law Analysis
|Central Administrative Tribunal

Doctrine of Proportionality | CAT Ahmedabad Quashes Dismissal of Postman for Undelivered Mail Amid Staff Shortage & Medical Leave : CAT Ahmedabad

CAT Ahmedabad invoked the doctrine of proportionality to set aside the dismissal of a postman who failed to deliver 10,000 mail articles due to staff shortages and medical leave. The Tribunal remitted the punishment for reconsideration, emphasizing that disciplinary action must account for mitigating circumstances and natural justice principles under the CCS (CCA) Rules.

Qualifying Service for Pension | Employer Bears Burden of Record Maintenance: CAT Ahmedabad Rules Missing Records Cannot Defeat Entitlement
Case Law Analysis
|Central Administrative Tribunal

Qualifying Service for Pension | Employer Bears Burden of Record Maintenance: CAT Ahmedabad Rules Missing Records Cannot Defeat Entitlement

CAT Ahmedabad holds that employers cannot exclude service periods from pension calculations due to unavailable records, placing the onus on them to maintain accurate service documentation. The ruling reinforces that pension entitlements cannot be denied on procedural grounds, ensuring protection for retired employees under service law.

CCS Pension Rules | Withholding Pension & Gratuity for Unrelated Criminal Case Violates Due Process & Right to Life: CAT Principal Bench
Case Law Analysis
|Central Administrative Tribunal

CCS Pension Rules | Withholding Pension & Gratuity for Unrelated Criminal Case Violates Due Process & Right to Life: CAT Principal Bench

CAT Principal Bench rules that denying full pension and gratuity to a retired government servant due to a pending criminal case unrelated to official duties is illegal and violates Article 21. The Tribunal directed payment within three months, emphasizing that provisional pension alone is insufficient and discriminatory when co-accused received full benefits. This sets a precedent for fair treatment under service law and pension jurisprudence.

NGT Southern Zone | Environmental Clearance & Lease Renewal Mandatory for Industrial Operations: Directions to Andhra Paper Mill on Effluent Disposal & Land Use Compliance
Case Law Analysis
|National Green Tribunal

NGT Southern Zone | Environmental Clearance & Lease Renewal Mandatory for Industrial Operations: Directions to Andhra Paper Mill on Effluent Disposal & Land Use Compliance

The National Green Tribunal (Southern Zone) ruled that industrial continuity hinges on strict compliance with environmental clearance and lease renewal conditions. The court directed Andhra Paper Mill to implement its approved effluent disposal plan and urged the East Godavari Collector to decide on the expired lease for Turupulanka discharge lagoons, emphasizing that non-compliance risks operational shutdowns and ecological harm.

Section 56 Income Tax Act | Notional Interest Entries in Seized Diaries Not Taxable as Real Income : ITAT Ahmedabad
Case Law Analysis
|Income Tax Appellate Tribunal

Section 56 Income Tax Act | Notional Interest Entries in Seized Diaries Not Taxable as Real Income : ITAT Ahmedabad

ITAT Ahmedabad clarifies that notional interest entries found in seized diaries do not constitute taxable income under Section 56 of the Income Tax Act, preventing double taxation. The ruling reinforces that only real accrual of income, not hypothetical accounting entries, can be taxed, offering relief to assessees facing arbitrary additions based on seized documents.

Section 115BBE Not Retrospective | Cash Deposits During Demonetisation Not Automatically Taxable as Unexplained Income : ITAT Delhi
Case Law Analysis
|Income Tax Appellate Tribunal

Section 115BBE Not Retrospective | Cash Deposits During Demonetisation Not Automatically Taxable as Unexplained Income : ITAT Delhi

ITAT Delhi rules that Section 115BBE of the Income Tax Act applies only post-01.04.2017, reducing a Rs. 1.49 crore addition to Rs. 5 lakh for cash deposits during demonetisation. The tribunal emphasised that regular business activities and cash sales in unorganised sectors justify a lower addition, setting a precedent for similar assessments.

Closure Orders Under Water & Air Acts Trump Expired Consent to Operate : NGT Southern Zone Upholds Industrial Shutdown on Agricultural Land
Case Law Analysis
|National Green Tribunal

Closure Orders Under Water & Air Acts Trump Expired Consent to Operate : NGT Southern Zone Upholds Industrial Shutdown on Agricultural Land

NGT Southern Zone rules that final closure orders under the Water and Air Acts override expired 'consent to operate' for industries violating environmental norms. The judgment reinforces that regulatory compliance cannot be bypassed by procedural lapses, setting a precedent for enforcement against industries operating on non-conforming land.

AMP Expenses as Revenue Expenditure | ITAT Delhi Rejects Capitalization for Brand Building by Subsidiary
Case Law Analysis
|Income Tax Appellate Tribunal

AMP Expenses as Revenue Expenditure | ITAT Delhi Rejects Capitalization for Brand Building by Subsidiary

ITAT Delhi rules that advertisement, marketing, and sales promotion expenses incurred by a subsidiary are revenue in nature, even if they enhance the parent company’s brand. The ruling dismisses the Revenue’s appeal, reinforcing that such expenses cannot be capitalized under transfer pricing norms, offering clarity for multinational corporations on tax treatment of AMP costs.

Section 153C Income Tax Act | Assessments Time-Barred If Satisfaction Note Not Recorded Within 6 AYs: ITAT Delhi Upholds Ojjus Medicare Precedent
Case Law Analysis
|Income Tax Appellate Tribunal

Section 153C Income Tax Act | Assessments Time-Barred If Satisfaction Note Not Recorded Within 6 AYs: ITAT Delhi Upholds Ojjus Medicare Precedent

ITAT Delhi quashes assessments for AY 2014-15 and 2015-16, ruling that satisfaction notes under Section 153C must be recorded within six assessment years to validate proceedings. The tribunal reaffirms the Delhi High Court’s holding in Ojjus Medicare, emphasizing strict procedural compliance to prevent time-barred assessments.

Section 263 IT Act | Revisional Jurisdiction Barred If AO Conducted Detailed Inquiry: ITAT Ahmedabad
Case Law Analysis
|Income Tax Appellate Tribunal

Section 263 IT Act | Revisional Jurisdiction Barred If AO Conducted Detailed Inquiry: ITAT Ahmedabad

ITAT Ahmedabad sets aside a revision order under Section 263, ruling that mere disagreement with the Assessing Officer’s findings does not justify revision if the AO conducted thorough inquiries. The decision reinforces that revisional powers cannot be exercised on a change of opinion alone, safeguarding assessees from arbitrary reassessments.

Section 14A IT Act | No Disallowance Under Rule 8D If Own Funds Exceed Investments: ITAT Delhi Sets Precedent for Banking & Finance Sector
Case Law Analysis
|Income Tax Appellate Tribunal

Section 14A IT Act | No Disallowance Under Rule 8D If Own Funds Exceed Investments: ITAT Delhi Sets Precedent for Banking & Finance Sector

ITAT Delhi rules that if an assessee’s own funds surpass the value of dividend-yielding investments, disallowance under Section 14A read with Rule 8D is unwarranted-even without separate books of accounts. The ruling clarifies that the Assessing Officer must demonstrate nexus between borrowed funds and investments before invoking Rule 8D, offering relief to entities with surplus liquidity.

Section 68 IT Act | Book Entries Without Cash Flow or Genuine Transactions Cannot Be Taxed as Unexplained Income : ITAT Mumbai
Case Law Analysis
|Income Tax Appellate Tribunal

Section 68 IT Act | Book Entries Without Cash Flow or Genuine Transactions Cannot Be Taxed as Unexplained Income : ITAT Mumbai

ITAT Mumbai rules that mere book adjustments between group companies, without actual cash flow or proof of genuineness, do not constitute unexplained income under Section 68 of the Income Tax Act. The assessee’s failure to substantiate creditworthiness and transaction authenticity led to the deletion of additions.

Section 54F Income Tax Act | Partial Construction & CGAS Deposit Suffice for Capital Gains Exemption Despite Joint Ownership & Delay: ITAT Delhi
Case Law Analysis
|Income Tax Appellate Tribunal

Section 54F Income Tax Act | Partial Construction & CGAS Deposit Suffice for Capital Gains Exemption Despite Joint Ownership & Delay: ITAT Delhi

ITAT Delhi rules that depositing sale proceeds in Capital Gains Account Scheme (CGAS) and initiating partial construction are sufficient to claim Section 54F exemption, even for jointly owned property and despite court-imposed delays. The ruling clarifies that co-owners need not complete construction within the prescribed timeline to retain tax benefits, reinforcing a pragmatic approach to capital gains exemptions.

Section 167A Income Tax Act | Charitable Trusts Without Section 11 Exemption Taxed as Individuals, Not AOPs: ITAT Delhi
Case Law Analysis
|Income Tax Appellate Tribunal

Section 167A Income Tax Act | Charitable Trusts Without Section 11 Exemption Taxed as Individuals, Not AOPs: ITAT Delhi

ITAT Delhi holds that charitable trusts not availing exemption under Section 11 of the Income Tax Act must be taxed at individual slab rates, not as Associations of Persons (AOPs) under Section 167A. The ruling clarifies that trusts without defined beneficiaries or members are not AOPs, impacting tax liability calculations for non-exempt charitable entities.

Section 2(15) IT Act | Statutory Urban Development Authorities Entitled to Charitable Exemption Under Section 11 : ITAT Delhi
Case Law Analysis
|Income Tax Appellate Tribunal

Section 2(15) IT Act | Statutory Urban Development Authorities Entitled to Charitable Exemption Under Section 11 : ITAT Delhi

ITAT Delhi rules that statutory urban development authorities like Hapur Pilukhuwa Development Authority qualify as charitable institutions under Section 2(15) of the Income Tax Act, entitling them to exemption under Section 11. The tribunal affirms that development activities for public purposes fall within the ambit of 'charitable purpose,' rejecting the Revenue's argument on commercial receipts.

Section 9(1)(vi) IT Act | Live Sports Broadcasting Rights Not 'Royalty'; No TDS Under Section 195 : ITAT Delhi
Case Law Analysis
|Income Tax Appellate Tribunal

Section 9(1)(vi) IT Act | Live Sports Broadcasting Rights Not 'Royalty'; No TDS Under Section 195 : ITAT Delhi

ITAT Delhi clarifies that payments for live sports broadcasting rights do not qualify as 'royalty' under Section 9(1)(vi) of the Income Tax Act, exempting such transactions from TDS obligations under Section 195. The ruling shields broadcasters from disallowances under Section 40(a)(i) and sets a precedent for distinguishing between live rights and intellectual property royalties.

Transfer Pricing | RPT Filter Must Be Applied Uniformly; Working Capital Adjustments Require Scientific Analysis Under TNMM : ITAT Bangalore
Case Law Analysis
|Income Tax Appellate Tribunal

Transfer Pricing | RPT Filter Must Be Applied Uniformly; Working Capital Adjustments Require Scientific Analysis Under TNMM : ITAT Bangalore

ITAT Bangalore rules that the Related Party Transaction (RPT) filter must be applied uniformly across comparables in transfer pricing analyses. The Tribunal also mandates that working capital adjustments under the Transactional Net Margin Method (TNMM) must be based on average balance analysis, while interest on foreign currency receivables should be calculated using LIBOR+200 bps. The ruling sets a precedent for scientific rigor in benchmarking international transactions.