Topic

Double Taxation Avoidance Agreement

10 articlesLatest July 2026
DTAA Article 12(4)(b) | 'Make Available' Test Not Triggered Without Transfer and Retention of Technical Knowledge: ITAT Mumbai
Case Law Analysis
|Income Tax Appellate Tribunal

DTAA Article 12(4)(b) | 'Make Available' Test Not Triggered Without Transfer and Retention of Technical Knowledge: ITAT Mumbai

The ITAT Mumbai ruled that fees for research management support services do not constitute Fees for Technical Services under the India-Singapore DTAA unless the recipient receives and retains transferable technical knowledge. This clarifies the boundary between advisory support and taxable technical service, impacting multinational corporations structuring intra-group support arrangements in India.
DTAA Supremacy Over Domestic Law | ITAT Mumbai Caps Dividend Distribution Tax at Treaty Rate Under Section 90(2) : ITAT
Case Law Analysis
|Income Tax Appellate Tribunal

DTAA Supremacy Over Domestic Law | ITAT Mumbai Caps Dividend Distribution Tax at Treaty Rate Under Section 90(2) : ITAT

ITAT Mumbai rules that Dividend Distribution Tax (DDT) under Section 115-O cannot exceed the lower rate prescribed in the India-Switzerland Double Taxation Avoidance Agreement (DTAA). The decision reinforces treaty supremacy under Section 90(2) of the Income Tax Act, directly impacting multinational corporations distributing dividends to foreign shareholders.

India-Singapore DTAA | 'Make Available' Condition Mandatory for FTS Taxability Under Article 12(4)(b) : ITAT Mumbai
Case Law Analysis
|Income Tax Appellate Tribunal

India-Singapore DTAA | 'Make Available' Condition Mandatory for FTS Taxability Under Article 12(4)(b) : ITAT Mumbai

ITAT Mumbai holds that management support services do not qualify as Fees for Technical Services (FTS) under the India-Singapore DTAA unless the 'make available' condition is satisfied, clarifying the taxability of cross-border service fees for multinational enterprises. The ruling reinforces the need for technical knowledge transfer to trigger FTS taxation under tax treaties.

DTAA Article 15 | Foreign Salary Taxable Only in Country of Service Rendering : ITAT Delhi Overrules Domestic Taxation
Case Law Analysis
|Income Tax Appellate Tribunal

DTAA Article 15 | Foreign Salary Taxable Only in Country of Service Rendering : ITAT Delhi Overrules Domestic Taxation

ITAT Delhi clarifies that under Article 15 of the India-Australia DTAA, salary for services rendered abroad is taxable exclusively in the country where the services are performed, not in India. The ruling shields foreign-earned income of Indian residents from double taxation, reinforcing DTAA supremacy over domestic tax laws.

Transfer Pricing | Arm's Length Pricing Precludes Further Profit Attribution to Permanent Establishment: ITAT Delhi
Case Law Analysis
|Income Tax Appellate Tribunal

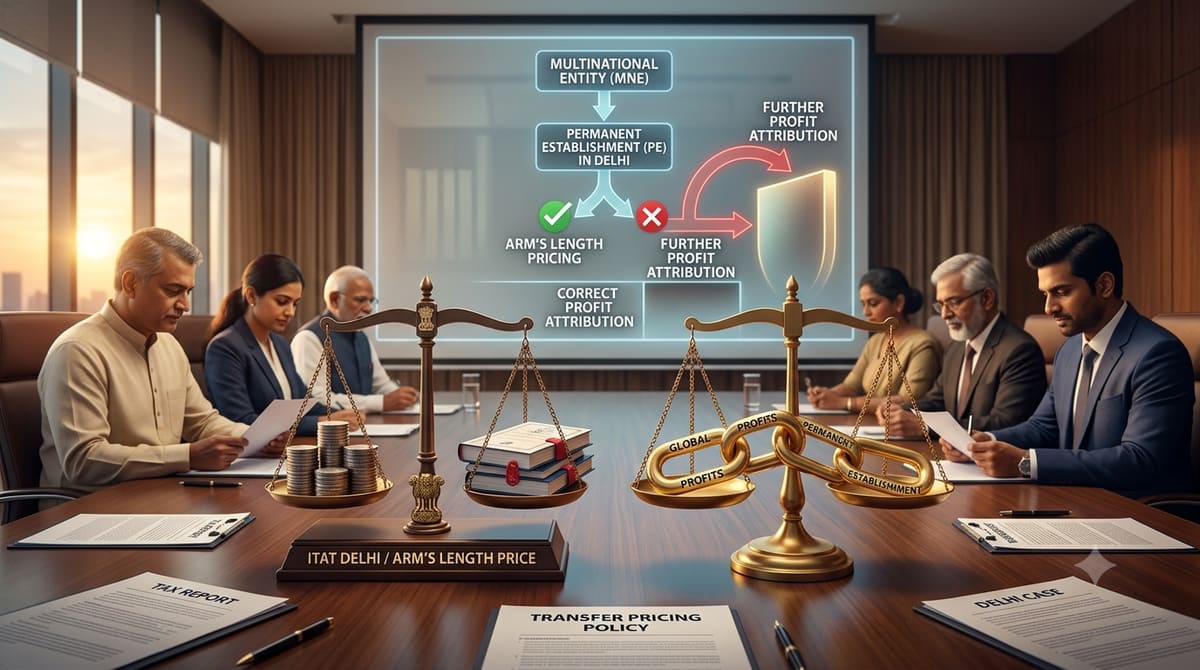
Transfer Pricing | Arm's Length Pricing Precludes Further Profit Attribution to Permanent Establishment: ITAT Delhi

The ITAT Delhi has ruled that once transfer pricing adjustments establish arm's length pricing for transactions with an associated enterprise, no additional profits can be attributed to a permanent establishment in India. This reinforces the principle that PE profit allocation must flow from the actual economic activity and pricing, not from speculative or artificial reallocations - a critical safeguard for multinational enterprises operating under DTAAs and the MLI.

Section 90 IT Act | Belated Form 67 Filing Does Not Disentitle Foreign Tax Credit Relief : ITAT Bangalore
|Income Tax Appellate Tribunal

Section 90 IT Act | Belated Form 67 Filing Does Not Disentitle Foreign Tax Credit Relief : ITAT Bangalore

ITAT Bangalore holds that a delayed Form 67 submission does not automatically disqualify a taxpayer from claiming foreign tax credit under Section 90, provided the credit was claimed in the return. The ruling clarifies that procedural delays in filing Form 67 should not override substantive entitlement to relief under Double Taxation Avoidance Agreements.

Real Income Doctrine | Refunded Royalties Under India-US DTAA Not Taxable as Notional Income : Bombay HC
Case Law Analysis
|Bombay High Court

Real Income Doctrine | Refunded Royalties Under India-US DTAA Not Taxable as Notional Income : Bombay HC

Bombay High Court holds that only the actual income retained after refunding excess royalties under an Advance Pricing Agreement is taxable under Article 12 of the India-US DTAA. The ruling rejects the Revenue’s attempt to tax notional amounts, reinforcing the real income principle in international taxation and providing relief to multinational enterprises facing transfer pricing adjustments.

Section 2(28A) IT Act | Broken Period Interest on NCDs Sold Before Maturity Taxable as Interest Income, Not Capital Gain: ITAT Delhi
Case Law Analysis
|Income Tax Appellate Tribunal

Section 2(28A) IT Act | Broken Period Interest on NCDs Sold Before Maturity Taxable as Interest Income, Not Capital Gain: ITAT Delhi

The ITAT Delhi has ruled that interest earned on non-convertible debentures during the broken period between purchase and sale-paid by the buyer, not the issuer-constitutes interest income under 'Income from Other Sources', not capital gains. This clarifies a critical tax treatment for institutional investors trading NCDs in secondary markets, preventing misclassification that could distort tax liability and compliance strategies.

Article 8 India-Germany DTAA | Income from Feeder Vessel Slot Arrangements Qualifies as Shipping Profits Exempt from Tax : ITAT Mumbai
Case Law Analysis
|Income Tax Appellate Tribunal

Article 8 India-Germany DTAA | Income from Feeder Vessel Slot Arrangements Qualifies as Shipping Profits Exempt from Tax : ITAT Mumbai

The ITAT Mumbai has ruled that income earned by non-resident shipping companies from cargo transported via feeder vessels under slot arrangements constitutes shipping profits under Article 8 of the India-Germany DTAA, exempting it from Indian taxation under Section 44B. This clarifies that ancillary logistics supporting international shipping are integral to the core shipping activity, benefiting global liner operators using feeder networks to access shallow Indian ports.

DTAA Article 12 | 'Make Available' Clause Mandatory for Royalty/FTS Classification of Telecom Services : ITAT Mumbai
Case Law Analysis
|Income Tax Appellate Tribunal

DTAA Article 12 | 'Make Available' Clause Mandatory for Royalty/FTS Classification of Telecom Services : ITAT Mumbai

ITAT Mumbai rules that payments for voice termination and bandwidth services do not qualify as royalty or fees for technical services under India-Singapore/US DTAA unless the 'make available' clause is satisfied. The ruling clarifies that business profits taxability hinges on the absence of a permanent establishment, shielding foreign telecom providers from double taxation.