Topic

Transfer Pricing

Transfer pricing in Indian tax law governs pricing of cross-border transactions between related entities to prevent profit shifting and ensure arm's length compliance under Sections 92 to 92F of the Income Tax Act.

42 articlesLatest September 2026
India-Mauritius DTAA Article 11 | Mauritius Entity with GBL Licence, FPI Registration & Control Over ECB Funds Held Beneficial Owner : ITAT Delhi
Case Law Analysis
|Income Tax Appellate Tribunal

India-Mauritius DTAA Article 11 | Mauritius Entity with GBL Licence, FPI Registration & Control Over ECB Funds Held Beneficial Owner : ITAT Delhi

ITAT Delhi rules a Mauritius entity holding a Category I GBL licence, FPI registration, and actual control over ECB funds satisfies the beneficial ownership test under Article 11 for interest income on ECBs lent to Indian group companies. The tribunal also denies the Section 194LD concessional withholding rate for non-convertible debentures.
NIL Arm's Length Price for Intra-Group Services Held Illegal | Transfer Pricing Adjustment : ITAT Delhi Bench
Case Law Analysis
|Income Tax Appellate Tribunal

NIL Arm's Length Price for Intra-Group Services Held Illegal | Transfer Pricing Adjustment : ITAT Delhi Bench

Delhi ITAT quashed a Rs 9.70 million transfer-pricing addition, holding that a zero arm’s-length price for intra-group management and support services breaches transfer-pricing rules. Taxpayers must demonstrate a tangible benefit to justify pricing. The ruling affects firms using NIL-price intra-group services under the Income Tax Act.

Export incentives and cash discounts must be treated as operating revenue for TNMM analysis | Transfer Pricing (Sec 92C) : ITAT
Case Law Analysis
|Income Tax Appellate Tribunal

Export incentives and cash discounts must be treated as operating revenue for TNMM analysis | Transfer Pricing (Sec 92C) : ITAT

The Delhi ITAT ruled that export incentives and cash discounts form part of a taxpayer’s operating revenue for the purpose of the Transactional Net Margin Method, requiring comparables to be selected on a fully adjusted basis. This clarifies the treatment of such items in transfer-pricing documentation and impacts exporters relying on TNMM benchmarks. Assessors must now ensure FAR-based comparables reflect these revenue components.

Inclusion of functional comparables & working-capital adjustment; exclusion of non-comparable firms under Rule 10B(2) | Transfer-Pricing Appeal : ITAT Delhi
Case Law Analysis
|Income Tax Appellate Tribunal

Inclusion of functional comparables & working-capital adjustment; exclusion of non-comparable firms under Rule 10B(2) | Transfer-Pricing Appeal : ITAT Delhi

The Delhi ITAT partially upheld WSP Consultants’ appeal, directing the assessing officer to incorporate functional comparables and adjust working-capital for AY 2021-22, while striking out firms lacking comparable functions. This refines peer-selection under Rule 10B(2) for similar transfer-pricing cases.

Section 144C(13) IT Act | Strict One-Month Limit for Final Assessment Order Mandatory: ITAT Delhi Quashes Time-Barred Order
Case Law Analysis
|Income Tax Appellate Tribunal

Section 144C(13) IT Act | Strict One-Month Limit for Final Assessment Order Mandatory: ITAT Delhi Quashes Time-Barred Order

ITAT Delhi ruled that the final assessment order under Section 144C(13) of the Income Tax Act must be passed within one month of receiving DRP directions, failing which it is barred by limitation. The decision reinforces procedural compliance in transfer pricing assessments, impacting taxpayers and revenue authorities alike.

Transfer Pricing | Arm's Length Pricing Precludes Further Profit Attribution to Permanent Establishment: ITAT Delhi
Case Law Analysis
|Income Tax Appellate Tribunal

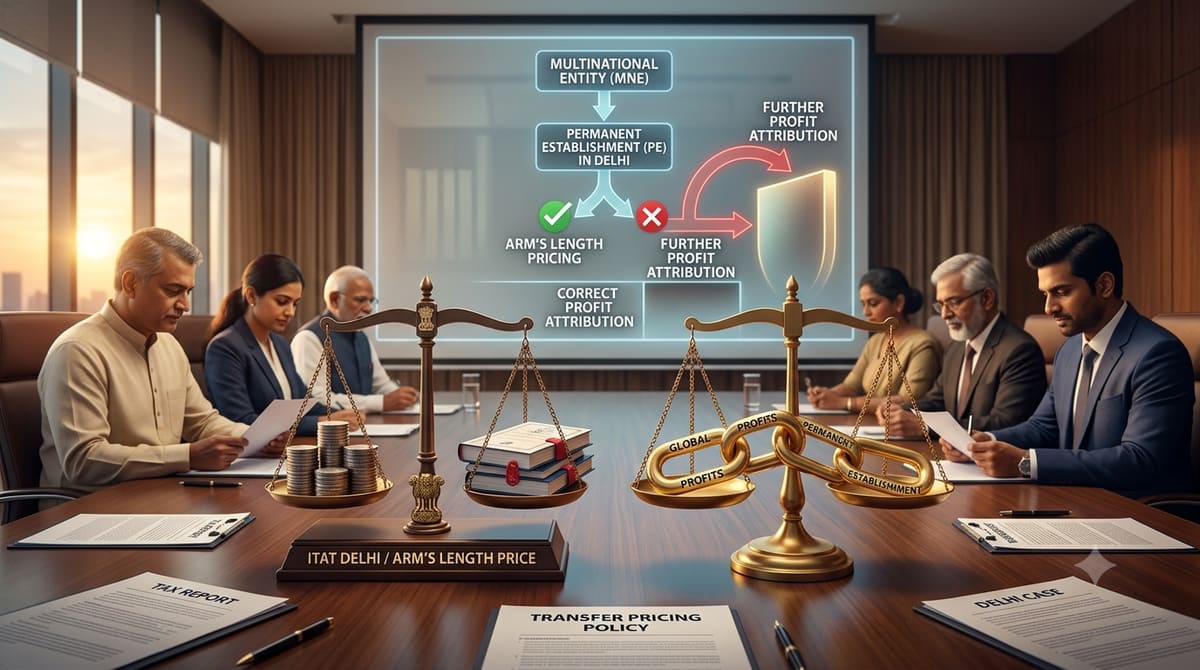
Transfer Pricing | Arm's Length Pricing Precludes Further Profit Attribution to Permanent Establishment: ITAT Delhi

The ITAT Delhi has ruled that once transfer pricing adjustments establish arm's length pricing for transactions with an associated enterprise, no additional profits can be attributed to a permanent establishment in India. This reinforces the principle that PE profit allocation must flow from the actual economic activity and pricing, not from speculative or artificial reallocations - a critical safeguard for multinational enterprises operating under DTAAs and the MLI.

Transfer Pricing | Foreign Exchange Gains Classified as Operating Income Under TNMM, Expense Allocation Tied to Gross Profit Margins: ITAT Delhi
Case Law Analysis
|Income Tax Appellate Tribunal

Transfer Pricing | Foreign Exchange Gains Classified as Operating Income Under TNMM, Expense Allocation Tied to Gross Profit Margins: ITAT Delhi

ITAT Delhi has ruled that foreign exchange gains arising from international transactions must be treated as operating income for transfer pricing purposes, and expense allocation must be calibrated using gross profit margins to determine the arm's length price. This sets a critical precedent for multinational enterprises using TNMM, forcing a reevaluation of how forex volatility and cost allocation impact their TP documentation and compliance strategy.

Resale Price Method (RPM) | Most Appropriate for Routine Distributors with No Value Addition: ITAT Delhi
Case Law Analysis
|Income Tax Appellate Tribunal

Resale Price Method (RPM) | Most Appropriate for Routine Distributors with No Value Addition: ITAT Delhi

ITAT Delhi has ruled that the Resale Price Method is the most appropriate transfer pricing method for distributors who merely resell imported goods without any value addition, affirming that gross profit margin analysis best reflects arm's length pricing in such cases. This sets a clear precedent for multinational distributors in India, reducing reliance on less suitable methods like TNMM when the distribution function is purely operational.

Real Income Doctrine | Refunded Royalties Under India-US DTAA Not Taxable as Notional Income : Bombay HC
Case Law Analysis
|Bombay High Court

Real Income Doctrine | Refunded Royalties Under India-US DTAA Not Taxable as Notional Income : Bombay HC

Bombay High Court holds that only the actual income retained after refunding excess royalties under an Advance Pricing Agreement is taxable under Article 12 of the India-US DTAA. The ruling rejects the Revenue’s attempt to tax notional amounts, reinforcing the real income principle in international taxation and providing relief to multinational enterprises facing transfer pricing adjustments.

TNMM Comparables Invalid if Related Party Transactions Exceed 25% of Sales: ITAT Delhi Sets Precedent on Arm's Length Price Selection
Case Law Analysis
|Income Tax Appellate Tribunal

TNMM Comparables Invalid if Related Party Transactions Exceed 25% of Sales: ITAT Delhi Sets Precedent on Arm's Length Price Selection

ITAT Delhi rules that comparables with related party transactions exceeding 25% of sales fail the arm's length price test under Section 92C, invalidating their selection. This precedent strengthens taxpayer challenges to Transfer Pricing Officer assessments, impacting multinational enterprises and transfer pricing litigation strategies.

Section 144C IT Act | Draft Assessment Order Must Exclude Demand Notice & Penalty Proceedings: ITAT Mumbai
Case Law Analysis
|Income Tax Appellate Tribunal

Section 144C IT Act | Draft Assessment Order Must Exclude Demand Notice & Penalty Proceedings: ITAT Mumbai

ITAT Mumbai rules that draft assessment orders under Section 144C of the IT Act cannot legally include demand notices or penalty initiation, setting a precedent for procedural compliance in transfer pricing assessments. The decision invalidates assessment orders that bundle these elements, impacting multinational corporations and tax authorities.

Section 144C(13) IT Act | AO Must Follow DRP Directions Even If TPO Has Not Acted : ITAT Bangalore
Case Law Analysis
|Income Tax Appellate Tribunal

Section 144C(13) IT Act | AO Must Follow DRP Directions Even If TPO Has Not Acted : ITAT Bangalore

The ITAT Bangalore has ruled that an Assessing Officer is legally bound to implement Dispute Resolution Panel directions under Section 144C(13) regardless of whether the Transfer Pricing Officer has finalized their order. This clarifies that statutory compliance with DRP mandates cannot be delayed or negated due to procedural lags in transfer pricing assessments, reinforcing taxpayer rights and administrative accountability in complex tax disputes.

Section 80G | CSR Donations Eligible for Tax Deduction If Recipient Is Registered Charity : ITAT Delhi
Case Law Analysis
|Income Tax Appellate Tribunal

Section 80G | CSR Donations Eligible for Tax Deduction If Recipient Is Registered Charity : ITAT Delhi

The ITAT Delhi has ruled that corporate social responsibility (CSR) expenditures under the Companies Act, 2013 qualify for income tax deduction under Section 80G, provided the recipient institution is duly registered under the Income Tax Act. This clarifies a long-standing ambiguity for businesses and aligns CSR compliance with tax incentives, impacting thousands of corporate donors nationwide.