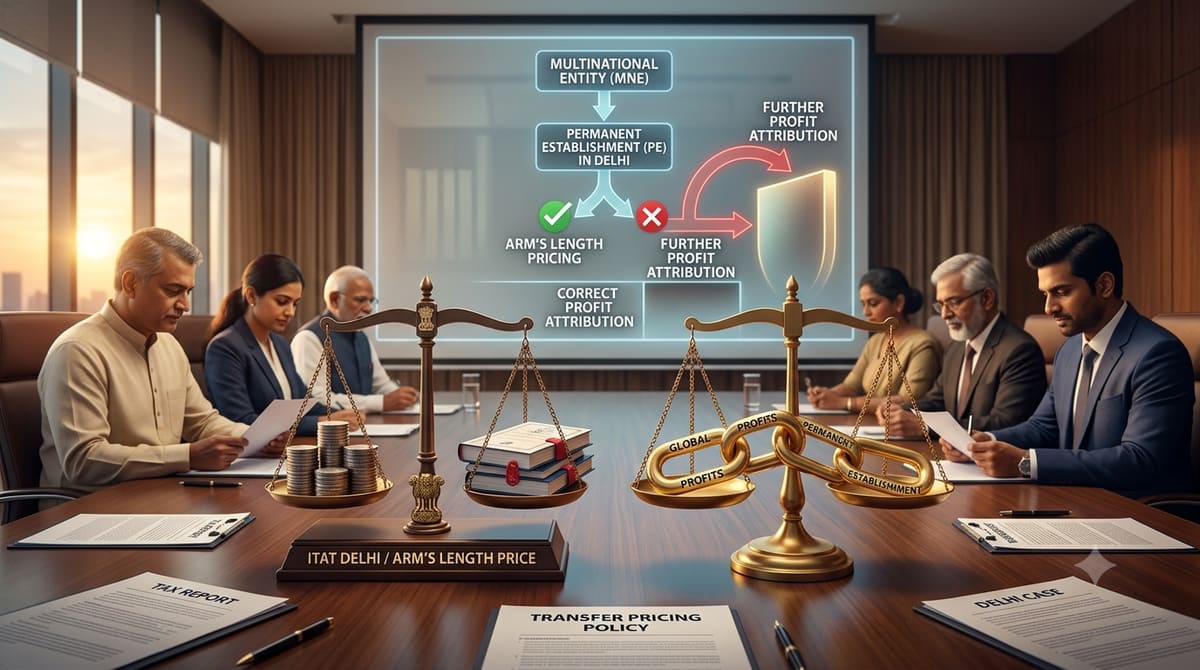
The Income Tax Appellate Tribunal, Delhi Bench 'I', has affirmed that a subsidiary acting as a limited risk service provider in international transactions is entitled to cost-plus remuneration, and that the Revenue cannot arbitrarily depart from a previously accepted transfer pricing methodology absent a material change in facts. This ruling reinforces the doctrinal importance of functional analysis, risk allocation, and consistency in transfer pricing assessments under the Income-tax Act, 1961.
Background & Facts
The Dispute
The appellant, Boeing India Defense Private Limited (BIDPL), is a wholly-owned subsidiary of Boeing Singapore Pte. Limited, which in turn is a subsidiary of The Boeing Company (TBC). BIDPL provides marketing, technical, management, and construction services to TBC and its subsidiaries on a cost-plus mark-up basis. During Assessment Year (AY) 2021-22, BIDPL entered into an international transaction involving receipt of technical and training services from its Associated Enterprise (AE), Boeing Aerospace Operations (BAO), for which it paid INR 39,67,01,914. The Transfer Pricing Officer (TPO) disallowed INR 38,20,29,442 of this amount, recharacterizing BIDPL as a full-risk service provider and rejecting its functional analysis and benchmarking methodology.
Key Facts
BIDPL was incorporated on 08.09.2014.
BIDPL entered into contracts with the Indian Air Force (IAF) for C-17 aircrew training (INR 37.5 crores) and BBJ technical support (INR 2.2 crores), both arising from aircraft sales by BAO to IAF.
BIDPL does not own the aircraft, simulators, technical know-how, or intellectual property related to the services.
BAO owns all critical intangibles, including proprietary training manuals, technical bulletins, and simulator technology.
BAO subcontracted the actual delivery of C-17 training to Mahindra Defense Systems (MDS), which operates the simulator on its own leased premises with its own instructors.
BIDPL employs only one site manager for C-17 and three Field Service Representatives (FSRs) for BBJ, solely for coordination and liaison between IAF and BAO.
BIDPL’s remuneration is strictly cost-plus: 20% markup on value-added expenses (VAE), excluding costs of services outsourced to BAO.
The intercompany agreement with BAO explicitly states that all liabilities, including liquidated damages and performance guarantees, rest with BAO.
BIDPL cannot disclose its contracts with IAF due to confidentiality clauses under the Ministry of Defence (MoD) and national security restrictions.
In AY 2020-21, the TPO accepted BIDPL’s functional characterization and benchmarking using TNMM with OP/OC as the Profit Level Indicator (PLI), resulting in an arm’s length price (ALP) of 20.48%.
No material change occurred in AY 2021-22 in functions, risks, assets, or contractual structure.
Procedural History
31.10.2023: TPO issued Transfer Pricing Order disallowing INR 38,20,29,442 as non-arm’s length.
18.01.2024: BIDPL filed objections before the Dispute Resolution Panel (DRP).
24.10.2024: DRP directed TPO to reconsider BIDPL’s characterization, not penalize it for non-submission of classified defense contracts, and re-evaluate comparables.
29.10.2024: TPO issued final assessment order, incorporating the same adjustment despite DRP directions.
11.02.2026: Hearing before ITAT Delhi.
06.05.2026: ITAT delivered order allowing the appeal.
The Parties' Positions
For the Appellant (BIDPL)
BIDPL is a limited risk service provider with no control over pricing, technology, or risk exposure.
All risks, including performance, warranty, and customer claims, are borne by BAO.
The TNMM with OP/OC as PLI was correctly applied and accepted in AY 2020-21.
The TPO’s use of royalty/license agreements as comparables is fundamentally flawed, as BIDPL does not license intangibles but coordinates services.
The DRP’s directions were ignored by the TPO.
The principle of consistency, as affirmed in Bharat Sanchar Nigam Ltd. v. UOI and CIT v. Excel Industries Ltd., mandates acceptance of the prior year’s position absent a material change.
Confidentiality obligations under MoD prevent disclosure of defense contracts; DRP had already directed that this not be held against the assessee.
For the Respondent (Revenue)
BIDPL’s role is substantial and it should be treated as the principal service provider.
The payment of INR 39.67 crores to BAO is disproportionate to the services rendered by BIDPL.
The revenue sharing mechanism shows BIDPL retains only 27.8% of total contractual revenue, suggesting it is not a low-risk entity.
The absence of back-to-back contracts with IAF raises doubts about risk allocation.
The TPO’s benchmarking using RoyaltyStat comparables was reasonable.
DRP directions were followed, and the TPO’s recharacterization was justified.
Relief Sought
BIDPL sought:
Deletion of the transfer pricing adjustment of INR 38,20,29,442.
Acceptance of its TNMM-based benchmarking with OP/OC of 20.48%.
Rejection of the TPO’s use of non-comparable royalty agreements.
Direction to the TPO to comply with DRP’s directions.
Cancellation of interest and penalty proceedings under Sections 234A, 234B, 234C and 270A, contingent on the above.
The Legal Issue
The central question was whether a subsidiary acting as a limited risk service provider, with no ownership of intangibles, no assumption of business risks, and a cost-plus remuneration model, can be recharacterized as a full-risk entity solely due to the absence of back-to-back contracts, and whether the Revenue can depart from a previously accepted transfer pricing methodology in the absence of any material change in facts.
Arguments Presented
For the Appellant
The appellant relied on the functional, asset, and risk (FAR) analysis under OECD Transfer Pricing Guidelines and CBDT Circular 6/2013 to establish its limited risk status. It emphasized that its role was purely coordinative, with no control over pricing, technology, or customer relationships. The intercompany agreement with BAO explicitly allocated all liabilities to BAO. The appellant cited Sumitomo Corporation India v. CIT and Li & Fung India v. CIT to support the use of the Berry Ratio (OP/VAE) as a valid PLI for low-risk service providers. It further invoked Bharat Sanchar Nigam Ltd. v. UOI and CIT v. Excel Industries Ltd. to argue that the Revenue cannot reverse a previously accepted position without justification. The appellant submitted that the TPO’s comparables were functionally and economically non-comparable, as they involved licensing of intangibles, whereas BIDPL’s transaction involved service coordination.
For the Respondent
The Revenue contended that BIDPL’s direct contractual relationship with IAF and its receipt of service revenue indicated it was the principal service provider. It argued that the 72.2% share of revenue paid to BAO was excessive and suggested BIDPL was retaining minimal margin, thus implying higher risk exposure. The TPO’s reliance on RoyaltyStat agreements was defended as a legitimate search for comparable transactions. The Revenue also argued that the DRP’s directions were merely advisory and did not bind the TPO to accept the appellant’s methodology.
The Court's Analysis
The Tribunal conducted a detailed review of the contractual arrangements, financial statements, and functional profiles of both BIDPL and BAO. It noted that BIDPL owned no simulators, no technical know-how, no proprietary software, and employed only minimal staff for liaison. The actual training was delivered by MDS, hired and paid by BAO. The Tribunal emphasized that the intercompany agreement explicitly assigned all performance risks to BAO, a fact not disputed by the Revenue.
"The assessee invested neither in the simulator or any technology to carry out the required services to the IAF. It completely depended on the execution of various services by the BAO."
The Tribunal held that the TPO’s recharacterization of BIDPL as a full-risk service provider was unsupported by evidence. The use of royalty/license agreements as comparables was rejected as inappropriate, since BIDPL did not license any intangible property; it merely facilitated service delivery. The Tribunal observed that the TPO had failed to follow the DRP’s specific directions to reconsider the functional characterization and not penalize the assessee for non-disclosure of classified contracts.
The Tribunal placed decisive weight on the principle of consistency. It noted that the same transaction, with identical facts, functions, risks, and assets, had been accepted in AY 2020-21. The Revenue had not demonstrated any change in circumstances to justify a different outcome. Citing Bharat Sanchar Nigam Ltd. and Excel Industries, the Tribunal held that the Revenue cannot flip-flop on a settled position without compelling reasons.
"Following the principles of consistency, we direct the AO/TPO to accept the benchmarking conducted by the assessee."
The Tribunal further clarified that confidentiality obligations under national security laws cannot be used to infer risk assumption. The DRP had already directed that this be disregarded, and the TPO’s failure to comply was a procedural lapse.
The Verdict
The appeal was allowed. The ITAT set aside the transfer pricing adjustment of INR 38,20,29,442 and directed the TPO to accept the appellant’s benchmarking analysis under TNMM with an OP/OC ratio of 20.48%. The Tribunal ordered the TPO to compute the arm’s length price based on the appellant’s methodology and to delete the addition. The interest and penalty proceedings under Sections 234A, 234B, 234C and 270A were held to be contingent upon the above and were accordingly dropped. The Tribunal directed compliance within 30 days of the order.
What This Means For Similar Cases
Consistency in Transfer Pricing Is Legally Binding
Practitioners must argue that once a transfer pricing methodology is accepted in a prior year with identical facts, the Revenue cannot unilaterally change it in subsequent years without demonstrating a material change in facts or law.
The burden shifts to the Revenue to justify deviation; mere disagreement is insufficient.
Cases like Excel Industries and Bharat Sanchar Nigam now form a strong doctrinal shield against arbitrary reassessments.
Limited Risk Service Providers Are Entitled to Cost-Plus Remuneration
Entities performing only coordination, liaison, or administrative functions without assuming market, technical, or performance risks qualify as limited risk service providers.
The Berry Ratio (OP/VAE) and OP/OC are valid PLIs for such entities, especially where value addition is minimal.
Ownership of intangibles and assumption of liabilities are decisive factors; direct contracting with the end customer does not, by itself, imply risk assumption.
Non-Disclosure of Classified Contracts Cannot Be Used Against Assessees
In defense, aerospace, and sensitive technology sectors, confidentiality obligations under national security laws are legally binding.
Tax authorities cannot infer risk exposure or non-compliance from non-disclosure of such contracts if the taxpayer has submitted all available non-classified documentation.
DRP directions to disregard non-disclosure must be followed by TPOs; failure to do so renders the assessment invalid.
Benchmarking Must Reflect Economic Reality
Comparables must be functionally and economically similar. Royalty/license agreements are irrelevant for service-based transactions.
The nature of the controlled transaction - whether licensing, service provision, or manufacturing - must dictate the choice of comparables.
TPOs must conduct a detailed functional analysis before selecting comparables; generic database searches are insufficient.
The DRP’s Directions Are Mandatory
DRP directions under Section 144C(5) are binding on the TPO.
Failure to comply with DRP directions renders the final assessment order legally defective.
Appeals must specifically challenge non-compliance with DRP directions as a ground of appeal.