Topic

Permanent Establishment

9 articlesLatest July 2026
Section 28(i) IT Act | PE Maintenance Expenses Not Automatically Disallowed After Business Transfer: ITAT Delhi
Case Law Analysis
|Income Tax Appellate Tribunal

Section 28(i) IT Act | PE Maintenance Expenses Not Automatically Disallowed After Business Transfer: ITAT Delhi

The ITAT Delhi ruled that expenses incurred to sustain a Permanent Establishment after a business transfer cannot be disallowed under Section 28(i) merely due to the transfer-each cost must be evaluated for its direct nexus to ongoing business operations. This clarifies a critical loophole for multinational firms restructuring Indian operations, ensuring tax treatment aligns with economic substance rather than corporate form.
Section 9(1)(v)(c) IT Act | Interest from Nostro Accounts Not Taxable Under Mutuality Principle : ITAT Mumbai
Case Law Analysis
|Income Tax Appellate Tribunal

Section 9(1)(v)(c) IT Act | Interest from Nostro Accounts Not Taxable Under Mutuality Principle : ITAT Mumbai

ITAT Mumbai rules that interest earned by Indian branches of foreign banks from their head office or overseas branches is not taxable under Section 9(1)(v)(c) of the Income Tax Act, as it constitutes payment to self rather than income. The decision reinforces the mutuality principle, shielding such transactions from domestic tax liability for foreign banks operating in India.

Article 8 India-China DTAA | Inland Haulage Charges Integral to International Shipping Profits Are Tax-Exempt : ITAT Mumbai
|Income Tax Appellate Tribunal

Article 8 India-China DTAA | Inland Haulage Charges Integral to International Shipping Profits Are Tax-Exempt : ITAT Mumbai

The ITAT Mumbai has ruled that Inland Haulage Charges received by non-resident shipping companies are exempt under Article 8 of the India-China DTAA because they are inseparable from the operation of ships in international traffic. This clarifies that ancillary land-based logistics supporting global shipping routes qualify for treaty protection, significantly benefiting foreign container lines operating in India.

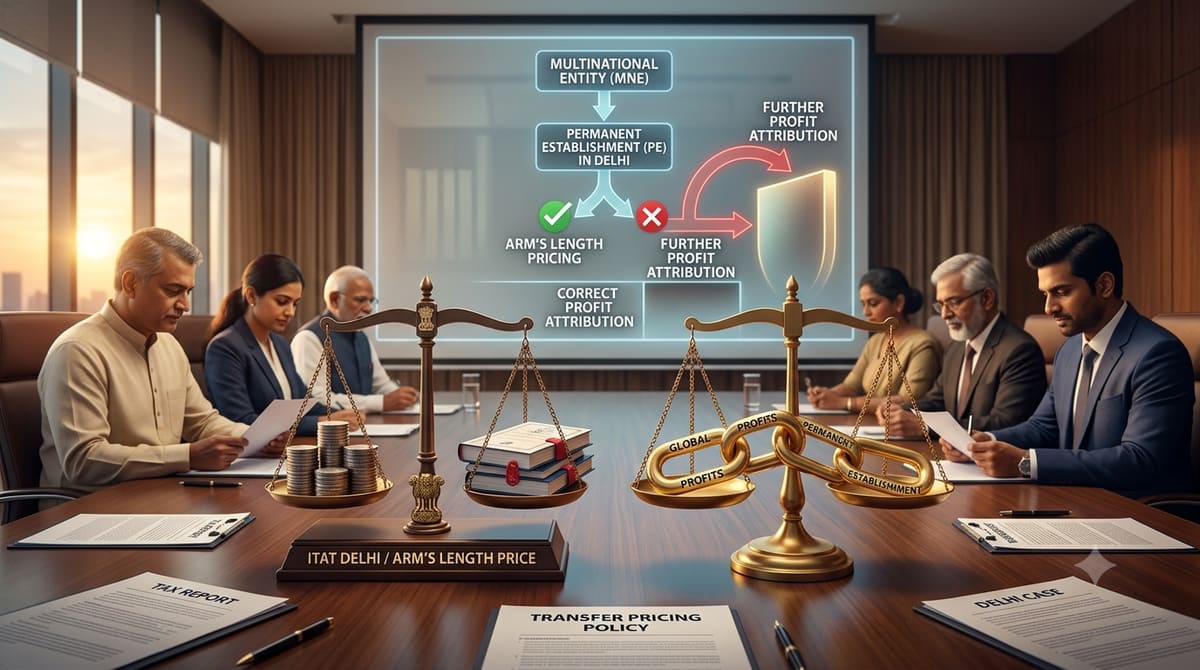
Transfer Pricing | Arm's Length Pricing Precludes Further Profit Attribution to Permanent Establishment: ITAT Delhi
Case Law Analysis
|Income Tax Appellate Tribunal

Transfer Pricing | Arm's Length Pricing Precludes Further Profit Attribution to Permanent Establishment: ITAT Delhi

The ITAT Delhi has ruled that once transfer pricing adjustments establish arm's length pricing for transactions with an associated enterprise, no additional profits can be attributed to a permanent establishment in India. This reinforces the principle that PE profit allocation must flow from the actual economic activity and pricing, not from speculative or artificial reallocations - a critical safeguard for multinational enterprises operating under DTAAs and the MLI.

Real Income Doctrine | Refunded Royalties Under India-US DTAA Not Taxable as Notional Income : Bombay HC
Case Law Analysis
|Bombay High Court

Real Income Doctrine | Refunded Royalties Under India-US DTAA Not Taxable as Notional Income : Bombay HC

Bombay High Court holds that only the actual income retained after refunding excess royalties under an Advance Pricing Agreement is taxable under Article 12 of the India-US DTAA. The ruling rejects the Revenue’s attempt to tax notional amounts, reinforcing the real income principle in international taxation and providing relief to multinational enterprises facing transfer pricing adjustments.

Fixed Place PE Not Established by Temporary Access for Installation | India-Canada DTAA: ITAT Delhi
Case Law Analysis
|Income Tax Appellate Tribunal

Fixed Place PE Not Established by Temporary Access for Installation | India-Canada DTAA: ITAT Delhi

ITAT Delhi ruled that temporary access to client premises solely for installing theatre systems does not create a fixed place permanent establishment under the India-Canada DTAA, even if activities span over 120 days. This clarifies that physical presence alone, without control or disposal rights over the space, is insufficient to trigger taxation in India - a critical guidance for foreign tech and service providers operating in India under tax treaties.

Section 44BB IT Act | No Presumptive Tax on Offshore Supply Without Permanent Establishment Under India-UK Tax Treaty : ITAT Delhi
Case Law Analysis
|Income Tax Appellate Tribunal

Section 44BB IT Act | No Presumptive Tax on Offshore Supply Without Permanent Establishment Under India-UK Tax Treaty : ITAT Delhi

The ITAT Delhi ruled that offshore supply of goods by a UK-based company, with no physical presence or control in India, cannot be taxed under Section 44BB’s presumptive regime. The Revenue failed to prove a permanent establishment under the India-UK Tax Treaty, reinforcing that mere contract execution or remote supervision does not create taxable nexus. This sets a critical precedent for multinational energy and engineering firms operating across borders without local infrastructure.

DTAA Article 5 | Remote Maintenance Services Do Not Create Fixed Place PE Without Physical Presence or 90-Day Threshold: ITAT Delhi
|Income Tax Appellate Tribunal

DTAA Article 5 | Remote Maintenance Services Do Not Create Fixed Place PE Without Physical Presence or 90-Day Threshold: ITAT Delhi

The ITAT Delhi has ruled that remote technical support for IMAX theatre systems, even when performed over 90 days, does not constitute a Fixed Place Permanent Establishment under the India-Canada DTAA unless there is a physical location at the disposal of the enterprise. This clarifies a critical gap in tax treaty interpretation for global tech and maintenance providers, shielding foreign enterprises from unintended tax liabilities in India solely due to digital access.

DTAA Article 12 | 'Make Available' Clause Mandatory for Royalty/FTS Classification of Telecom Services : ITAT Mumbai
Case Law Analysis
|Income Tax Appellate Tribunal

DTAA Article 12 | 'Make Available' Clause Mandatory for Royalty/FTS Classification of Telecom Services : ITAT Mumbai

ITAT Mumbai rules that payments for voice termination and bandwidth services do not qualify as royalty or fees for technical services under India-Singapore/US DTAA unless the 'make available' clause is satisfied. The ruling clarifies that business profits taxability hinges on the absence of a permanent establishment, shielding foreign telecom providers from double taxation.