Topic

Exemption Notification

Exemption notifications under Indian tax laws specify conditions under which goods or services are exempt from duties like GST, central excise, or service tax, often tied to specific usage, classification, or supply chains.

13 articlesLatest July 2026
Service Tax Exemption for Non-AC Restaurants with Common Kitchen | CESTAT Clarifies Demarcation Requirement Under Finance Act 1994 : CESTAT Chennai
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

Service Tax Exemption for Non-AC Restaurants with Common Kitchen | CESTAT Clarifies Demarcation Requirement Under Finance Act 1994 : CESTAT Chennai

CESTAT Chennai rules that non-air-conditioned restaurant services sourced from a common kitchen are exempt from service tax if clearly demarcated from AC sections. The ruling underscores strict compliance with Notification No. 03/2013-ST, impacting restaurant operators with mixed seating arrangements.

Service Tax Exemption for Railway Projects | Notification 25/2012 Covers Both Public and Private Use: CESTAT Chandigarh
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

Service Tax Exemption for Railway Projects | Notification 25/2012 Covers Both Public and Private Use: CESTAT Chandigarh

CESTAT Chandigarh has ruled that services related to railway infrastructure qualify for exemption under Notification 25/2012 regardless of whether the project serves public or private interests, clarifying that the exemption is not contingent on ownership or end-use. This decision shields project consultants and agents from service tax liability in railway development, offering critical relief to private contractors and public-sector partners alike.

Notification 12/2012-CE Sr. No. 203 | Hot Rolling of SS Flats into Pattas/Pattis Qualifies for Nil Duty, Even Without Further Processing: CESTAT Ahmedabad
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

Notification 12/2012-CE Sr. No. 203 | Hot Rolling of SS Flats into Pattas/Pattis Qualifies for Nil Duty, Even Without Further Processing: CESTAT Ahmedabad

CESTAT Ahmedabad clarifies that hot-rolled stainless steel pattas/pattis are eligible for nil excise duty under Sr. No. 203 of Notification 12/2012-CE, even when no process beyond hot rolling is applied. This resolves long-standing ambiguity for manufacturers, affirming that cold rolling is the only excluded step - not mere slitting or shaping - significantly impacting SS flat product manufacturers across Gujarat and beyond.

Customs Exemption Notification No. 65/88-Cus. | Hospital Duty Waiver Voided for Failing Free Treatment Obligations : CESTAT Hyderabad
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

Customs Exemption Notification No. 65/88-Cus. | Hospital Duty Waiver Voided for Failing Free Treatment Obligations : CESTAT Hyderabad

CESTAT Hyderabad denied customs duty exemption to Durgabai Deshmukh Hospital for failing to fulfill mandatory conditions: providing free treatment to 40% of outpatients and reserving 10% of beds for low-income patients. The ruling reinforces that exemption benefits are strictly conditional, and non-compliance triggers retrospective duty demand and confiscation - a critical warning for charitable hospitals relying on duty waivers.

Customs Exemption | Procedural Non-Compliance Does Not Void Benefit If Substantive Purpose Is Met : CESTAT
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

Customs Exemption | Procedural Non-Compliance Does Not Void Benefit If Substantive Purpose Is Met : CESTAT

CESTAT rules that failure to meet a procedural condition under a customs exemption notification does not automatically trigger duty demand, provided the underlying objective of the condition has been achieved. This shields compliant importers from punitive demands when technical lapses don't undermine the exemption's intent, reinforcing proportionality in customs enforcement.

Section 11B Customs and Excise Refund | No Tax Liability Nullifies Limitation Period for Deposits Made Under Protest : CESTAT Chandigarh
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

Section 11B Customs and Excise Refund | No Tax Liability Nullifies Limitation Period for Deposits Made Under Protest : CESTAT Chandigarh

When tax authorities drop a demand entirely, deposits made under protest must be refunded without being barred by the one-year limitation under Section 11B. This ruling protects businesses from being penalized for complying with investigative demands while preserving their legal rights, setting a critical precedent for service tax and customs taxpayers across India.

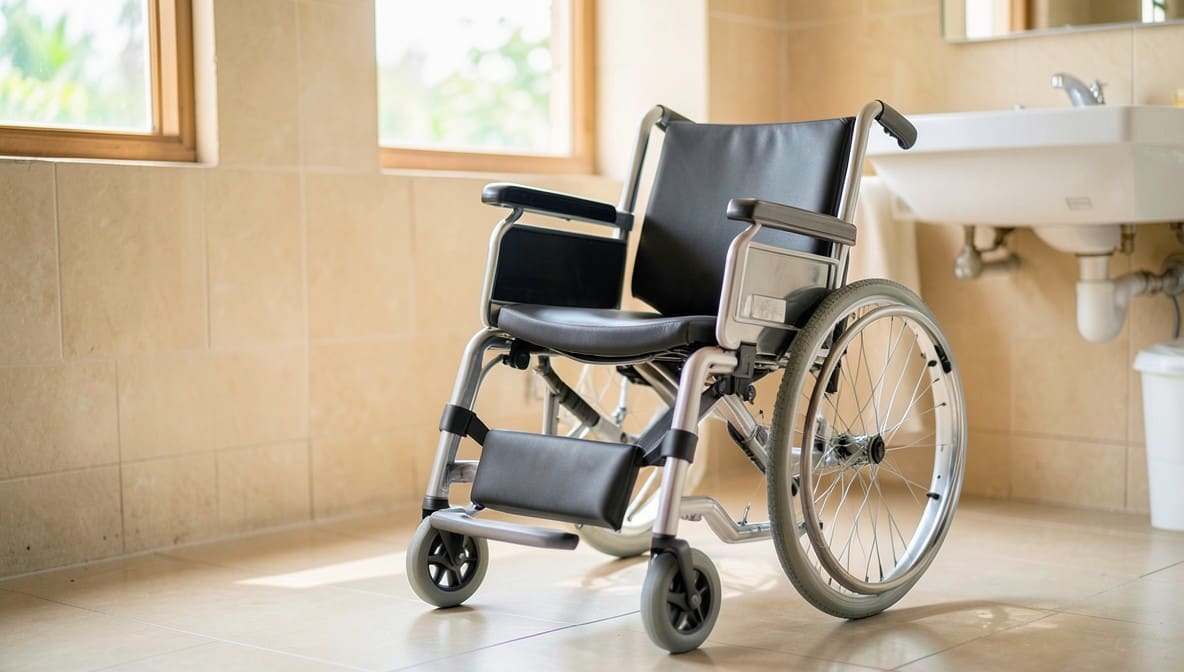
Essential Character Doctrine | Wheelchairs with Integrated Toileting Facilities Remain Classifiable Under HSN 8713 for Exemption: CESTAT Chennai
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

Essential Character Doctrine | Wheelchairs with Integrated Toileting Facilities Remain Classifiable Under HSN 8713 for Exemption: CESTAT Chennai

CESTAT Chennai rules that adding toileting functionality to a wheelchair does not reclassify it as a commode chair under HSN 9402, as long as mobility remains its essential purpose. This clarifies that assistive devices combining multiple health functions retain exemption eligibility under Notification 12/2012-Cus. if their primary design serves mobility for persons with disabilities.

SAD Exemption Under Notification 45/2005 | Stock Transfer from FTWZ to DTA Eligible Despite VAT Payable : CESTAT Mumbai
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

SAD Exemption Under Notification 45/2005 | Stock Transfer from FTWZ to DTA Eligible Despite VAT Payable : CESTAT Mumbai

CESTAT Mumbai rules that Special Additional Duty (SAD) exemption under Notification 45/2005 applies to stock transfers from Free Trade Warehousing Zones (FTWZ) to Domestic Tariff Areas (DTA) even if VAT is payable on final sale. The tribunal also bars invocation of the extended limitation period without legal basis, reinforcing compliance clarity for importers and manufacturers.

Notification 41/2017 GST | Direct Supply to Registered Recipient Mandatory for Concessional Rate; Third-Party Delivery Invalidates Exemption : Karnataka HC
Case Law Analysis
|Karnataka High Court

Notification 41/2017 GST | Direct Supply to Registered Recipient Mandatory for Concessional Rate; Third-Party Delivery Invalidates Exemption : Karnataka HC

The Karnataka High Court ruled that GST exemption under Notification 41/2017 is contingent on direct supply to the registered recipient or their registered warehouse. Delivery to third parties-even at the recipient’s instruction-disqualifies the supplier from the concessional rate, underscoring the strict compliance required for tax exemptions under GST law.