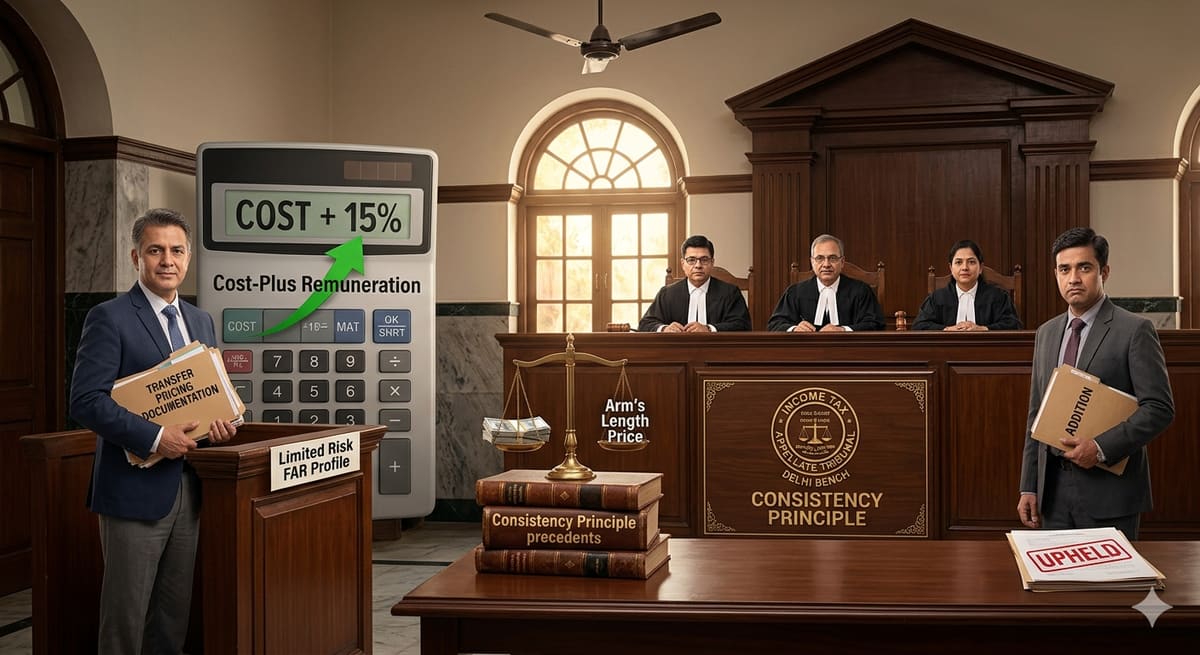
The Income Tax Appellate Tribunal's ruling in Idemitsu Lube India Private Limited v. DCIT establishes a critical precedent on the consistent application of comparables in transfer pricing adjustments. The Tribunal emphasized that arbitrary exclusion of entities previously accepted by the Revenue undermines the integrity of the arm's length principle and violates the doctrine of consistency in tax administration.
Background & Facts
The Dispute
The appellant, Idemitsu Lube India Private Limited, manufactures automotive lubricants and engages in international transactions for the purchase of raw materials. The dispute centered on a transfer pricing adjustment of ₹12.44 crore made by the Transfer Pricing Officer (TPO) under Section 92CA(3) of the Income Tax Act, 1961. The TPO rejected two companies proposed by the appellant - Iftex Oil and Chemicals Ltd. and Universal Petro-Chemicals Ltd. - as comparables for determining the arm's length price using the Transaction Net Margin Method (TNMM). The Dispute Resolution Panel (DRP) upheld this exclusion, citing cherry-picking and failure to meet turnover and profitability filters.
Procedural History
- Assessment Year 2021-22: TPO issued order rejecting two proposed comparables and made adjustment of ₹12,44,40,596.
- DRP Proceedings: Appellant filed additional grounds seeking inclusion of the two companies; DRP rejected them on grounds of low margins, negative profitability, and lack of disclosure of search process.
- Appeal to ITAT: Appellant challenged DRP’s order, relying on prior years’ assessments where the same companies were accepted by the TPO.
Relief Sought
The appellant sought deletion of the transfer pricing adjustment by including Iftex Oil and Chemicals Ltd. and Universal Petro-Chemicals Ltd. in the final list of comparables, arguing that their functional comparability had been previously acknowledged by the Revenue.
The Legal Issue
The central question was whether the Revenue can exclude comparables previously accepted in prior assessment years without demonstrating a change in functional or economic conditions, and whether such exclusion constitutes arbitrary application of Section 92C and Section 92CA.
Arguments Presented
For the Appellant
The appellant relied on the principle of consistency in tax administration and cited orders from Assessment Years 2018-19 and 2020-21, where the same two companies were included by the TPO as comparables. It argued that the Revenue had not disputed their functional comparability in those years, and their inclusion in the current year would bring the appellant’s margin of 5.23% within the 35th - 65th percentile range (4.86% - 9.83%), thereby negating the adjustment. The appellant emphasized that the DRP’s new turnover filter (1/10th of turnover) was applied retrospectively and inconsistently.
For the Respondent
The Revenue contended that the two companies were excluded due to persistent losses (Iftex) and disproportionately low turnover compared to the appellant. It argued that the appellant had not disclosed the search methodology for these companies and that their inclusion would distort the median margin. The DRP maintained that cherry-picking of low-margin entities to reduce the arm’s length price was impermissible under Section 92C(2).
The Court's Analysis
The Tribunal examined the doctrine of consistency in tax administration and the statutory framework under Section 92C and Section 92CA, which require comparables to be functionally comparable and selected using objective criteria. The Court noted that the Revenue had, in two prior years, accepted both companies as functionally comparable without objection. The Tribunal held that the absence of any material change in the business operations or market conditions between the years rendered the DRP’s exclusion arbitrary.
"The Revenue has not disputed the functional comparability of those companies with Assessee's manufacturing segment for those years under consideration."
The Court rejected the DRP’s newly introduced turnover filter as retrospective and inconsistent with prior practice. It further observed that the appellant’s margin of 5.23% fell within the adjusted range when the two companies were included, thereby satisfying the TNMM threshold. The Tribunal emphasized that the burden of justifying exclusion lies with the Revenue, especially when the same entities were previously accepted. The Tribunal also dismissed the argument of persistent losses, noting that Section 92C does not mandate profitability as a standalone criterion - functional similarity and economic substance prevail.
The Verdict
The appellant won. The Tribunal held that consistent acceptance of comparables across assessment years establishes functional comparability, and arbitrary exclusion without change in circumstances violates the principle of consistency under Section 92C. The Tribunal directed the Assessing Officer to include both companies in the final list of comparables for the assessment year 2021-22, thereby setting aside the transfer pricing adjustment.
What This Means For Similar Cases
Prior Acceptance Creates Binding Precedent
- Practitioners must cite prior years’ TPO orders where the same comparables were accepted to challenge arbitrary exclusions.
- Revenue authorities cannot introduce new filters retroactively without justification tied to material changes in business or market conditions.
Functional Comparability Trumps Turnover or Profitability Filters
- Turnover disparity alone cannot disqualify a comparable if functional similarity is established.
- Persistent losses do not automatically disqualify a company under Section 92C; the focus must remain on operational functions and economic substance.
Documentation of Search Process Is Critical
-
Taxpayers must maintain and disclose the methodology used to identify comparables in their TP study reports.
-
Failure to document search criteria invites allegations of cherry-picking, even if comparables were previously accepted.
-
Always cross-reference prior years’ TPO orders when challenging comparables exclusion.
-
Argue that consistency in administrative practice is a facet of natural justice under Article 14 of the Constitution.
-
Where margin falls within the interquartile range after inclusion of previously accepted comparables, the adjustment must be reversed.