Topic

TNMM

The Transactional Net Margin Method (TNMM) is a transfer pricing methodology under Indian income tax law used to determine arm's length prices for international transactions by comparing net profit margins of related parties with independent enterprises.

6 articlesLatest August 2026
Export incentives and cash discounts must be treated as operating revenue for TNMM analysis | Transfer Pricing (Sec 92C) : ITAT
Case Law Analysis
|Income Tax Appellate Tribunal

Export incentives and cash discounts must be treated as operating revenue for TNMM analysis | Transfer Pricing (Sec 92C) : ITAT

The Delhi ITAT ruled that export incentives and cash discounts form part of a taxpayer’s operating revenue for the purpose of the Transactional Net Margin Method, requiring comparables to be selected on a fully adjusted basis. This clarifies the treatment of such items in transfer-pricing documentation and impacts exporters relying on TNMM benchmarks. Assessors must now ensure FAR-based comparables reflect these revenue components.
TNMM Comparables Invalid if Related Party Transactions Exceed 25% of Sales: ITAT Delhi Sets Precedent on Arm's Length Price Selection
Case Law Analysis
|Income Tax Appellate Tribunal

TNMM Comparables Invalid if Related Party Transactions Exceed 25% of Sales: ITAT Delhi Sets Precedent on Arm's Length Price Selection

ITAT Delhi rules that comparables with related party transactions exceeding 25% of sales fail the arm's length price test under Section 92C, invalidating their selection. This precedent strengthens taxpayer challenges to Transfer Pricing Officer assessments, impacting multinational enterprises and transfer pricing litigation strategies.

TNMM Prevails Over Internal CPM for Identical Functional Profiles | ITAT Ahmedabad Deletes ₹3.88 Crore TP Adjustment Under Consistency Principle
Case Law Analysis
|Income Tax Appellate Tribunal

TNMM Prevails Over Internal CPM for Identical Functional Profiles | ITAT Ahmedabad Deletes ₹3.88 Crore TP Adjustment Under Consistency Principle

ITAT Ahmedabad ruled that the Transactional Net Margin Method (TNMM) remains the most appropriate transfer pricing method where functional profiles remain unchanged, deleting a ₹3.88 crore adjustment. The decision reinforces judicial precedent, binding tax authorities to prior rulings for identical facts, offering relief to multinational enterprises facing repetitive TP disputes.

Working Capital Adjustment Under TNMM Precludes Separate Notional Interest on Receivables : ITAT Ahmedabad
Case Law Analysis
|Income Tax Appellate Tribunal

Working Capital Adjustment Under TNMM Precludes Separate Notional Interest on Receivables : ITAT Ahmedabad

ITAT Ahmedabad rules that once working capital adjustment is granted under the Transactional Net Margin Method (TNMM), imputing additional notional interest on delayed receivables constitutes double adjustment and is legally unsustainable. The decision reinforces that receivables are integral to primary transactions and cannot be re-characterized as loan financing for tax purposes.

Transfer Pricing | ITAT Delhi Upholds Cost-Plus Remuneration for Limited Risk Service Providers Under Consistency Principle : ITAT Delhi
Case Law Analysis
|Income Tax Appellate Tribunal

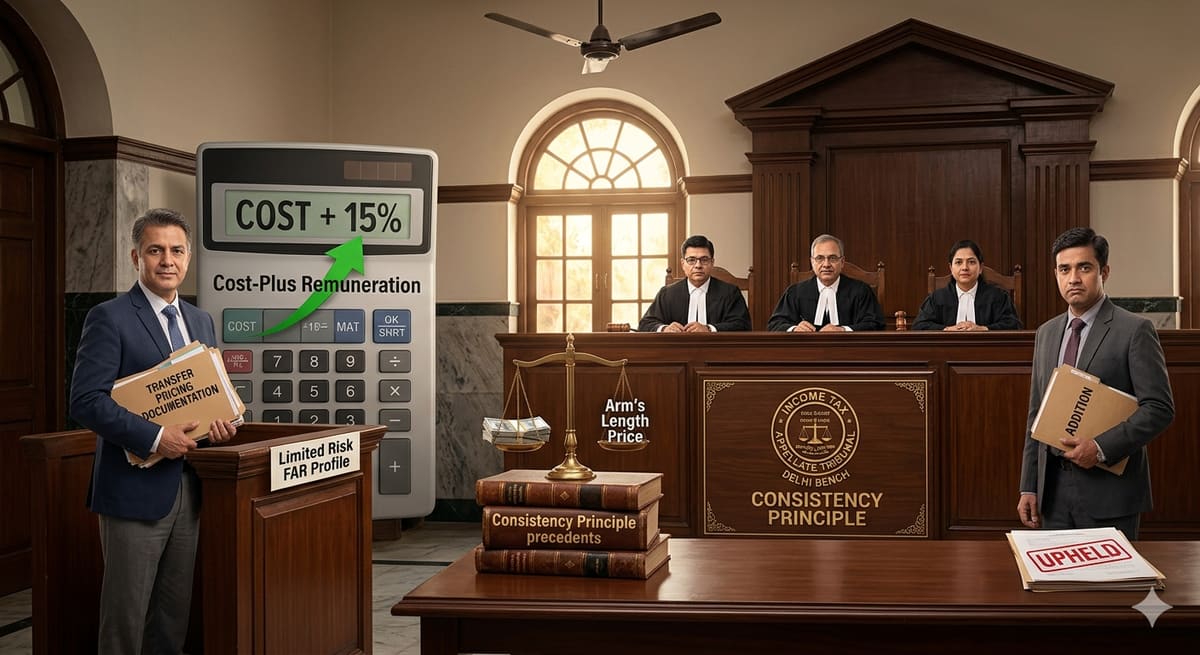
Transfer Pricing | ITAT Delhi Upholds Cost-Plus Remuneration for Limited Risk Service Providers Under Consistency Principle : ITAT Delhi

ITAT Delhi ruled that a limited risk service provider is entitled to cost-plus remuneration, rejecting transfer pricing adjustments where benchmarking was inconsistent and DRP directions were ignored. The decision reinforces the consistency principle in transfer pricing, impacting multinational enterprises and tax compliance strategies.

Transfer Pricing | RPT Filter Must Be Applied Uniformly; Working Capital Adjustments Require Scientific Analysis Under TNMM : ITAT Bangalore
Case Law Analysis
|Income Tax Appellate Tribunal

Transfer Pricing | RPT Filter Must Be Applied Uniformly; Working Capital Adjustments Require Scientific Analysis Under TNMM : ITAT Bangalore

ITAT Bangalore rules that the Related Party Transaction (RPT) filter must be applied uniformly across comparables in transfer pricing analyses. The Tribunal also mandates that working capital adjustments under the Transactional Net Margin Method (TNMM) must be based on average balance analysis, while interest on foreign currency receivables should be calculated using LIBOR+200 bps. The ruling sets a precedent for scientific rigor in benchmarking international transactions.