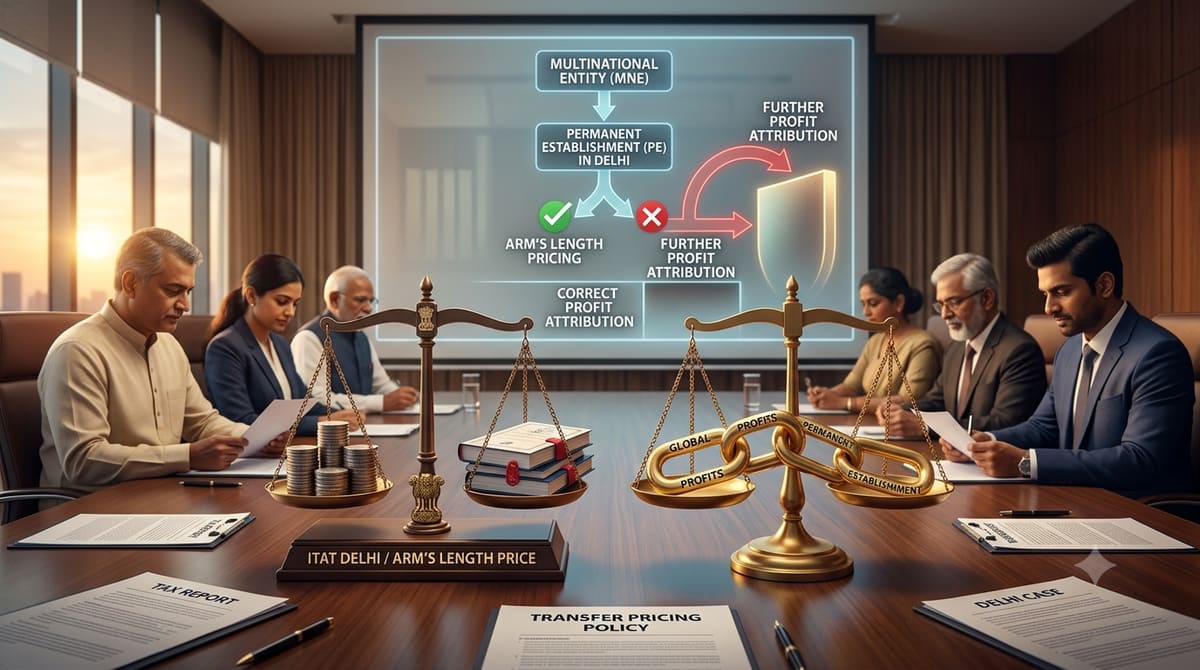
The Income Tax Appellate Tribunal (ITAT), Delhi, has reaffirmed the Resale Price Method (RPM) as the Most Appropriate Method (MAM) for benchmarking international transactions involving routine distributors who do not add value to imported goods. This ruling clarifies that incurrence of high distribution or marketing expenses does not justify rejection of RPM in favor of the Transactional Net Margin Method (TNMM), provided the assessee performs no substantial value addition. The decision underscores the primacy of RPM for pure trading transactions under Rule 10B(1)(b) of the Income-tax Act, 1961, and aligns with precedents from the Delhi and Bombay High Courts.
Background & Facts
The Dispute
The appellant, Beam Global Spirits and Wine (India) Pvt. Ltd., a subsidiary of Beam Group, is engaged in the production and sale of alcoholic beverages in India. For the Assessment Year (AY) 2011-12, the assessee filed its return of income on 30.11.2011, declaring a total income of Rs. 54,02,95,256. The dispute pertains to the transfer pricing adjustment of Rs. 4,08,80,300 proposed by the Transfer Pricing Officer (TPO) in respect of the international transaction of import of finished goods (Bottle-in-origin or BIO products) from its Associated Enterprises (AEs).
Key Facts
- The assessee operates under three segments: manufacturing, distribution, and provision of services. The dispute is confined to the distribution segment, which accounts for 3.56% of the total turnover.
- The assessee imports BIO products from Beam Group entities under a distributorship agreement and resells them in India to licensed vendors and duty-free shops.
- The assessee also provides need-based marketing support services to promote the sales of these products.
- The assessee benchmarked the international transaction using RPM, with gross profit by sales as the Profit Level Indicator (PLI). The tested party's margin was 49.73%, while the comparables' margin was 15.91%, leading the assessee to conclude that the transaction was at Arm's Length Price (ALP).
Procedural History
- 17.04.2015: The Assessing Officer (AO) passed an assessment order u/s 143(3) r.w.s. 144C of the Act, incorporating the TPO's adjustment.
- 21.02.2023: The Commissioner of Income Tax (Appeals)-44, New Delhi [CIT(A)] upheld the TPO's adjustment, rejecting RPM and substituting it with TNMM. The CIT(A) observed that the assessee had incurred selling and distribution expenses, indicating active engagement in brand promotion and development of local intangibles.
- 01.04.2026: The matter was heard by the ITAT Delhi.
- The assessee contended that RPM was accepted by the TPO in AYs 2012-13 and 2013-14 under identical facts and circumstances.
Relief Sought
The assessee challenged the transfer pricing adjustment of Rs. 4,08,80,300 and sought restoration of RPM as the MAM for benchmarking the international transaction.
The Legal Issue
The central question was whether RPM remains the Most Appropriate Method (MAM) for benchmarking international transactions involving routine distributors who import goods from AEs and resell them without value addition, even if the assessee incurs substantial distribution or marketing expenses.
Arguments Presented
For the Appellant
- RPM is the appropriate method for routine distributors who do not add value to imported goods, as held in Burberry India Pvt. Ltd. Vs. ACIT (ITA Nos. 758 & 7684/Del/2017) and affirmed by the Delhi High Court in PCIT vs. Burberry India Pvt. Ltd. (ITA No. 471/2019).
- The assessee merely imports and resells BIO products without any physical alteration or value addition, making RPM the most suitable method under Rule 10B(1)(b).
- Distribution expenses (including marketing and advertising) are debited below the gross profit line in the profit and loss account and thus do not affect the gross profit margin under RPM.
- The coordinate bench of ITAT Delhi in Burberry India Pvt. Ltd. held that high AMP expenses do not justify rejection of RPM in favor of TNMM.
For the Respondent
- The assessee is not a mere routine distributor but engages in brand promotion and development of local intangibles, justifying the use of TNMM over RPM.
- The assessee incurred distribution expenses of Rs. 8.02 crores against a turnover of Rs. 9.30 crores, indicating substantial value addition that warrants compensation from the AE.
- Reliance was placed on the Bangalore ITAT decision in Abott Medical Optics Private Limited Vs. DCIT (71 taxmann.com 338), where RPM was rejected due to high selling and distribution expenses.
The Court's Analysis
The ITAT Delhi conducted a detailed examination of the legal principles governing transfer pricing methods, particularly RPM and TNMM, and their applicability to routine distributors:
- RPM as the Most Appropriate Method for Routine Distributors
"A close scrutiny of the above two sub-clauses along with the remaining sub-clauses of rule 10B(1)(b) makes it clear beyond doubt that RPM is best suited for determining ALP of an international transaction in the nature of purchase of goods from an AE which are resold as such to unrelated parties. Ordinarily, this method pre-supposes no or insignificant value addition to the goods purchased from foreign AE."
The Tribunal relied on the Delhi High Court decision in Principal Commissioner of Income-tax-6 v. Matrix Cellular International Services (P.) Ltd. ([2018] 90 taxmann.com 54), which held that RPM is the appropriate method for pure traders who do not add value to the product before resale. The Court observed:
"Once the ITAT... had concluded that the business of the assessee was merely that of a pure trader, and there was no value addition made before re-selling the particular products... its consequent finding that RPM is the Most Appropriate Method, is irreproachable."
- Irrelevance of Distribution Expenses Under RPM
The Tribunal rejected the revenue's argument that high distribution expenses justify the rejection of RPM. It held:
"The incurrence of distribution expenses per se, be it high or low, has got no relevance at all for comparing the gross profit margin of the assessee vis-a-vis the comparable when RPM is adopted as the MAM. When we consider gross profit in numerator and net sales in denominator, all the expenses debited to the Profit & loss account automatically stand excluded."
The Tribunal cited Nokia India (P) Ltd. v. Dy. CIT ([2014] 52 taxmann.com 492), which clarified that advertising and marketing expenses (debited below the gross profit line) do not affect the ALP determination under RPM. If such expenses contribute to brand building for the AE, a separate adjustment for Advertising, Marketing, and Promotion (AMP) expenses may be warranted, but this was not done in the present case.
- Precedents Supporting RPM
The Tribunal relied on multiple judicial precedents to support its conclusion:
- Swarovski India Pvt. Ltd. v. ACIT (ITA No. 5621/Del/2014): Held that RPM is the most appropriate method for determining ALP where the assessee purchases goods from AE and sells them without value addition.
- Mattel Toys v. Deputy Commissioner of Income Tax ([2013] 158 TTJ 461): Affirmed that RPM is applicable where the reseller does not physically alter the goods or use intangible assets to add value.
- CIT v. L'Oreal India Pvt. Ltd. (ITA No. 1046/2012): Bombay High Court held that RPM is appropriate for distribution activities where goods are purchased from AEs and sold to unrelated parties without further processing.
- Bausch & Lomb Eyecare (India) Pvt. Ltd. v. Additional Commissioner of Income Tax ([2016] 381 ITR 227): Noted that RPM loses accuracy where the reseller adds substantial value to the product.
- Rejection of Revenue's Reliance on Bangalore ITAT Decision
The Tribunal distinguished the Bangalore ITAT decision in Abott Medical Optics Private Limited Vs. DCIT, where RPM was rejected due to high selling and distribution expenses. It held that the Delhi Tribunal's decision in Burberry India Pvt. Ltd. (affirmed by the Delhi High Court) squarely applies to the present case, rendering the Bangalore decision inapplicable.
The Verdict
The ITAT Delhi allowed the assessee's appeal in part by:
- Setting aside the transfer pricing adjustment of Rs. 4,08,80,300 proposed by the TPO and upheld by the CIT(A).
- Restoring RPM as the Most Appropriate Method (MAM) for benchmarking the international transaction of import of finished goods.
- Dismissing Ground No. 3.2 (challenging initiation of penalty proceedings u/s 271G and 271(1)(c)) as premature.
- Holding Ground No. 3.1 (challenging levy of interest u/s 234B and 234D) as consequential.
What This Means For Similar Cases
RPM Remains the Default Method for Routine Distributors
- Pure trading transactions (import and resale without value addition) must be benchmarked using RPM under Rule 10B(1)(b). TNMM is not a substitute merely because the assessee incurs distribution or marketing expenses.
- Gross profit margin (not net profit) is the relevant PLI under RPM. Expenses debited below the gross profit line (e.g., marketing, advertising) do not affect ALP determination under RPM.
High AMP Expenses Do Not Justify Rejection of RPM
- Advertising, Marketing, and Promotion (AMP) expenses incurred by the assessee do not automatically warrant rejection of RPM. If such expenses contribute to brand building for the AE, a separate adjustment may be required, but this must be explicitly proposed by the TPO.
- Burden of proof lies on the revenue to demonstrate value addition or development of local intangibles to justify deviation from RPM.
Precedential Value of Delhi High Court Rulings
- Delhi High Court decisions in Burberry India Pvt. Ltd. and Luxottica India Pvt. Ltd. bind lower authorities, including the TPO and CIT(A), in matters involving routine distributors.
- Coordinate bench decisions (e.g., Burberry India Pvt. Ltd.) carry significant persuasive value and should be preferred over conflicting rulings from other jurisdictions (e.g., Bangalore ITAT).
Practical Takeaways for Taxpayers
- Document FAR Analysis: Ensure Functions performed, Assets employed, and Risks assumed (FAR) are clearly documented to establish the assessee's role as a routine distributor.
- Benchmarking Strategy: If the assessee is a pure trader, RPM should be the default method. Deviations to TNMM must be justified by tangible value addition.
- Separate AMP Adjustment: If AMP expenses are incurred for brand building of the AE, consider separate benchmarking to avoid disputes.
- Consistency Across AYs: Ensure uniform application of transfer pricing methods across assessment years to avoid adjustments based on inconsistent treatment.