Topic

taxable service

Taxable service under Indian law refers to specific services listed under the Finance Act, 1994, subject to service tax before its replacement by GST in 2017, with interpretations shaped by CESTAT rulings and exemptions.

10 articlesLatest July 2026
Section 65(105)(zzzm) Finance Act | Municipal Corporations Exempt from Service Tax on Advertisement Space Sales Pre-2012: CESTAT Chandigarh
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

Section 65(105)(zzzm) Finance Act | Municipal Corporations Exempt from Service Tax on Advertisement Space Sales Pre-2012: CESTAT Chandigarh

CESTAT Chandigarh ruled that municipal corporations do not qualify as 'persons' under Section 65(105)(zzzm) of the Finance Act, 1994, for the period before 01.07.2012, exempting them from service tax on advertisement space sales. The decision sets a precedent for statutory interpretation of taxable entities, impacting revenue disputes involving constitutional bodies.
Service Tax | Ocean Freight Markup Not Taxable as 'Business Support Service' Under Finance Act, 1994 : CESTAT Chandigarh
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

Service Tax | Ocean Freight Markup Not Taxable as 'Business Support Service' Under Finance Act, 1994 : CESTAT Chandigarh

CESTAT Chandigarh holds that when a freight forwarder purchases ocean freight on a principal-to-principal basis and resells it with a markup, the transaction does not constitute a taxable 'Business Support Service' under the Finance Act, 1994. This clarifies the scope of taxable auxiliary services in logistics and benefits freight forwarders operating as principals, not agents, in international shipping arrangements.

Revenue Sharing with Food Outlets Not Business Support Service Under Service Tax : CESTAT Chennai
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

Revenue Sharing with Food Outlets Not Business Support Service Under Service Tax : CESTAT Chennai

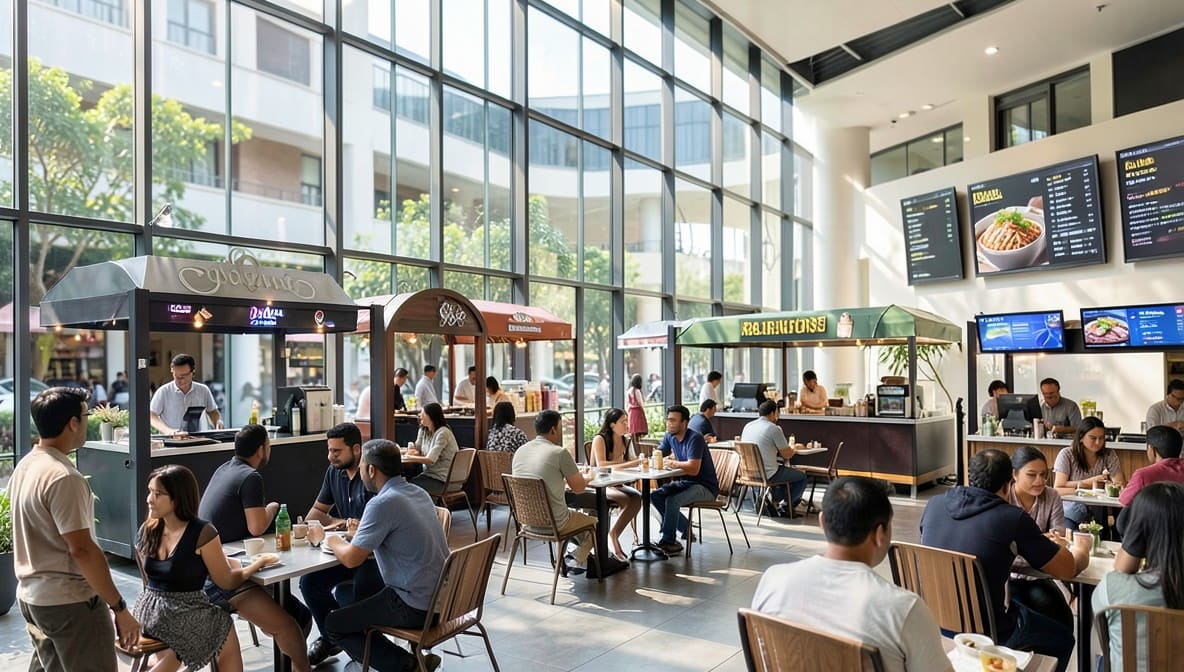
CESTAT Chennai rules that revenue-sharing payments from licensees operating food and beverage outlets within a property do not constitute taxable Business Support Services under the Finance Act, 1994. This clarifies a critical boundary for mall operators and entertainment complexes, shielding them from service tax demands on ancillary commercial partnerships that lack direct operational control or support functions.

Service Tax Valuation | Wall Rent Includible in Advertising Service Value; Flex Costs Excluded If Separately Invoiced as Goods : CESTAT Chandigarh
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

Service Tax Valuation | Wall Rent Includible in Advertising Service Value; Flex Costs Excluded If Separately Invoiced as Goods : CESTAT Chandigarh

CESTAT Chandigarh ruled that advertising agencies must include wall rent payments in the taxable value of their services, as it is an essential cost directly tied to service delivery. However, printed flex costs are excluded if billed separately as goods and taxed accordingly, clarifying the boundary between service and supply in advertising contracts.

Service Tax Not Applicable on Placement Fees Collected from Students Under 'Manpower Recruitment' Definition : CESTAT Mumbai
|Custom, Excise & Service Tax Tribunal

Service Tax Not Applicable on Placement Fees Collected from Students Under 'Manpower Recruitment' Definition : CESTAT Mumbai

CESTAT Mumbai rules that placement fees charged by educational institutions to students-not employers-do not constitute 'manpower recruitment or supply agency service' under Section 65(105)(k) of the Finance Act, 1994. The decision clarifies that service tax liability arises only when institutions act as intermediaries for employers, shielding academic bodies from retrospective tax demands.

Corporate Guarantee Without Consideration Not Taxable as 'Banking Service' Under Service Tax | Reverse Charge Mechanism Inapplicable : CESTAT Chandigarh
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

Corporate Guarantee Without Consideration Not Taxable as 'Banking Service' Under Service Tax | Reverse Charge Mechanism Inapplicable : CESTAT Chandigarh

CESTAT Chandigarh rules that a corporate guarantee issued by an overseas parent company without monetary consideration does not constitute a 'taxable service' under service tax law. The tribunal quashed a ₹11.6 crore demand, holding that the reverse charge mechanism cannot apply where no service fee or benefit is exchanged, setting a precedent for cross-border financial arrangements.

Service Tax Exemption for Residential Construction of Fewer Than 12 Units | CESTAT Kolkata Invalidates Demand Based on Bank-ST-3 Comparison Alone
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

Service Tax Exemption for Residential Construction of Fewer Than 12 Units | CESTAT Kolkata Invalidates Demand Based on Bank-ST-3 Comparison Alone

CESTAT Kolkata rules that residential construction projects with fewer than 12 units are exempt from service tax under the Finance Act, 1994. The tribunal quashed the demand, holding that reliance solely on ST-3 form and bank statement comparisons without substantive evidence lacks legal basis, setting a precedent for audit compliance challenges.

Section 65(82) Finance Act | Supply of Water to Vessels Constitutes Taxable 'Port Service' Pre-July 2010 : CESTAT Ahmedabad
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

Section 65(82) Finance Act | Supply of Water to Vessels Constitutes Taxable 'Port Service' Pre-July 2010 : CESTAT Ahmedabad

CESTAT Ahmedabad rules that supplying water to vessels within port premises qualifies as a 'port service' under Section 65(82) of the Finance Act, 1994, making it liable for service tax even if characterized as a sale of goods. The ruling clarifies that reimbursement charges for such services attract tax obligations, impacting port operators and shipping entities.