Topic

Customs Tariff

Customs Tariff in India governs the classification of goods under the Harmonized System of Nomenclature (HSN) for duty assessment and exemption eligibility, as interpreted by customs authorities and the CESTAT.

7 articlesLatest August 2026
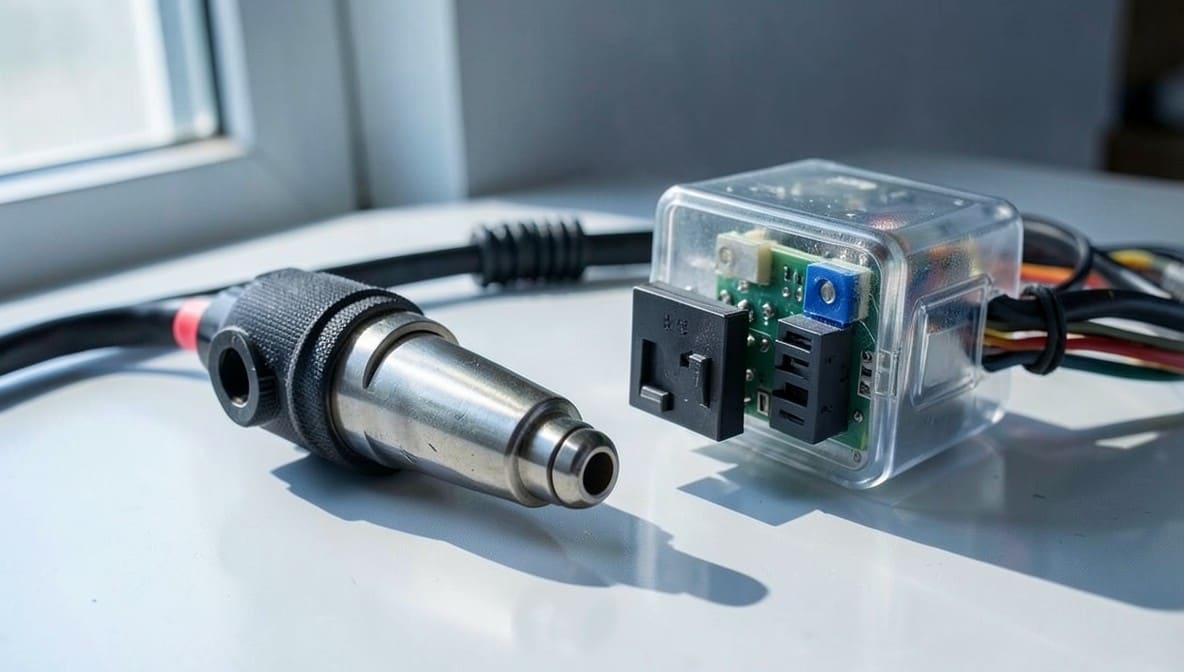
Glow Plug Control Unit falls under CTH 8511 as part of ignition equipment | Customs tariff classification : CESTAT (New Delhi)
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

Glow Plug Control Unit falls under CTH 8511 as part of ignition equipment | Customs tariff classification : CESTAT (New Delhi)

CESTAT ruled that the imported glow-plug control unit is a component of the glow plug and must be classified under heading 8511 9000 of the Customs Tariff, not under 9032 8990. The order upholds the normal-period demand and sets aside the Section 114A penalty. Importers of automotive ignition parts will now attract the 7.5% basic customs duty and IGST.
Customs Classification | Inconclusive IS Standard Lab Reports Cannot Justify Confiscation; Benefit of Doubt Favors Importer : CESTAT Ahmedabad
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

Customs Classification | Inconclusive IS Standard Lab Reports Cannot Justify Confiscation; Benefit of Doubt Favors Importer : CESTAT Ahmedabad

CESTAT Ahmedabad rules that test reports failing to verify mandatory parameters under IS 14314:1995 and IS 1745:2018 are legally inadequate for confiscation. Importers are entitled to benefit of doubt when labs omit critical data like aromatic hydrocarbon content, reinforcing strict compliance with Indian Standards for accurate tariff classification.

HSN 3302 | Odoriferous Substances Need Not Be Predominant for Classification: CESTAT Mumbai
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

HSN 3302 | Odoriferous Substances Need Not Be Predominant for Classification: CESTAT Mumbai

CESTAT Mumbai clarifies that goods containing trace amounts of odoriferous ingredients like paprika, garlic oil, or spearmint qualify under HSN 3302 even when not the primary component, overturning a restrictive interpretation by customs authorities. This ruling impacts snack food manufacturers, flavoring suppliers, and importers by providing clarity on tariff classification for complex blended seasonings.

Essential Character Doctrine | Wheelchairs with Integrated Toileting Facilities Remain Classifiable Under HSN 8713 for Exemption: CESTAT Chennai
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

Essential Character Doctrine | Wheelchairs with Integrated Toileting Facilities Remain Classifiable Under HSN 8713 for Exemption: CESTAT Chennai

CESTAT Chennai rules that adding toileting functionality to a wheelchair does not reclassify it as a commode chair under HSN 9402, as long as mobility remains its essential purpose. This clarifies that assistive devices combining multiple health functions retain exemption eligibility under Notification 12/2012-Cus. if their primary design serves mobility for persons with disabilities.