Topic

General Rules of Interpretation

3 articlesLatest May 2026
CTH 7323 vs 9403 | Stainless Steel Kitchen Baskets & Racks Classified as Household Articles, Not Furniture Parts : CESTAT New Delhi
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

CTH 7323 vs 9403 | Stainless Steel Kitchen Baskets & Racks Classified as Household Articles, Not Furniture Parts : CESTAT New Delhi

CESTAT New Delhi has ruled that stainless steel kitchen baskets, racks, and holders are household articles under CTH 7323, not furniture parts under CTH 9403, reversing a customs duty demand. This clarifies a critical boundary in tariff classification for importers of modular kitchen accessories, reducing compliance uncertainty and potential duty exposure for similar goods.
General Rules of Interpretation | Curved Molybdenum Mirrors/Shields Classifiable as 'Other Articles' Under CTH 81029900, Not Flat Sheets : CESTAT
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

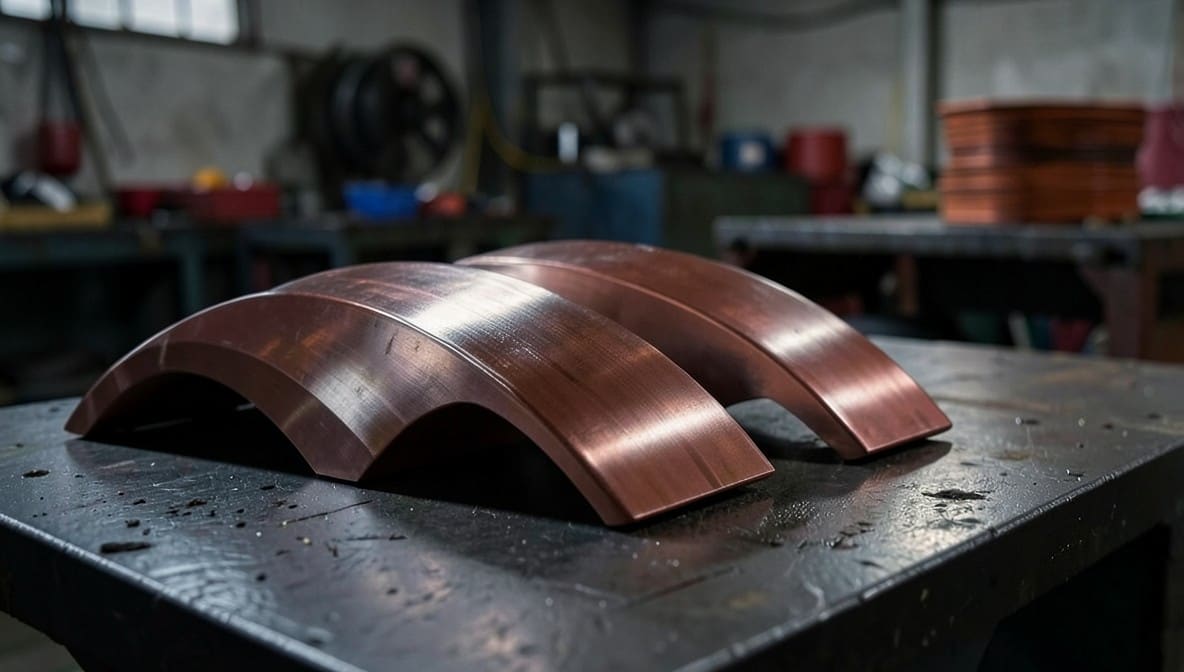
General Rules of Interpretation | Curved Molybdenum Mirrors/Shields Classifiable as 'Other Articles' Under CTH 81029900, Not Flat Sheets : CESTAT

CESTAT rules that curved molybdenum mirrors/shields, despite being made from sheets, acquire a distinct functional identity and must be classified under CTH 81029900 at 10% BCD, not as flat sheets under CTH 810295. The decision underscores the application of the General Rules of Interpretation in customs law, impacting importers and tax authorities in tariff disputes.

HSN 7113 | Gold Chains in Running Length Classified as Jewellery, Not Semi-Manufactured Gold: CESTAT Bangalore
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

HSN 7113 | Gold Chains in Running Length Classified as Jewellery, Not Semi-Manufactured Gold: CESTAT Bangalore

CESTAT Bangalore rules that gold chains in running length, requiring only cutting and hook attachment, qualify as 'articles of jewellery' under HSN 7113, rejecting classification as semi-manufactured gold. The decision clarifies tariff classification for importers and customs authorities, impacting duty exemptions and valuation under the Customs Act 1962.