Topic

Precedent

4 articlesLatest 3 weeks ago
HSST Upgradation Retrospective Effect | Benefit Must Commence from Academic Year Start, Not Government Order Date: Kerala HC
Case Law Analysis
|Kerala High Court

HSST Upgradation Retrospective Effect | Benefit Must Commence from Academic Year Start, Not Government Order Date: Kerala HC

The Kerala High Court has ruled that the upgradation of Junior Higher Secondary School Teachers to Higher Secondary School Teachers must be given retrospective effect from the beginning of the academic year, not from the date of the government order. This ensures equitable pay and seniority for teachers, aligning with established precedent and protecting their legitimate expectations under service law.

Review Jurisdiction | Error Apparent on Face of Record Justifies Recall of Order Ignoring Binding Precedent : MP HC Jabalpur
Case Law Analysis
|Madhya Pradesh High Court

Review Jurisdiction | Error Apparent on Face of Record Justifies Recall of Order Ignoring Binding Precedent : MP HC Jabalpur

Madhya Pradesh High Court rules that review jurisdiction under Order 47 Rule 1 CPC can be invoked if a coordinate bench's order overlooks binding precedent, creating an 'error apparent on the face of the record'. The decision clarifies that such errors warrant recall of erroneous orders, ensuring judicial discipline and consistency in service law matters.

Service Tax Exemption | Tobacco Threshing & Redrying on Job Work is Agricultural Processing, Not Taxable BAS : CESTAT Hyderabad
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

Service Tax Exemption | Tobacco Threshing & Redrying on Job Work is Agricultural Processing, Not Taxable BAS : CESTAT Hyderabad

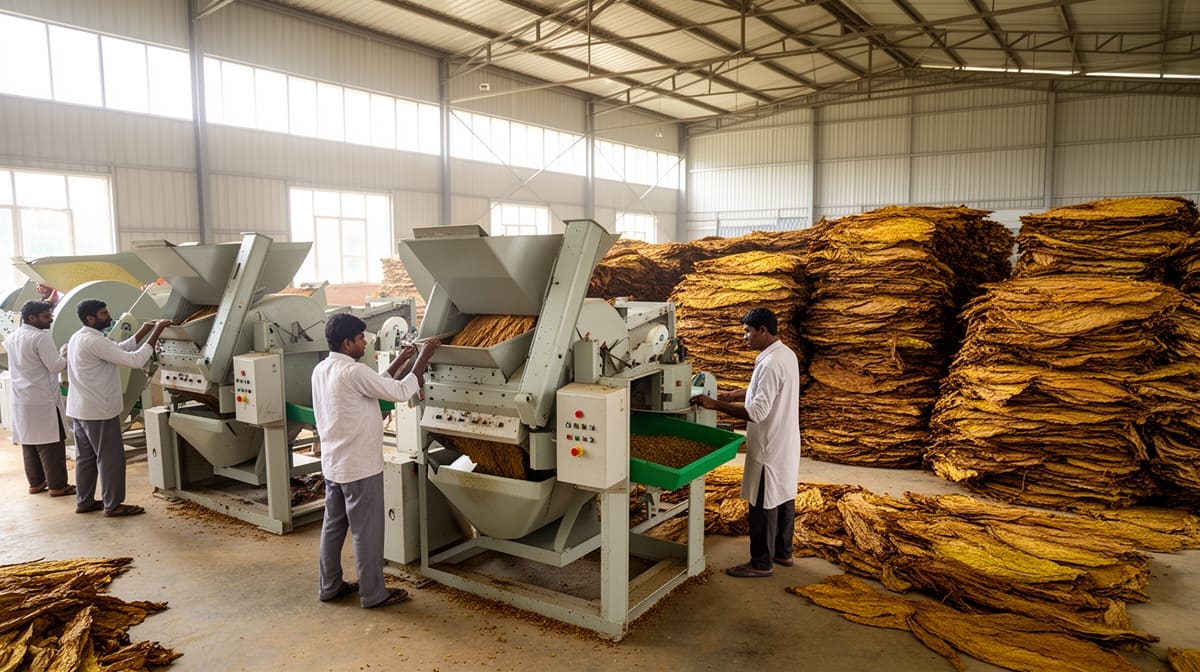
CESTAT Hyderabad rules that threshing and redrying of tobacco leaves on a job work basis qualifies as processing of agricultural produce, exempting it from service tax under Notification 14/2004-ST. The decision clarifies that such activities do not fall under 'Business Auxiliary Services', providing relief to tobacco processors and traders from retrospective tax demands.