The Chennai Customs, Excise & Service Tax Appellate Tribunal has clarified a critical distinction in service tax jurisprudence: whether an arrangement constitutes 'manpower supply' or 'job work' hinges not on the nature of the activity alone, but on the precise terms of the contract and the allocation of control, risk, and remuneration. This decision provides much-needed doctrinal clarity for manufacturers and labour contractors operating in regulated industries.
Background & Facts
The Dispute
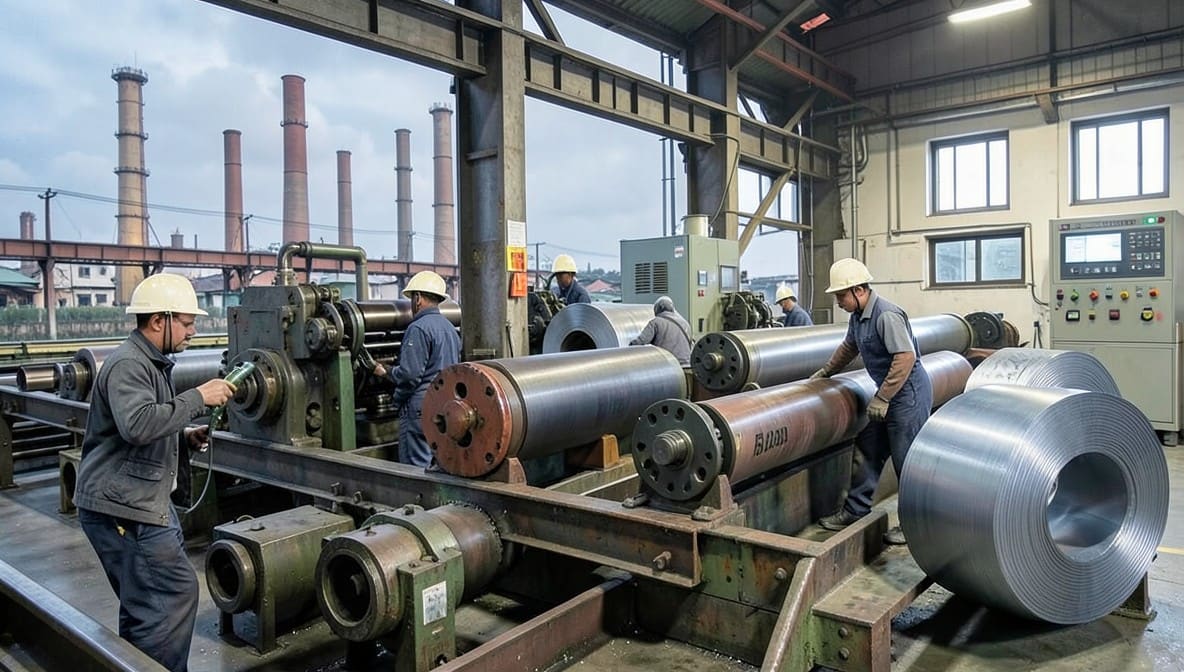
The dispute centres on the classification of services rendered by B.S. Biswal & Company (Biswal) to Beekay Steel Industries Ltd. (Beekay). Beekay, a manufacturer of steel products under Chapter 72 of the Central Excise Tariff Act, engaged Biswal to perform production-related tasks including hot rolling and housekeeping. The Revenue classified this as 'Manpower Recruitment and Supply Agency Service', attracting service tax under the Finance Act, 1994. Biswal and Beekay contended that the arrangement was a genuine job work contract for manufacturing excisable goods, falling outside the service tax net.
Key Facts
- Biswal was initially registered as a manpower supplier and paid service tax up to March 2008.
- On 01.04.2008, a new contractual arrangement was executed via Letter No. BSIL/F/VS/002A/08-09.
- The agreement required Biswal to produce a specified daily quantity of Hot Rolled Products.
- Payment was structured as job charges of Rs. 160 per metric tonne (MT) of finished goods produced.
- The job charges were inclusive of statutory levies, margin, and all labour-related costs.
- Biswal was responsible for hiring, paying, and managing its own labour.
- The agreement explicitly stated: "labour engaged to produce given result will be under your control and that M/s BSIL do not undertake any control over the labour."
- Biswal was obligated to maintain Beekay’s machinery, comply with statutory laws, and operate during fixed shift hours (06:00 - 18:00).
- Monthly job bills were submitted and settled within 10 days of receipt.
- Either party could terminate the agreement with one month’s notice.
- Biswal stopped filing ST-3 returns from 01.04.2008, triggering departmental scrutiny.
- Show Cause Notices were issued for multiple periods: 01.04.2008 - 30.06.2012, 01.07.2012 - 30.09.2013, 01.10.2013 - 31.03.2015, and 01.04.2015 - 31.03.2016.
- Total service tax demand across all periods aggregated Rs. 1,90,00,000+, with penalties under Sections 76, 77, and 78 of the Finance Act, 1994.
Procedural History
- 01.04.2008: Execution of new contractual arrangement between Biswal and Beekay.
- 23.10.2013: Show Cause Notice issued to Biswal for period 01.04.2008 - 30.06.2012.
- 23.04.2014: Show Cause Notice issued to Biswal for period 01.07.2012 - 30.09.2013.
- 14.10.2015: Show Cause Notice issued to Biswal for period 01.10.2013 - 31.03.2015.
- 19.08.2014: Show Cause Notice issued to Beekay for period 01.07.2012 - 31.03.2014.
- 28.11.2016: Show Cause Notice issued to Beekay for period 01.04.2015 - 31.03.2016.
- 31.05.2016: Commissioner (Appeals - II) confirmed demands against Biswal (Order No. 209 & 210/2016).
- 16.12.2016: Commissioner (Appeals - II) confirmed demand against Beekay (Order No. 456/2016).
- 31.01.2017: Commissioner (Appeals - II) confirmed demand against Biswal for 01.10.2013 - 31.03.2015 (Order No. 49/2017).
- 29.01.2018: Commissioner (Audit - I) upheld demand against Beekay for 01.04.2015 - 31.03.2016 (Order No. 11/2017-2018).
- 2016 - 2018: Appeals filed before CESTAT Chennai (ST/41753, 41754/2016; ST/40559/2017; ST/40860/2017; ST/40819/2018).
- 09.01.2026: Oral arguments heard by CESTAT Chennai.
- 17.04.2026: Final order passed.
The Parties' Positions
For the Appellants (Biswal & Beekay)
- The arrangement was a contract for service (job work), not a contract of service (manpower supply).
- Payment was linked exclusively to output (MT of finished goods), not to number of workers or hours worked.
- The contract explicitly vested control of labour with Biswal, negating any employer-employee relationship with Beekay.
- The activity resulted in manufacture of excisable goods under Chapter 72, falling under the negative list for service tax.
- Biswal bore economic risk: job charges included statutory levies, and profit/loss depended on efficiency and productivity.
- The change from manpower supply to job work was a legitimate tax planning decision, not a sham.
- Relied on Sushilaben Indravadan Gandhi v. New India Assurance Co. Ltd. and Achchey Lal v. U.P. Cooperative Bank Ltd. for multifactor test.
For the Respondent (Revenue)
- The activity involved supplying labour for production and housekeeping, squarely within 'Manpower Recruitment or Supply Agency Service' under Section 65(68) of the Finance Act, 1994.
- Payment structure disguised labour hire as job work to evade tax.
- Fixed shift hours, machinery maintenance duties, and statutory compliance obligations indicated employer-like control.
- Biswal’s prior payment of service tax until 2008 proved the true nature of the activity.
- CBIC Circular No. 96/7/2007-ST supported classification as manpower supply.
- The change in structure was a colourable device to avoid tax liability.
Relief Sought
The appellants sought quashing of all impugned orders, cancellation of service tax demands totalling over Rs. 1.9 crore, withdrawal of penalties under Sections 76, 77, and 78, and consequential relief including refund of any amounts paid under protest.
The Legal Issue
The central question was whether the contractual arrangement between Biswal and Beekay constituted 'Manpower Recruitment or Supply Agency Service' under Section 65(68) of the Finance Act, 1994, or whether it qualified as 'job work' for manufacture of excisable goods, thereby falling outside the service tax net.
Arguments Presented
For the Appellant
The appellants relied on the multifactor test articulated in Achchey Lal v. U.P. Cooperative Bank Ltd. and Sushilaben Indravadan Gandhi v. New India Assurance Co. Ltd. to demonstrate the absence of an employer-employee relationship. They emphasized that control over labour was expressly reserved to Biswal; remuneration was tied to output, not hours or headcount; and Biswal bore economic risk through inclusive job charges. The contract’s structure, including monthly billing, mutual termination rights, and absence of Beekay’s supervision over daily operations, aligned with a principal-to-principal commercial arrangement. They further argued that the shift from manpower supply to job work was a legitimate tax mitigation strategy, protected under Vodafone International Holdings v. Union of India and Shiv Raj Gupta v. CIT, and not a sham or fraudulent device.
For the Respondent
The Revenue contended that the arrangement was a disguised labour hire, citing fixed working hours, machinery maintenance obligations, and statutory compliance duties as indicators of control. It argued that the payment per MT was merely a mechanism to conceal wage payments and that Biswal’s prior tax payments established the true nature of the service. The Revenue relied on CBIC Circular No. 96/7/2007-ST, which states that agencies supplying workers for specific tasks are liable for service tax. It further asserted that the change in structure after 2008 was a deliberate attempt to evade tax liability, rendering the contract a colourable device.
The Court's Analysis
The Tribunal undertook a rigorous analysis of the contractual terms in light of the multifactor test established by the Supreme Court in Achchey Lal and Sushilaben. It rejected the Revenue’s reliance on the control test in isolation, noting that the Supreme Court has consistently held that no single factor is determinative.
"The most that profitably can be done is to examine all the factors that have been referred to in the cases on the topic. Clearly, not all of these factors would be relevant in all these cases or have the same weight in all cases."
The Tribunal found that the contract’s core feature - payment linked to output (Rs. 160 per MT) - was decisive. This aligned with the mode of remuneration test under the multifactor framework, indicating a contract for service rather than employment. The fact that job charges included statutory levies and margin demonstrated that Biswal bore the economic risk and had a genuine chance of profit or loss, a hallmark of independent contracting.
The Tribunal further noted that the explicit contractual clause - "labour engaged to produce given result will be under your control and that M/s BSIL do not undertake any control over the labour" - was not merely a formality but a material term that negated the existence of a master-servant relationship. The obligation to maintain machinery and adhere to shift hours were deemed operational necessities, not indicators of control over the manner of work.
The Revenue’s argument that the arrangement was a post-2008 device to evade tax was dismissed. The Tribunal held that tax mitigation through legitimate restructuring of business arrangements is lawful, as affirmed in Vodafone and Shiv Raj Gupta. The burden to prove fraud or sham lay with the Revenue, which failed to adduce any evidence of dishonest intent or artificiality in the transaction.
The Tribunal concluded that the activity was not 'manpower supply' but 'job work' for manufacture of excisable goods, and therefore, not subject to service tax under the relevant statutory framework.
The Verdict
The appellants succeeded. The Tribunal set aside all impugned orders dated 31.05.2016, 16.12.2016, 31.01.2017, and 29.01.2018. All service tax demands totalling Rs. 1,90,00,000+ and associated penalties under Sections 76, 77, and 78 of the Finance Act, 1994, were cancelled. The appellants are entitled to consequential relief, including refund of any amounts paid under protest, subject to applicable procedural requirements under law.
What This Means For Similar Cases
Job Work Must Be Contractually Defined
- Practitioners must ensure that job work agreements explicitly state: (i) payment is linked to output, not manpower; (ii) the contractor retains full control over labour; and (iii) economic risk (profit/loss) rests with the contractor.
- Vague or ambiguous contracts will invite Revenue scrutiny and risk reclassification as manpower supply.
Tax Mitigation Is Lawful - But Documentation Is Key
- A change in business model to reduce tax liability is not per se suspicious.
- The burden of proving fraud or sham lies with the Revenue; taxpayers need not prove legitimacy.
- Maintain contemporaneous records: signed contracts, payment ledgers, job bills, and internal communications.
Control Is Not Just About Supervision - It’s About Legal Right
- Operational coordination (e.g., shift hours) does not equate to legal control.
- The critical question is: Who has the legal right to direct how the work is performed? If the answer is the contractor, the arrangement is likely job work.
- Mere presence of statutory compliance obligations does not convert job work into employment.
Service Tax Classification Turns on Substance, Not Label
- Labels like 'job work' or 'manpower supply' are irrelevant; courts look at the substance of the relationship.
- The multifactor test is now the definitive framework - control, remuneration, risk, and integration must be evaluated holistically.
- CBIC circulars cannot override statutory interpretation grounded in judicial precedent.