The Central Excise and Service Tax Appellate Tribunal (CESTAT) has clarified a critical boundary in the application of compounded levy under the Central Excise Act, 1944, holding that manual packing of goods - even when sealed using electric machines - does not trigger the compulsory duty regime under Section 3A. This decision resolves long-standing ambiguity for manufacturers of branded chewing tobacco and sets a precedent for interpreting statutory definitions with precision.
Background & Facts
The Dispute
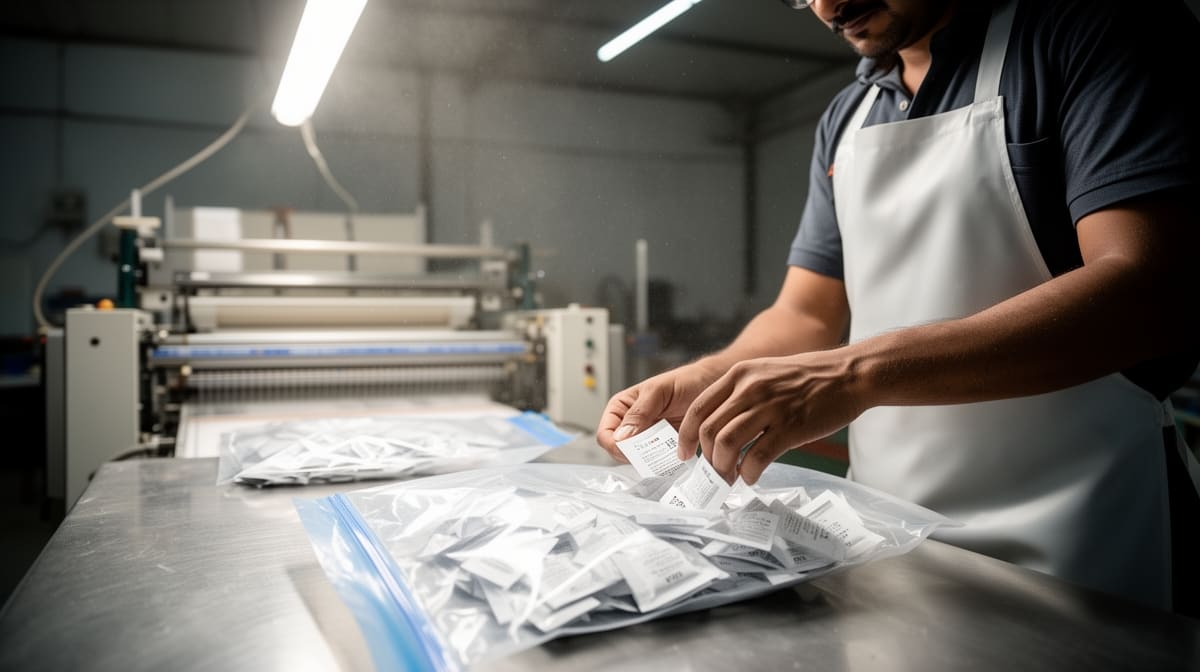
The respondent, M/s Tej Ram Dharam Paul, manufactured branded chewing tobacco in the form of "filter khaini" - small sachets of tobacco wrapped in filter paper or fabric. These sachets were produced using nine Form, Fill and Seal (FFS) machines, which automatically formed, filled, and sealed the individual sachets. Subsequently, ten such sachets were manually placed into pre-zipped plastic pouches, which were then sealed using continuous band sealing machines powered by electricity. The Revenue contended that this entire process fell under the compounded levy scheme under Section 3A of the Central Excise Act, 1944, which applies to goods packed with the aid of packing machines.
Procedural History
- 2010: Central Excise authorities conducted a search and issued show cause notices alleging evasion of compounded duty.
- 2010: Deputy Commissioner, Sangrur, issued a clarification that filter pillow sachets made with FFS machines were not subject to compounded levy if further packed manually.
- 2011: Commissioner (Appeals) upheld the clarification and dropped proceedings.
- 2013: CESTAT Delhi, in Commissioner of C.Ex. Chandigarh v. Tej Ram Dharam Paul, dismissed the Revenue’s appeal, affirming the lower authority’s view.
- 2014: Revenue filed fresh appeals before CESTAT Chandigarh, challenging the same position.
Relief Sought
The Revenue sought to set aside the order dropping the show cause notices and to impose compounded duty under Section 3A on the respondent’s entire production. The respondent sought dismissal of the appeals, relying on the binding precedent of CESTAT Delhi and the plain language of the relevant notifications.
The Legal Issue
The central question was whether Section 3A of the Central Excise Act, 1944, applies to goods where the final packaging into branded pouches is done manually - even if the pouches are sealed using electrically operated band sealing machines - and whether the term "packing machine" in the notifications includes such sealing equipment.
Arguments Presented
For the Appellant
The Revenue argued that the continuous band sealing machine qualifies as a "packing machine" under the inclusive definition in Notification No. 10/2010-C.E.(N.T.), and that the sealing of pouches is an integral part of the packing process. It contended that the Board’s letter dated 05.03.2010 did not cover cases where sealing was done mechanically, and that the Explanation 5 to Notification No. 16/2010-CE must be read to mean that any packing of chewing tobacco into pouches - regardless of method - triggers the compounded levy. It further argued that the CESTAT Delhi judgment was wrongly decided and should not bind the present tribunal.
For the Respondent
The respondent relied on the binding precedent of Commissioner of C.Ex. Chandigarh v. Tej Ram Dharam Paul (2013) and the plain wording of Explanation 5 to Notification No. 16/2010-CE, which defines "filter khaini" as chewing tobacco packed in sachets before being packed in pouches with the aid of a packing machine. It emphasized that the manual insertion of sachets into pouches, even with mechanical sealing, does not constitute packing by machine. It also cited the Board’s clarification that manual packing with heat sealers is explicitly excluded from the compounded levy scheme.
The Court's Analysis
The Tribunal undertook a meticulous textual and contextual analysis of the statutory framework. It emphasized that Section 3A and its supporting notifications must be interpreted strictly, as they impose a simplified but burdensome duty regime. The key lay in the structure of Explanation 5 to Notification No. 16/2010-CE: "filter khaini" means chewing tobacco which is packed in sachets of filter paper or fabric before being packed in pouches with the aid of a packing machine.
"The word 'with the aid of packing machine' is used in relation to the activity of further packing in pouches. The activity of packing of chewing tobacco in sachets/filter paper has not been qualified with the words 'with the aid of packing machine'."
The Tribunal agreed with the lower authorities that the grammatical structure of the Explanation clearly links the phrase "with the aid of a packing machine" to the act of packing into pouches - not to the prior formation of sachets. Since the sachets were formed by FFS machines but inserted into pouches manually, the final packing step did not meet the statutory threshold.
The Tribunal further distinguished the use of band sealing machines from "packing machines" by referencing the Board’s 2010 clarification, which explicitly excluded manual packing - even with heat or band sealers - from the compounded levy. It analogized the process to tea bags: individual sachets without branding are intermediate products, not the final marketable goods. Only the final pouch, bearing brand, MRP, and health warnings, constitutes the notified good, and its manual assembly excluded it from Section 3A.
The Tribunal also affirmed the principle of res judicata in administrative law, noting that the Revenue had previously accepted the CESTAT Delhi judgment and had not appealed it. To permit a fresh challenge on identical facts would undermine consistency and legitimate expectation.
The Verdict
The respondent won. The Court held that Section 3A of the Central Excise Act, 1944, does not apply to chewing tobacco packed in pouches where the final insertion of sachets is done manually, even if the pouches are sealed using electrically operated machines. The Revenue’s appeals were dismissed.
What This Means For Similar Cases
Manual Packing Excludes Goods from Compounded Levy
- Practitioners must now argue that any step involving human intervention in the final packaging - such as inserting sachets, folding, or placing into branded pouches - excludes the product from Section 3A, even if sealing is mechanical.
- The burden shifts to the Revenue to prove that the final packaging into market-ready containers was performed by a machine, not by hand.
Sealing Machines Are Not Packing Machines Under Statutory Definition
- Band sealers, heat sealers, and similar devices are not "packing machines" under the notifications unless they perform the function of forming, filling, and sealing as a unitary process.
- Manufacturers may safely use electric sealing for pouches without triggering compounded levy, provided the insertion of contents is manual.
Precedent Binding Even When Revenue Disagrees
- When the Revenue accepts a tribunal judgment in one case and later re-litigates the same issue, courts may invoke principles of res judicata and legitimate expectation to dismiss the appeal.
- Practitioners should cite Tej Ram Dharam Paul (2013) as binding authority in all similar cases involving filter khaini or analogous products.