The Income Tax Appellate Tribunal (ITAT), Delhi, has delivered a significant ruling on the validity of re-assessment notices under Section 148 of the Income Tax Act, 1961, where the escaped income does not meet the statutory threshold of ₹50 lakh. The Tribunal quashed the notice issued to the assessee, holding that the Assessing Officer’s mechanical reliance on information from the Insight Portal, without verifying the nature of transactions, rendered the proceedings invalid. This judgment reinforces the principle that re-assessment notices must satisfy the preconditions under Section 149(1)(b) to be legally tenable.
Background & Facts
The Dispute
The appellant, Shri Vijay Kumar Soni, an individual assessee, filed his return of income for the Assessment Year (AY) 2014-15 on 28 September 2014. The Department received information through the Insight Portal, based on an investigation report from the Investigation Wing, Mumbai, alleging that the assessee was engaged in trades through the National Spot Exchange Limited (NSEL). The report indicated that M/s Anand Rathi Commodities Limited had executed client code modifications, issuing contract notes in the assessee’s name for transactions originally carried out by other parties. The total transaction amount, as alleged by the Department, was ₹2,48,18,275.
Key Facts
- The assessee’s return for AY 2014-15 was filed on 28 September 2014.
- The Department received information on client code modifications in NSEL trades, suggesting escapement of income.
- The Assessing Officer (AO) issued a notice under Section 148 on 16 April 2021, followed by a notice under Section 148A(b) on 29 June 2022.
- The AO alleged that the assessee’s transactions amounted to ₹2,48,18,275, which had escaped assessment.
- The assessee contended that the profit embedded in the transactions was only ₹4,27,778, as evidenced by the computation of profit from purchase transactions.
Procedural History
- 30 May 2023: AO passed an order under Section 147 read with Section 144B of the Act.
- 7 August 2025: CIT(A), NFAC, Delhi, confirmed the AO’s order, upholding the re-assessment proceedings.
- 4 June 2026: Appeal heard by the ITAT Delhi Bench-F.
- 12 June 2026: ITAT pronounced its order, allowing the assessee’s appeal.
The Parties' Positions
For the Appellant
- The assessee argued that the AO’s action was mechanical and based on unverified information from the Insight Portal.
- The profit from the transactions was only ₹4,27,778, which is below the ₹50 lakh threshold prescribed under Section 149(1)(b) of the Act.
- The assessee relied on the judgment of the Bombay High Court in Ram Nebhnani HUF, which held that only the net income from buy and sell transactions can be taxed, not the gross transaction amount.
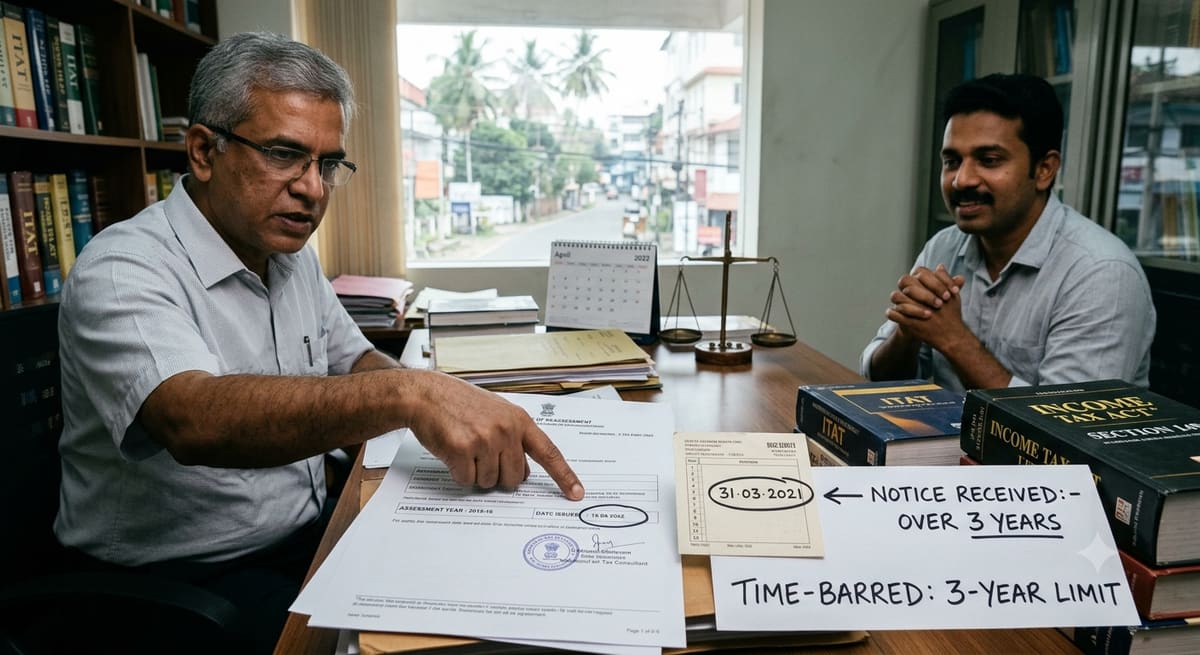
- The assessee contended that the notice under Section 148 was issued beyond the three-year limitation period under the unamended provisions of Section 147.
For the Respondent
- The Department argued that the escaped income was represented by the gross transaction amount of ₹2,48,18,275, which exceeded the ₹50 lakh threshold.
- The AO relied on the investigation report from the Mumbai Wing, which alleged client code modifications by brokers.
- The Department contended that the amended provisions of Section 149 applied, and the notice was valid.
Relief Sought
The assessee sought annulment of the re-assessment proceedings, arguing that:
- The notice under Section 148 was invalid as it was issued beyond the three-year limitation period.
- The escaped income did not meet the ₹50 lakh threshold under Section 149(1)(b).
- The AO’s order was mechanical and perverse, as it failed to consider the profit element of the transactions.
The Legal Issue
The central legal question was whether a notice under Section 148 of the Income Tax Act, 1961, could be validly issued where:
- The escaped income was below the ₹50 lakh threshold prescribed under Section 149(1)(b).
- The notice was issued beyond the three-year limitation period under the unamended provisions of Section 147.
- The AO mechanically relied on unverified information without assessing the net income from the transactions.
Arguments Presented
For the Appellant
- Limitation Period: The assessee argued that the notice under Section 148 was issued on 16 April 2021, beyond the three-year period from the end of AY 2014-15, rendering it invalid under the unamended Section 147.
- Threshold Requirement: The profit from the transactions was only ₹4,27,778, which is below the ₹50 lakh threshold under Section 149(1)(b). Thus, the notice was invalid.
- Mechanical Action: The AO failed to verify the nature of transactions and presumed escapement of income based on gross figures, contrary to the law laid down in Ram Nebhnani HUF.
- Judicial Precedent: The assessee relied on the Bombay High Court’s judgment in Ram Nebhnani HUF, which held that only the net income from buy and sell transactions can be taxed, not the gross amount.
For the Respondent
- Gross Transaction Amount: The Department contended that the escaped income was ₹2,48,18,275, which exceeded the ₹50 lakh threshold under Section 149(1)(b).
- Investigation Report: The AO relied on the investigation report from the Mumbai Wing, which alleged client code modifications by brokers, justifying the re-assessment.
- Amended Provisions: The Department argued that the amended provisions of Section 149 applied, and the notice was valid.
The Court's Analysis
The ITAT Delhi meticulously examined the legal framework governing re-assessment proceedings under Sections 147, 148, and 149 of the Income Tax Act. The Tribunal noted the following key points:
-
Threshold Requirement under Section 149(1)(b): The Tribunal observed that Section 149(1)(b) permits the issuance of a notice under Section 148 only if the escaped income is ₹50 lakh or more. In this case, the profit from the transactions was only ₹4,27,778, which is far below the threshold. The AO’s reliance on the gross transaction amount was misplaced, as only the net income could be considered for taxation.
"Admittedly, in this case, the amount of profit embedded in the transaction is ₹4,27,778/- which is much below the amount prescribed under Section 149(1)(b) of the Act i.e., ₹50 lakhs or more than that."
-
Judicial Precedent: The Tribunal relied on the Bombay High Court’s judgment in Ram Nebhnani HUF, which held that only the net income from buy and sell transactions can be taxed, not the gross transaction amount. The AO’s failure to distinguish between gross transactions and net income rendered the notice invalid.
"It is well settled that only the net income from the buy and sell transactions can be brought to tax in petitioner's hand and not the entire sum as done in this case."
-
Mechanical Action by the AO: The Tribunal criticized the AO for mechanically relying on the Insight Portal information without verifying the nature of the transactions or the profit element. The AO’s approach was contrary to the principles of natural justice and judicial precedents.
-
Limitation Period: The Tribunal noted that the notice under Section 148 was issued on 16 April 2021, beyond the three-year limitation period under the unamended Section 147. The Supreme Court’s judgment in Union of India v. Ashish Agarwal was cited, which held that the defense available under Section 149 continues to apply to assessees.
The Verdict
The ITAT Delhi allowed the assessee’s appeal, quashing the notice under Section 148 and the subsequent re-assessment proceedings. The Tribunal held that:
- The notice under Section 148 was invalid as the escaped income did not meet the ₹50 lakh threshold under Section 149(1)(b).
- The AO’s mechanical reliance on unverified information rendered the proceedings perverse and untenable.
- The re-assessment proceedings were barred by limitation, as the notice was issued beyond the three-year period under the unamended Section 147.
What This Means For Similar Cases
The ₹50 Lakh Threshold Is Non-Negotiable
- Practitioners must scrutinize the escaped income claimed by the AO to ensure it meets the ₹50 lakh threshold under Section 149(1)(b).
- Gross transaction amounts cannot be presumed to represent escaped income. Only the net income from transactions is taxable.
- Assessees should demand detailed computations from the AO to verify whether the threshold is satisfied.
Mechanical Action by AO Is Vulnerable to Challenge
- The ITAT has criticized mechanical reliance on portal information without verifying the nature of transactions.
- Assessees can challenge re-assessment proceedings if the AO fails to distinguish between gross transactions and net income.
- Judicial precedents, such as Ram Nebhnani HUF, must be cited to argue against perverse or arbitrary actions by the AO.
Limitation Period Remains a Strong Defense
- The three-year limitation period under the unamended Section 147 continues to apply, as held by the Supreme Court in Union of India v. Ashish Agarwal.
- Assessees should verify the date of issuance of notices to ensure compliance with the limitation period.
- Delayed notices can be challenged on limitation grounds, providing a strong defense in re-assessment proceedings.