Topic

Section 148

Section 148 of the Income Tax Act, 1961, empowers the Income Tax Department to issue a notice for reassessment of income previously assessed, if it has reason to believe income has escaped assessment.

37 articlesLatest 2 days ago
Section 148 NI Act | Statutory 20% Deposit Floor Non-Negotiable; Appellate Court Lacks Discretion to Reduce : Uttarakhand HC
Case Law Analysis

Section 148 NI Act | Statutory 20% Deposit Floor Non-Negotiable; Appellate Court Lacks Discretion to Reduce : Uttarakhand HC

The Uttarakhand High Court ruled that the 20% deposit under Section 148 NI Act is a statutory floor that appellate courts cannot reduce, holding that a Sessions Judge's reduction to 10% and subsequent bail cancellation for non-compliance with the unlawful condition was impermissible. This safeguards appellants from arbitrary deposit reductions and ensures bail conditions adhere strictly to the statutory mandate.
Section 151 Income Tax Act | Reassessment Beyond 3 Years Requires PCCIT/CCIT Sanction, Not PCIT Approval : ITAT Kolkata
Case Law Analysis
|Income Tax Appellate Tribunal

Section 151 Income Tax Act | Reassessment Beyond 3 Years Requires PCCIT/CCIT Sanction, Not PCIT Approval : ITAT Kolkata

ITAT Kolkata held that reassessment beyond three years under Section 148 mandates PCCIT or CCIT sanction under Section 151; PCIT approval is jurisdictionally invalid. The tribunal quashed a notice where only PCIT approval was obtained, reinforcing the strict hierarchy for time-barred proceedings and protecting taxpayers from procedurally flawed orders.

Section 138 NI Act | Mechanical 100% Deposit Condition for Suspension Quashed; 20% Deposit + Undertaking Substituted per Section 148 : Gujarat HC
Case Law Analysis

Section 138 NI Act | Mechanical 100% Deposit Condition for Suspension Quashed; 20% Deposit + Undertaking Substituted per Section 148 : Gujarat HC

The Gujarat High Court held that conditions for suspending sentence in Section 138 NI Act appeals cannot be imposed mechanically, quashing a Sessions Court order mandating 100% cheque amount deposit. The Court substituted this with a 20% deposit and an undertaking to attend hearings, aligning with Section 148 NI Act's framework. This ruling protects appellants from oppressive pre-conditions while ensuring the complainant's interim relief.

Reopening of assessment based on pre-2021 search material must use Sec 153C, not Sec 148 | Income Tax Act assessment reopening : Gujarat HC
Case Law Analysis

Reopening of assessment based on pre-2021 search material must use Sec 153C, not Sec 148 | Income Tax Act assessment reopening : Gujarat HC

Assessing officers cannot invoke Section 148 to reopen returns when the material originates from a search conducted before 31 March 2021; such cases fall within the block period of Section 153C. This limits revenue’s power to reassess older assessments and guides practitioners on the correct statutory basis. Taxpayers with assessments from that period are protected from improper reopening.

Section 148 notice invalid if assessment order issued post-death of assessee; proceedings void ab initio | Deceased taxpayer : ITAT Dehradun
Case Law Analysis
|Income Tax Appellate Tribunal

Section 148 notice invalid if assessment order issued post-death of assessee; proceedings void ab initio | Deceased taxpayer : ITAT Dehradun

An assessment order issued under Section 148 after the assessee’s death is deemed void from the outset, rendering the notice ineffective. This ruling bars revenue authorities from reopening assessments of deceased taxpayers without proper procedural basis, protecting legal heirs from unwarranted tax demands.

Commission on Accommodation Entries Taxable at 0.15% of Credits, Not 3%; Section 148 Notice Void Without Section 151(ii) Nod : ITAT Delhi
Case Law Analysis
|Income Tax Appellate Tribunal

Commission on Accommodation Entries Taxable at 0.15% of Credits, Not 3%; Section 148 Notice Void Without Section 151(ii) Nod : ITAT Delhi

The ITAT Delhi held that commission income from accommodation entries must be taxed at a reasonable rate of 0.15% of total credits, rejecting the arbitrary 3% estimate. It also ruled that a reassessment notice under Section 148 is invalid without prior approval from the specified authority under Section 151(ii), protecting assessees from procedural lapses.

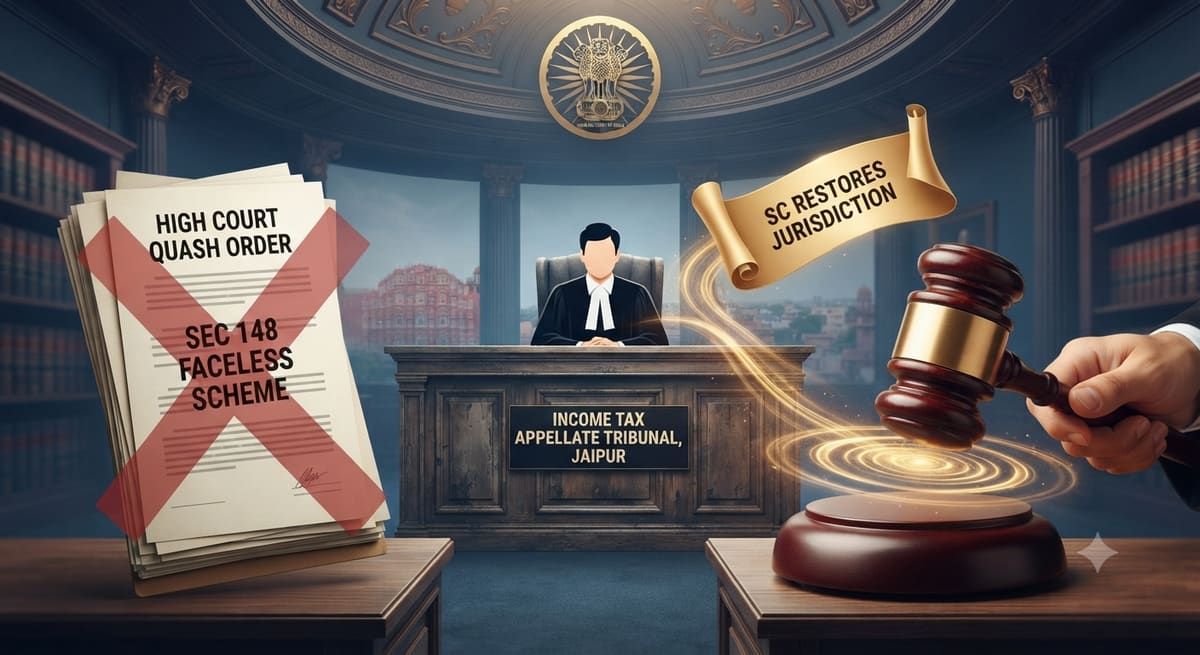
SC Restores ITAT Jaipur’s Reassessment Jurisdiction After HC Quash | Section 148 Faceless Scheme : ITAT Jaipur
Case Law Analysis
|Income Tax Appellate Tribunal

SC Restores ITAT Jaipur’s Reassessment Jurisdiction After HC Quash | Section 148 Faceless Scheme : ITAT Jaipur

Supreme Court set aside a Rajasthan High Court order quashing a Section 148 reassessment notice, restoring the Income Tax Appellate Tribunal Jaipur’s jurisdiction to re-examine the case under the Faceless Assessment Scheme. The ruling clarifies that appellate jurisdiction under the Act remains distinct from writ jurisdiction, impacting reassessment proceedings pending before ITAT.