Income Tax Appellate Tribunal judgments

893 Income Tax Appellate Tribunal judgments explained in plain English: what was decided, the law applied and why it matters. Page 21 of 38.

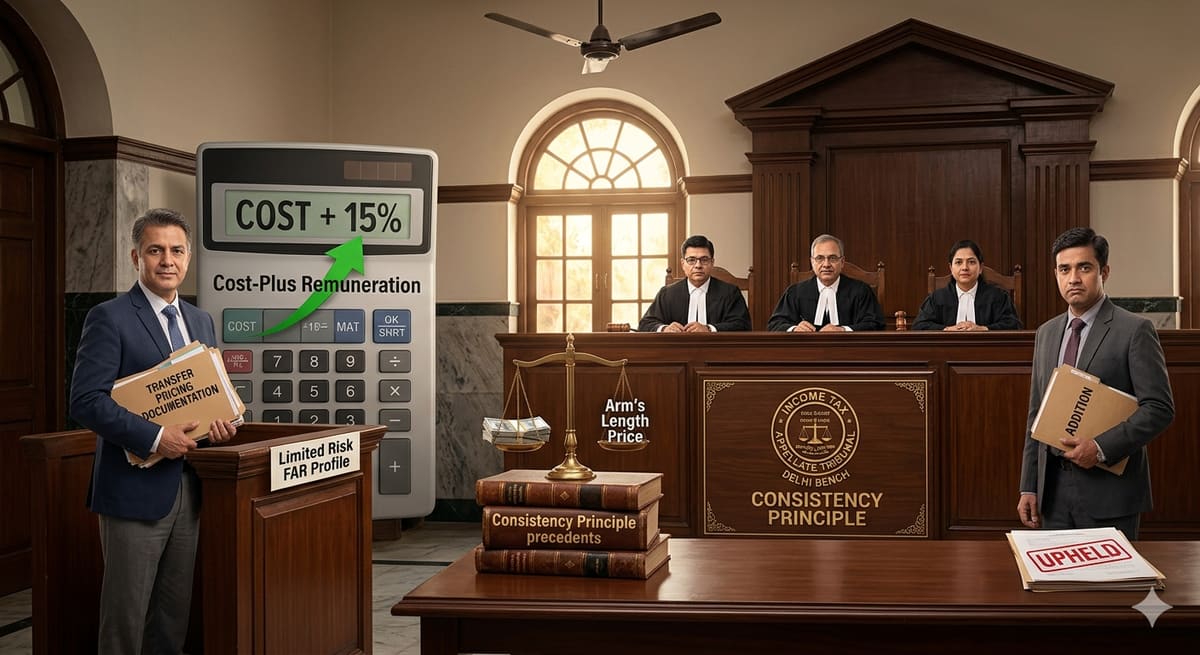
Transfer Pricing | ITAT Delhi Upholds Cost-Plus Remuneration for Limited Risk Service Providers Under Consistency Principle : ITAT Delhi
Case Law Analysis
|Income Tax Appellate Tribunal

Transfer Pricing | ITAT Delhi Upholds Cost-Plus Remuneration for Limited Risk Service Providers Under Consistency Principle : ITAT Delhi

ITAT Delhi ruled that a limited risk service provider is entitled to cost-plus remuneration, rejecting transfer pricing adjustments where benchmarking was inconsistent and DRP directions were ignored. The decision reinforces the consistency principle in transfer pricing, impacting multinational enterprises and tax compliance strategies.

Section 69C IT Act | Entire Bogus Purchase Amount Taxable Without Proof of Genuineness : ITAT Kolkata
Case Law Analysis
|Income Tax Appellate Tribunal

Section 69C IT Act | Entire Bogus Purchase Amount Taxable Without Proof of Genuineness : ITAT Kolkata

ITAT Kolkata rules that when an assessee fails to prove the existence of suppliers, delivery, or transactional genuineness, the entire purchase amount is taxable as unexplained expenditure under Section 69C. The ruling underscores the burden of proof on taxpayers to substantiate transactions, even with banking evidence, to avoid full disallowance.

Section 269SS IT Act | Cash Repayment of Prior Advances Not 'Deposit' Under Section 269SS; Penalty Under Section 271D Invalid Without Natural Justice : ITAT Kolkata
Case Law Analysis
|Income Tax Appellate Tribunal

Section 269SS IT Act | Cash Repayment of Prior Advances Not 'Deposit' Under Section 269SS; Penalty Under Section 271D Invalid Without Natural Justice : ITAT Kolkata

ITAT Kolkata rules that cash repayments of prior advances do not constitute 'deposits' under Section 269SS of the Income Tax Act, setting aside penalties imposed under Section 271D. The Tribunal emphasized the violation of natural justice principles, remanding the case for a fresh hearing with an opportunity for the assessee to present evidence.

Section 144 Income Tax Act | ITAT Bangalore Restores Assessment for Fresh Adjudication Citing Natural Justice Due to Assessee’s Health Issues
Case Law Analysis
|Income Tax Appellate Tribunal

Section 144 Income Tax Act | ITAT Bangalore Restores Assessment for Fresh Adjudication Citing Natural Justice Due to Assessee’s Health Issues

ITAT Bangalore condoned a 114-day delay in filing an appeal and restored the assessment to the Assessing Officer, emphasizing that ex-parte additions under Section 144 without considering the assessee’s health constraints violate procedural fairness. The ruling underscores the assessee’s right to submit evidence and mandates fresh adjudication where unexplained income additions were made without proper opportunity.

Section 11 Income Tax Act | Lost Trust Deed Does Not Permanently Disqualify Exemption; Registration Reinstated via Affidavit : ITAT Bangalore
Case Law Analysis
|Income Tax Appellate Tribunal

Section 11 Income Tax Act | Lost Trust Deed Does Not Permanently Disqualify Exemption; Registration Reinstated via Affidavit : ITAT Bangalore

ITAT Bangalore rules that a charitable trust’s exemption under Section 11 cannot be denied solely due to a lost trust deed. The tribunal permits reinstatement of registration through a sworn affidavit and condonation of delay, ensuring trusts are not penalized for procedural lapses beyond their control.

Section 2(42A) Income Tax Act | Holding Period for Capital Assets Begins at Final Allotment, Not Provisional Letter: ITAT Mumbai
Case Law Analysis
|Income Tax Appellate Tribunal

Section 2(42A) Income Tax Act | Holding Period for Capital Assets Begins at Final Allotment, Not Provisional Letter: ITAT Mumbai

ITAT Mumbai rules that the acquisition date for capital gains computation under Section 2(42A) of the Income Tax Act is the date of final, binding allotment and registration, not the issuance of provisional letters. This precedent clarifies the holding period calculation, impacting property transactions and tax liability assessments for taxpayers.

Section 56(2)(viib) IT Act | CCD Conversion Prior to Share Allotment Exempt from Share Premium Taxation : ITAT Delhi
Case Law Analysis
|Income Tax Appellate Tribunal

Section 56(2)(viib) IT Act | CCD Conversion Prior to Share Allotment Exempt from Share Premium Taxation : ITAT Delhi

ITAT Delhi rules that Section 56(2)(viib) of the Income Tax Act applies only when consideration is received in the assessment year of share allotment. Funds received earlier via Compulsorily Convertible Debentures (CCD) conversion do not attract tax on share premium, even if valuation is based on prior balance sheets. The ruling clarifies the timing of receipt for tax applicability under this provision.

Section 197(b) IDS 2016 | Non-Payment of Tax Voids Amnesty, Income Taxable in Declaration Year : ITAT Delhi
Case Law Analysis
|Income Tax Appellate Tribunal

Section 197(b) IDS 2016 | Non-Payment of Tax Voids Amnesty, Income Taxable in Declaration Year : ITAT Delhi

ITAT Delhi holds that failure to pay tax under the Income Declaration Scheme 2016 within the stipulated time renders the declaration invalid, making the disclosed income taxable in the year of declaration rather than the original assessment year. This ruling underscores the strict compliance requirement for availing amnesty benefits under the scheme.

Section 10(46) IT Act | Pending CBDT Notification Does Not Bar De Novo Assessment: ITAT Mumbai Directs Fresh Adjudication on Exemption Eligibility
Case Law Analysis
|Income Tax Appellate Tribunal

Section 10(46) IT Act | Pending CBDT Notification Does Not Bar De Novo Assessment: ITAT Mumbai Directs Fresh Adjudication on Exemption Eligibility

ITAT Mumbai ruled that the absence of a CBDT notification under Section 10(46) of the Income Tax Act does not preclude a de novo assessment of exemption claims. The Tribunal set aside the denial of exemption and directed fresh adjudication, keeping all grounds open, including the assessee's claim of being a 'State' instrumentality under Article 289. This ruling clarifies that procedural pendency cannot defeat substantive rights to exemption.

Section 148 IT Act | Reassessment Notices Issued Beyond Limitation Period Void Ab Initio: ITAT Delhi Applies Rajeev Bansal Precedent
Case Law Analysis
|Income Tax Appellate Tribunal

Section 148 IT Act | Reassessment Notices Issued Beyond Limitation Period Void Ab Initio: ITAT Delhi Applies Rajeev Bansal Precedent

ITAT Delhi quashes reassessment notices for AYs 2013-14 and 2014-15, ruling that notices issued under the old Section 148 provisions after 31.03.2021 are time-barred. The Tribunal relied on the Supreme Court’s decision in Union of India v. Rajeev Bansal, reinforcing strict compliance with limitation periods in tax reassessment proceedings.

Section 68 IT Act | ITAT Delhi Mandates Corroborative Evidence & Cross-Examination Rights for Unexplained Cash Credits : ITAT Delhi
Case Law Analysis
|Income Tax Appellate Tribunal

Section 68 IT Act | ITAT Delhi Mandates Corroborative Evidence & Cross-Examination Rights for Unexplained Cash Credits : ITAT Delhi

ITAT Delhi quashed Rs. 49.5L and Rs. 54.5L additions under Section 68, ruling that additions cannot stand without incriminating material or opportunity for cross-examination. The decision reinforces natural justice principles in income tax assessments, impacting taxpayers facing similar allegations of accommodation entries.

Section 56 Income Tax Act | Notional Interest Entries in Seized Diaries Not Taxable as Real Income : ITAT Ahmedabad
Case Law Analysis
|Income Tax Appellate Tribunal

Section 56 Income Tax Act | Notional Interest Entries in Seized Diaries Not Taxable as Real Income : ITAT Ahmedabad

ITAT Ahmedabad clarifies that notional interest entries found in seized diaries do not constitute taxable income under Section 56 of the Income Tax Act, preventing double taxation. The ruling reinforces that only real accrual of income, not hypothetical accounting entries, can be taxed, offering relief to assessees facing arbitrary additions based on seized documents.

Section 115BBE Not Retrospective | Cash Deposits During Demonetisation Not Automatically Taxable as Unexplained Income : ITAT Delhi
Case Law Analysis
|Income Tax Appellate Tribunal

Section 115BBE Not Retrospective | Cash Deposits During Demonetisation Not Automatically Taxable as Unexplained Income : ITAT Delhi

ITAT Delhi rules that Section 115BBE of the Income Tax Act applies only post-01.04.2017, reducing a Rs. 1.49 crore addition to Rs. 5 lakh for cash deposits during demonetisation. The tribunal emphasised that regular business activities and cash sales in unorganised sectors justify a lower addition, setting a precedent for similar assessments.

AMP Expenses as Revenue Expenditure | ITAT Delhi Rejects Capitalization for Brand Building by Subsidiary
Case Law Analysis
|Income Tax Appellate Tribunal

AMP Expenses as Revenue Expenditure | ITAT Delhi Rejects Capitalization for Brand Building by Subsidiary

ITAT Delhi rules that advertisement, marketing, and sales promotion expenses incurred by a subsidiary are revenue in nature, even if they enhance the parent company’s brand. The ruling dismisses the Revenue’s appeal, reinforcing that such expenses cannot be capitalized under transfer pricing norms, offering clarity for multinational corporations on tax treatment of AMP costs.

Section 153C Income Tax Act | Assessments Time-Barred If Satisfaction Note Not Recorded Within 6 AYs: ITAT Delhi Upholds Ojjus Medicare Precedent
Case Law Analysis
|Income Tax Appellate Tribunal

Section 153C Income Tax Act | Assessments Time-Barred If Satisfaction Note Not Recorded Within 6 AYs: ITAT Delhi Upholds Ojjus Medicare Precedent

ITAT Delhi quashes assessments for AY 2014-15 and 2015-16, ruling that satisfaction notes under Section 153C must be recorded within six assessment years to validate proceedings. The tribunal reaffirms the Delhi High Court’s holding in Ojjus Medicare, emphasizing strict procedural compliance to prevent time-barred assessments.

Section 263 IT Act | Revisional Jurisdiction Barred If AO Conducted Detailed Inquiry: ITAT Ahmedabad
Case Law Analysis
|Income Tax Appellate Tribunal

Section 263 IT Act | Revisional Jurisdiction Barred If AO Conducted Detailed Inquiry: ITAT Ahmedabad

ITAT Ahmedabad sets aside a revision order under Section 263, ruling that mere disagreement with the Assessing Officer’s findings does not justify revision if the AO conducted thorough inquiries. The decision reinforces that revisional powers cannot be exercised on a change of opinion alone, safeguarding assessees from arbitrary reassessments.

Section 14A IT Act | No Disallowance Under Rule 8D If Own Funds Exceed Investments: ITAT Delhi Sets Precedent for Banking & Finance Sector
Case Law Analysis
|Income Tax Appellate Tribunal

Section 14A IT Act | No Disallowance Under Rule 8D If Own Funds Exceed Investments: ITAT Delhi Sets Precedent for Banking & Finance Sector

ITAT Delhi rules that if an assessee’s own funds surpass the value of dividend-yielding investments, disallowance under Section 14A read with Rule 8D is unwarranted-even without separate books of accounts. The ruling clarifies that the Assessing Officer must demonstrate nexus between borrowed funds and investments before invoking Rule 8D, offering relief to entities with surplus liquidity.

Section 68 IT Act | Book Entries Without Cash Flow or Genuine Transactions Cannot Be Taxed as Unexplained Income : ITAT Mumbai
Case Law Analysis
|Income Tax Appellate Tribunal

Section 68 IT Act | Book Entries Without Cash Flow or Genuine Transactions Cannot Be Taxed as Unexplained Income : ITAT Mumbai

ITAT Mumbai rules that mere book adjustments between group companies, without actual cash flow or proof of genuineness, do not constitute unexplained income under Section 68 of the Income Tax Act. The assessee’s failure to substantiate creditworthiness and transaction authenticity led to the deletion of additions.

Section 54F Income Tax Act | Partial Construction & CGAS Deposit Suffice for Capital Gains Exemption Despite Joint Ownership & Delay: ITAT Delhi
Case Law Analysis
|Income Tax Appellate Tribunal

Section 54F Income Tax Act | Partial Construction & CGAS Deposit Suffice for Capital Gains Exemption Despite Joint Ownership & Delay: ITAT Delhi

ITAT Delhi rules that depositing sale proceeds in Capital Gains Account Scheme (CGAS) and initiating partial construction are sufficient to claim Section 54F exemption, even for jointly owned property and despite court-imposed delays. The ruling clarifies that co-owners need not complete construction within the prescribed timeline to retain tax benefits, reinforcing a pragmatic approach to capital gains exemptions.

Section 167A Income Tax Act | Charitable Trusts Without Section 11 Exemption Taxed as Individuals, Not AOPs: ITAT Delhi
Case Law Analysis
|Income Tax Appellate Tribunal

Section 167A Income Tax Act | Charitable Trusts Without Section 11 Exemption Taxed as Individuals, Not AOPs: ITAT Delhi

ITAT Delhi holds that charitable trusts not availing exemption under Section 11 of the Income Tax Act must be taxed at individual slab rates, not as Associations of Persons (AOPs) under Section 167A. The ruling clarifies that trusts without defined beneficiaries or members are not AOPs, impacting tax liability calculations for non-exempt charitable entities.

Section 2(15) IT Act | Statutory Urban Development Authorities Entitled to Charitable Exemption Under Section 11 : ITAT Delhi
Case Law Analysis
|Income Tax Appellate Tribunal

Section 2(15) IT Act | Statutory Urban Development Authorities Entitled to Charitable Exemption Under Section 11 : ITAT Delhi

ITAT Delhi rules that statutory urban development authorities like Hapur Pilukhuwa Development Authority qualify as charitable institutions under Section 2(15) of the Income Tax Act, entitling them to exemption under Section 11. The tribunal affirms that development activities for public purposes fall within the ambit of 'charitable purpose,' rejecting the Revenue's argument on commercial receipts.