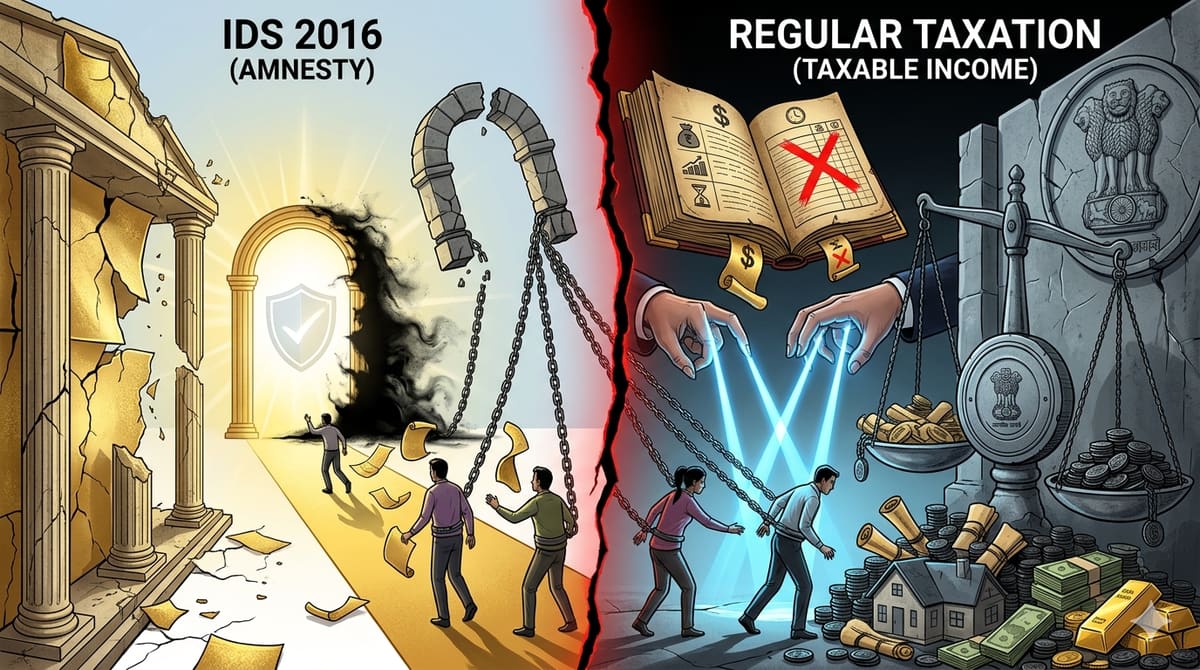
The Income Tax Appellate Tribunal, Delhi Bench, has delivered a significant ruling on the interpretation of Section 197(b) of the Income Declaration Scheme (IDS) 2016. The tribunal held that if an assessee fails to pay the tax, surcharge, and penalty within the stipulated time under the IDS-2016, the undisclosed income shall be chargeable to tax in the previous year in which the declaration was made, not the original assessment year. This judgment clarifies the jurisdictional limits of reassessment under Section 147 of the Income Tax Act, 1961, and underscores the importance of strict compliance with tax payment deadlines under amnesty schemes.
Background & Facts
The Dispute
The appellant, M/s Daffodills Pharmaceuticals Ltd., filed its income tax return for Assessment Year (AY) 2013-14 on 26.09.2013, declaring an income of Rs. 35,07,225. On 28.09.2016, the assessee disclosed an additional amount of Rs. 2,03,17,850 under the Income Declaration Scheme (IDS) 2016 for AY 2013-14. The assessee was required to pay tax of Rs. 91,43,032 on this undisclosed income by 30.09.2017, but failed to do so within the stipulated time.
Key Facts
Return filed for AY 2013-14: 26.09.2013 (Income: Rs. 35,07,225)
Declaration under IDS-2016: 28.09.2016 (Amount: Rs. 2,03,17,850)
Tax payable under IDS-2016: Rs. 91,43,032 (due by 30.09.2017)
Failure to pay tax: Assessee did not deposit the tax within the designated period
Reassessment proceedings: Notice u/s 148 issued on 30.03.2021 after recording reasons and obtaining sanction u/s 151
Revised return filed: 13.04.2021 (Income: Rs. 2,38,25,080, including the IDS-declared amount)
Assessment order: 21.03.2022 (Total income assessed: Rs. 2,38,25,080 u/s 143(3) r/w Section 147)
Procedural History
26.09.2013: Original return filed for AY 2013-14
28.09.2016: Declaration made under IDS-2016 for AY 2013-14
30.09.2017: Last date for payment of tax under IDS-2016 (default by assessee)
30.03.2021: Notice u/s 148 issued for reassessment
13.04.2021: Revised return filed in response to notice u/s 148
21.03.2022: Assessment order passed u/s 143(3) r/w Section 147
20.08.2025: Appeal dismissed by Ld. CIT(A), National Faceless Appeal Centre
07.04.2026: Hearing before ITAT Delhi
30.04.2026: Pronouncement of ITAT order
The Parties' Positions
For the Appellant (Assessee)
The assessee contended that Section 197(b) of the IDS-2016 explicitly states that if tax, surcharge, and penalty are not paid within the stipulated time, the undisclosed income shall be chargeable to tax in the previous year in which the declaration is made. The assessee argued that the Assessing Officer (AO) erred in treating the disclosed amount as undisclosed income for AY 2013-14, as the declaration was made in FY 2016-17. The assessee relied on a similar order dated 30.03.2026 in the case of Kuldip Singh Sethi & Gagan Goyal (PAN: AAJFK8905H), where the department accepted that the income should be taxed in the year of declaration, not the original assessment year.
For the Respondent (Department)
The Ld. Departmental Representative (DR) relied on the orders of the lower authorities, arguing that the assessee's failure to pay the tax within the stipulated time under IDS-2016 rendered the declaration invalid. Consequently, the AO was justified in treating the disclosed amount as undisclosed income for AY 2013-14 and initiating reassessment proceedings u/s 147.
Relief Sought
The assessee sought deletion of the addition of Rs. 2,03,17,850 made by the AO for AY 2013-14, arguing that the income should have been taxed in the year of declaration (FY 2016-17), not the original assessment year.
The Legal Issue
The central question before the tribunal was:
Whether the failure to pay tax under the Income Declaration Scheme 2016 within the stipulated time renders the undisclosed income chargeable to tax in the original assessment year (AY 2013-14) or the previous year in which the declaration was made (FY 2016-17)?
Arguments Presented
For the Appellant
Statutory Interpretation of Section 197(b): The assessee argued that Section 197(b) of IDS-2016 clearly mandates that if tax, surcharge, and penalty are not paid within the stipulated time, the undisclosed income shall be chargeable to tax in the previous year in which the declaration is made. The AO erred in taxing the income for AY 2013-14 instead of FY 2016-17.
Precedent Reliance: The assessee cited the department's own order dated 30.03.2026 in the case of Kuldip Singh Sethi & Gagan Goyal, where the AO accepted that the income disclosed under IDS-2016 but not paid within the stipulated time should be taxed in the year of declaration, not the original assessment year.
Jurisdictional Error: The assessee contended that the AO lacked jurisdiction u/s 147 to reopen the assessment for AY 2013-14, as the income was not undisclosed for that year but was disclosed under IDS-2016 in FY 2016-17.
For the Respondent
Default Under IDS-2016: The department argued that the assessee's failure to pay the tax within the stipulated time under IDS-2016 rendered the declaration invalid, justifying the AO's action of treating the disclosed amount as undisclosed income for AY 2013-14.
Reassessment Validity: The department relied on the orders of the AO and Ld. CIT(A), contending that the reassessment proceedings u/s 147 were validly initiated, as the income had escaped assessment for AY 2013-14.
The Court's Analysis
The tribunal examined Section 197(b) of the IDS-2016, which states:
"For the removal of doubts, it is hereby declared that...(b) where any declaration has been made under section 183 but no tax, surcharge and penalty referred to in section 184 and section 185 has been paid within the time specified under section 187, the undisclosed income shall be chargeable to tax under the Income Tax Act in the previous year in which such declaration is made."
The tribunal observed that the IDS-2016 was introduced as an amnesty scheme to allow taxpayers to declare undisclosed income and pay tax, surcharge, and penalty at concessional rates. However, Section 197(b) explicitly provides that if the tax is not paid within the stipulated time, the undisclosed income shall be chargeable to tax in the previous year in which the declaration is made, not the original assessment year.
The tribunal noted that the AO had incorrectly treated the disclosed amount as undisclosed income for AY 2013-14, despite the assessee having made a declaration under IDS-2016 in FY 2016-17. The tribunal held that the AO's action was not sustainable in law, as the income should have been taxed in the year of declaration (FY 2016-17), not the original assessment year.
The tribunal also took note of the department's own order in the case of Kuldip Singh Sethi & Gagan Goyal, where the AO had accepted that the income disclosed under IDS-2016 but not paid within the stipulated time should be taxed in the year of declaration. This consistency in the department's approach strengthened the assessee's argument.
The Verdict
The tribunal allowed the assessee's appeal and deleted the addition of Rs. 2,03,17,850 made by the AO for AY 2013-14. The tribunal held that the income disclosed under IDS-2016 but not paid within the stipulated time should be chargeable to tax in the previous year in which the declaration was made (FY 2016-17), not the original assessment year (AY 2013-14). The reassessment proceedings initiated u/s 147 for AY 2013-14 were quashed.
What This Means For Similar Cases
Strict Compliance with IDS-2016 Payment Deadlines
Taxpayers must ensure timely payment of tax, surcharge, and penalty under IDS-2016 to avoid the disclosed income being taxed in the year of declaration. Failure to comply with the payment deadline will invalidate the declaration, and the income will be taxed in the year of declaration, not the original assessment year.
Practitioners should advise clients to strictly adhere to the payment timelines under amnesty schemes, as non-compliance can lead to unintended tax consequences in subsequent years.
Jurisdictional Limits of Reassessment Under Section 147
Reassessment proceedings u/s 147 cannot be initiated for an assessment year if the income was disclosed under IDS-2016 but not paid within the stipulated time. The income shall be taxed in the year of declaration, not the original assessment year.
Assessing Officers must exercise caution while reopening assessments for years where income was disclosed under IDS-2016. The tribunal's ruling clarifies that the AO lacks jurisdiction to tax such income in the original assessment year.
Precedential Value of Departmental Orders
Consistency in departmental orders strengthens taxpayers' arguments. The tribunal relied on the department's own order in Kuldip Singh Sethi & Gagan Goyal, where the AO had accepted the same legal position. Practitioners should cite similar departmental orders to bolster their cases.
Taxpayers can challenge reassessment orders if the department has previously accepted a contrary position in similar cases. The tribunal's reliance on the department's own order underscores the importance of consistency in legal interpretations.