The M.P. State Consumer Disputes Redressal Commission has clarified that an inordinate delay in filing a First Information Report (FIR) for vehicle theft can nullify an insurance claim, even where the theft is otherwise genuine. This ruling reinforces the contractual obligation of insured parties to act promptly under policy terms, setting a critical precedent for motor insurance disputes under the Consumer Protection Act.
Background & Facts
The Dispute
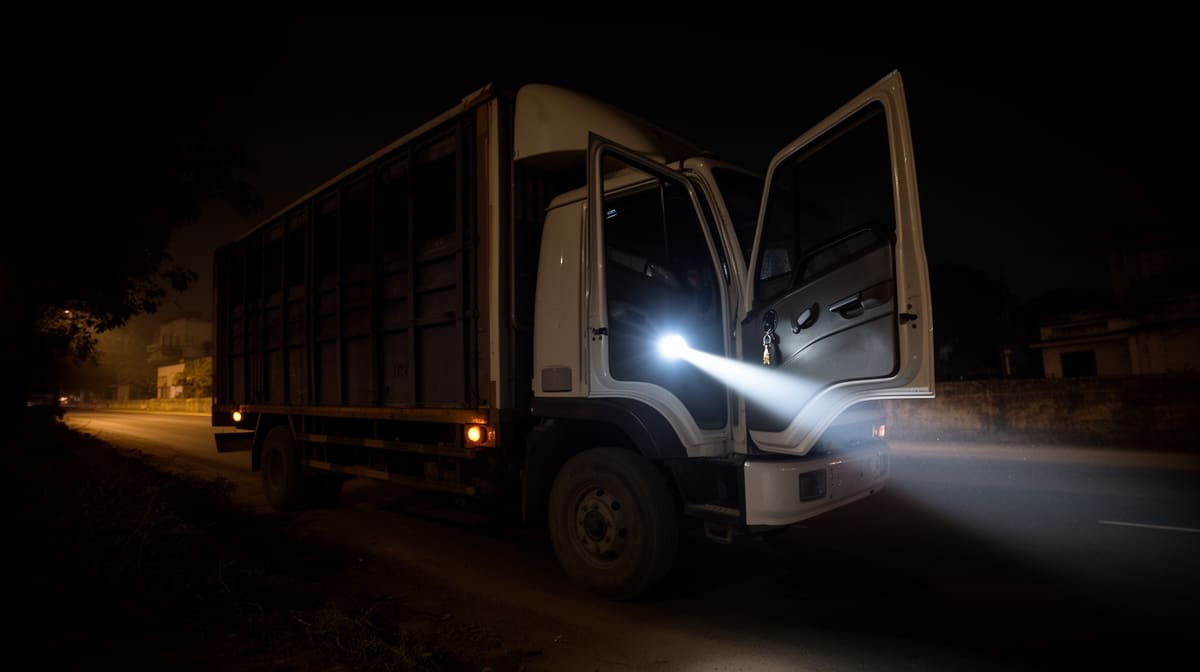
The appellant, Smt. Sunita, owned a truck registered as MP-09 HF 6544, insured with HDFC Ergo General Insurance Company Ltd. for the period 4 February 2013 to 3 February 2014. On 15 February 2013 at 10 P.M., the driver parked the vehicle for dinner. Upon return at midnight, the truck was missing. The driver reported the loss to the appellant’s husband, who lodged a complaint with Lusadia Police Station on 16 February 2013. However, the FIR was only registered on 15 March 2013 - 29 days after the alleged theft. The final report was filed on 20 September 2013. The appellant submitted a claim with all documents, but the insurer repudiated it on 22 July 2013, citing delay in FIR and negligence.
Procedural History
- 15 February 2013: Truck stolen after driver left ignition key inside
- 16 February 2013: Informal complaint lodged with police
- 15 March 2013: FIR registered - 29 days after theft
- 22 July 2013: Insurance Company repudiated claim
- 2013: Complaint filed before District Consumer Commission, Indore
- 6 February 2019: District Commission dismissed complaint, holding delay and negligence invalidated claim
- 2019: Appeal filed before M.P. State Commission
Relief Sought
The appellant sought compensation for the value of the stolen truck, interest, and costs, alleging deficiency in service by the insurer for unjustly denying a legitimate claim.
The Legal Issue
The central question was whether a 29-day delay in filing an FIR for vehicle theft, coupled with the driver leaving the ignition key in the vehicle, constitutes a material breach of policy conditions sufficient to repudiate a claim under the Consumer Protection Act, 1986, even in the absence of fraud.
Arguments Presented
For the Petitioner
Learned counsel for the appellant relied on Ashok Kumar v. New India Assurance Co. Ltd. (2023) to argue that mere negligence, such as leaving keys in the ignition, does not amount to a fundamental breach warranting claim denial. He also cited Amalendu Sahu v. Oriental Insurance Co. Ltd. (2010) to contend that minor policy violations must be addressed on a non-standard basis, not through outright repudiation. He further emphasized that the appellant had informed police on 16 February 2013, and the delay was attributable to police inaction, not the insured. The Commission’s own precedent in Ram Pratap Singh v. New India Assurance affirmed that vehicle owners are consumers under the Act.
For the Respondent
The insurer argued that the policy required immediate intimation to police in case of theft, as per standard terms. The 29-day delay rendered recovery impossible and violated policy condition 1. Counsel cited Tata AIG v. Mahendra Singh (2019) and Bacchu Singh v. National Insurance Co. (2017) to support that delayed FIRs undermine the insurer’s ability to investigate and recover. He also contended that the vehicle was used for commercial purposes, excluding the appellant from the definition of ‘consumer’ under Section 2(1)(d) of the Consumer Protection Act, 1986.
The Court's Analysis
The Commission examined the obligation of immediate intimation to police under insurance policy conditions, referencing binding precedents from the Supreme Court. In Gurshinder Singh v. Shriram General Insurance Co. Ltd. (2020), the Court held that immediate police notification is essential to mobilize investigative machinery for recovery. Similarly, in Jaina Construction Co. v. Oriental Insurance Co. Ltd. (2022), the Court emphasized that the insurer’s role is secondary to police action in theft cases. The Commission found no evidence that the appellant had provided timely notice to police beyond an unverified letter dated 16 March 2013, which was not referenced in the FIR. The FIR itself recorded 15 March 2013 as the date of intimation, confirming the 29-day delay. The Court rejected the argument that police inaction excused the insured’s duty, stating: > "The insured cannot shift the burden of prompt reporting onto the police. The policy condition is clear: immediate intimation is mandatory, not discretionary."
The Commission also noted that while leaving keys in the ignition may be negligent, it was not the primary ground for repudiation. The decisive factor was the failure to comply with the policy’s core procedural requirement. The appellant’s status as a consumer was not decisive, as the claim failed on contractual grounds.
The Verdict
The appeal was dismissed. The Court held that the 29-day delay in filing the FIR constituted a material breach of the insurance policy’s terms, rendering the claim unenforceable. The insurer’s repudiation was upheld as lawful, and no compensation was awarded.
What This Means For Similar Cases
Immediate FIR Reporting Is Non-Negotiable
- Practitioners must advise insured clients that delay in FIR filing - even for legitimate theft - can void claims
- Insurers may rely on this precedent to deny claims where FIR is filed beyond 48 - 72 hours without compelling justification
- Documentation of immediate police notification (e.g., receipt, timestamped complaint) is now essential
Policy Conditions Trump General Consumer Protections
- Consumer status under the Act does not override contractual obligations in insurance policies
- Even if the insured qualifies as a consumer, failure to comply with policy terms (e.g., prompt reporting) defeats the claim
- Advocates must prioritize policy wordings over broad consumer rights arguments in insurance disputes
Negligence Alone Is Not Sufficient for Repudiation - But Delay Is
- Leaving keys in the ignition, while negligent, is insufficient alone to deny a claim
- However, when combined with delayed FIR, it reinforces the insurer’s position
- The focus must shift from fault to procedural compliance: timeliness is the threshold