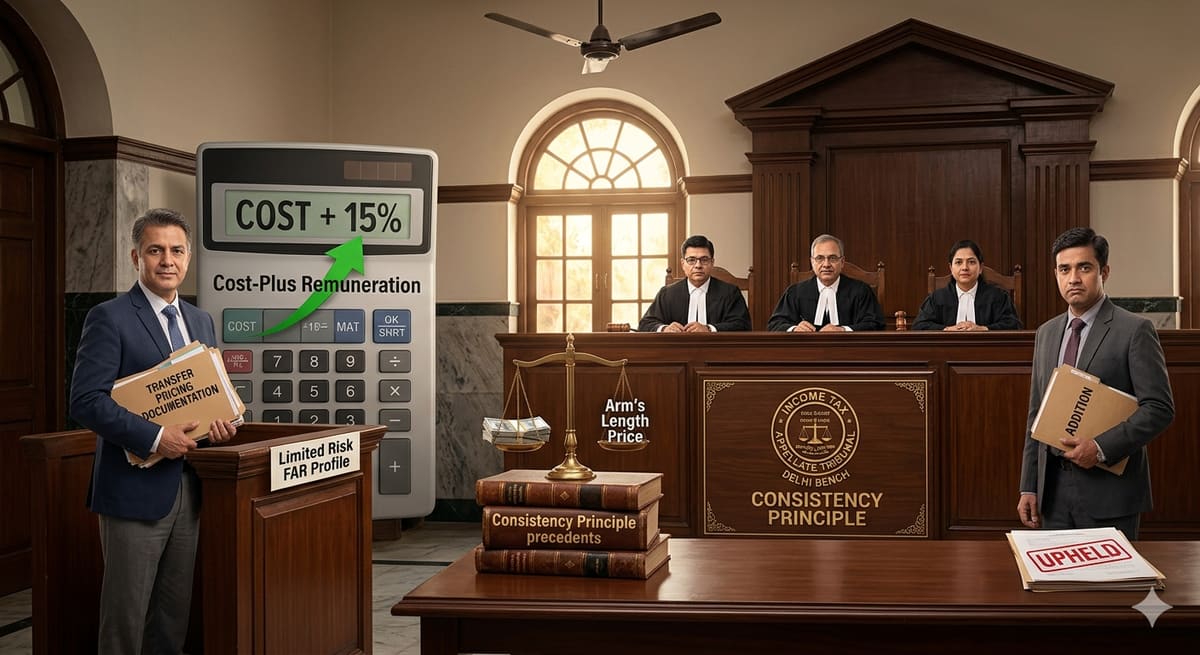
The Delhi Income Tax Appellate Tribunal has set a significant precedent by granting stay on tax recovery where identical transfer pricing issues were previously decided in the assessee’s favor by the Delhi High Court. This ruling reinforces that administrative consistency and judicial precedent must constrain revenue authorities, even in the face of delayed litigation.
Background & Facts
The Dispute
The appellant, Borg Warner Emissions Systems India Private Limited, faced a proposed transfer pricing adjustment of Rs. 16.32 crore for A.Y. 2022-23, arising from payments for royalty, business support services, and purchase of fixed assets to associated enterprises. The Transfer Pricing Officer (TPO) disallowed these payments under Section 92CE of the Income Tax Act, alleging non-arm’s length pricing. The assessee challenged the adjustment before the Dispute Resolution Panel (DRP), which upheld the TPO’s findings.
Procedural History
- 2013-14: The same issue regarding business support services was litigated before the ITAT and subsequently affirmed by the Delhi High Court, which upheld the assessee’s aggregation approach in TP documentation.
- 2022-23: The TPO applied the same methodology to disallow identical payments, despite the binding precedent.
- March 2026: The assessee filed a stay application before ITAT Delhi, seeking complete suspension of recovery pending appeal.
Relief Sought
The assessee sought full stay of recovery, arguing that the legal issue was squarely covered by the Delhi High Court’s prior decision. The revenue opposed, urging partial recovery of 20% of the demand.
The Legal Issue
The central question was whether a binding judicial precedent on identical facts and legal issues in a prior assessment year can compel the tax authority to suspend recovery in a subsequent year, absent any material change in circumstances.
Arguments Presented
For the Appellant
The appellant’s counsel relied on the Delhi High Court’s judgment in the assessee’s own case for A.Y. 2013-14, which had affirmed the legitimacy of the aggregation approach used in TP documentation. She argued that the facts, nature of services, and contractual framework were materially identical. The precedent established a ratio decidendi that directly governed the current dispute, making the TPO’s action legally untenable.
For the Respondent
The revenue contended that the 2013-14 decision was a decade old and could not be mechanically applied due to potential factual variations. It argued that the principle of res judicata does not apply to assessment years and that the TPO was entitled to reassess based on current documentation. It sought partial recovery of 20% to ensure some revenue flow pending appeal.
The Court's Analysis
The Tribunal examined whether the prior High Court ruling constituted a binding authority on the identical issue. It noted that the TPO and DRP had failed to distinguish the facts of A.Y. 2022-23 from those in A.Y. 2013-14. The Court emphasized that judicial precedent binds administrative action, especially when the legal and factual matrix remains unchanged.
"The Hon’ble Delhi High Court has already laid down the legal position on the very issue of business support services... to deny the benefit of such a binding precedent would amount to arbitrary application of tax law."
The Tribunal further held that while the TPO retains discretion to examine documentation, it cannot ignore a higher court’s definitive interpretation of the same transaction type. The Court distinguished between factual disputes and legal interpretations, noting that the latter are settled by precedent. It concluded that the revenue’s insistence on recovery without addressing the binding precedent was contrary to natural justice and the doctrine of consistency in tax administration.
The Verdict
The assessee prevailed. The ITAT Delhi granted stay on 80% of the disputed demand, conditioning recovery of only 20% relating to royalty and fixed asset purchases - issues not covered by the prior judgment. The stay on the balance amount remains in force for 180 days or until disposal of the appeal, whichever is earlier.
What This Means For Similar Cases
Precedent Overrides Administrative Discretion
- Practitioners must cite prior judicial rulings on identical TP issues to challenge TPO adjustments, even if the assessment year is years apart.
- Revenue authorities cannot ignore binding High Court decisions merely because the case is old or the taxpayer is a repeat litigant.
- A consistent factual matrix across years triggers the doctrine of stare decisis in tax administration.
Partial Stay as a Balanced Remedy
- Courts may grant partial stay when some issues remain unaddressed by precedent, allowing limited recovery to balance revenue interests and taxpayer rights.
- Practitioners should segment demands in stay applications: identify which parts are covered by precedent and which are not.
- Deposit of 20% as a condition for stay is now a recognized procedural norm in TP cases with partial precedent coverage.
Documentation Consistency Is a Shield
- Taxpayers must maintain uniform TP documentation across years. Inconsistencies may open the door for revenue to argue factual divergence.
- A well-documented, consistently applied methodology strengthens the claim that a prior precedent applies.
- This case underscores the strategic value of preserving and citing past favorable rulings in current disputes.