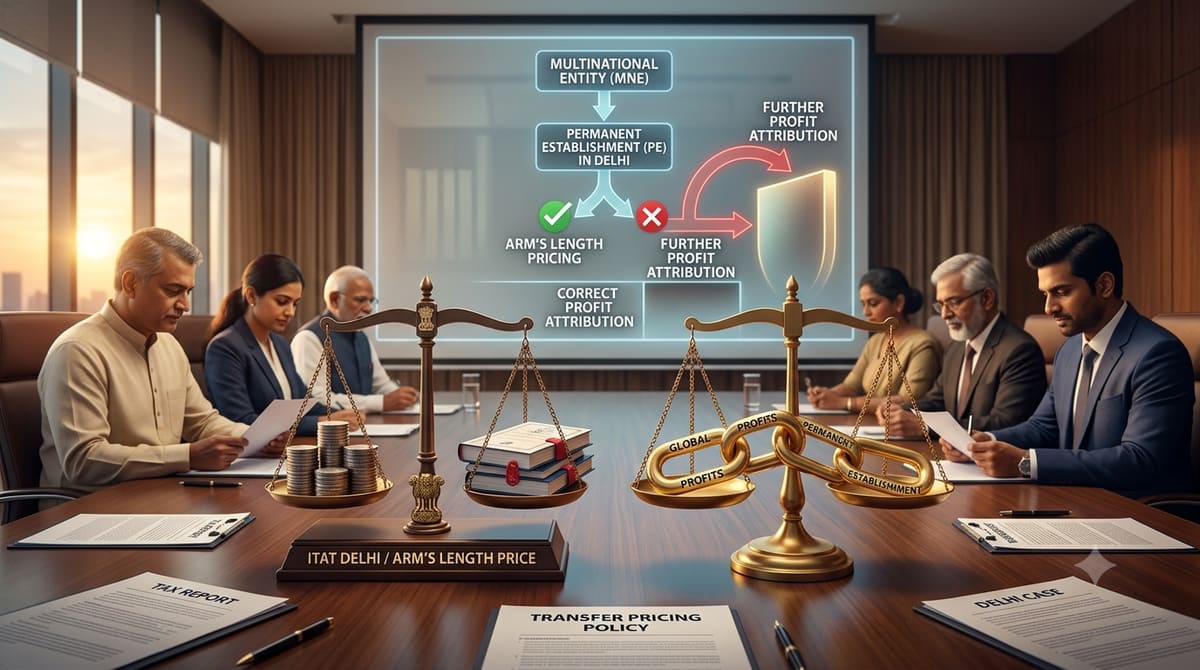
The Income Tax Appellate Tribunal, Delhi, has clarified that the mere transfer of a business on a going concern basis does not automatically render all subsequent expenses incurred by a non-resident company’s Indian branch office as non-deductible. The Tribunal emphasized that expenses aimed at preserving the legal and statutory existence of a Permanent Establishment may still qualify as allowable business expenditures under Section 28(i) of the Income Tax Act, 1961, if they are incidental to the continued existence of the PE.
Background & Facts
The Dispute
The assessee, A.T. Kearney Ltd., a UK-incorporated company, operated a branch office in India which constituted a Permanent Establishment (PE) under Article 5 of the India-UK Double Taxation Avoidance Agreement (DTAA). The branch office provided management consultancy services to clients in India and abroad. On 1 April 2021, the assessee entered into a Business Transfer Agreement (BTA) with its wholly owned Indian subsidiary, A.T. Kearney Consulting (India) Private Limited, transferring the entire business undertaking of the India branch on a going concern basis. However, certain assets were retained by the assessee post-transfer.
Key Facts
- The assessee filed its return for AY 2022-23 on 29.11.2022, declaring income of Rs. 1,27,76,240 and claiming a refund of Rs. 3,30,40,420 against TDS of Rs. 3,84,61,635.
- During the year, the assessee earned interest income of Rs. 3,99,79,892 from income tax refunds.
- The assessee claimed business expenses of Rs. 2,72,03,648 against this interest income, comprising:
- Legal and professional fees: Rs. 25,956,996
- Employee benefits: Rs. 64,43,000
- Finance costs: Rs. 97,000
- Auditor fees: Rs. 3,50,000
- The AO disallowed the entire amount of Rs. 2,72,03,648, holding that the business had ceased on 01.04.2021 and no business was carried on during the previous year.
- The assets retained by the assessee post-transfer included:
- Accrued export incentive: Rs. 1,76,17,373
- Advance tax recoverable: Rs. 2,70,60,9177
- Advance with statutory authorities: Rs. 13,59,540
- Total retained assets: Rs. 34,64,83,048 (over Rs. 34 crores)
- The retained assets were more valuable than the transferred assets (Rs. 2,030.96 lakhs).
- The assessee submitted that the retained assets were necessary to settle pending statutory claims and litigation related to the former branch operations.
Procedural History
- 01.04.2021: Business transfer agreement executed; India branch operations ceased.
- 29.11.2022: Assessee filed return for AY 2022-23.
- 31.05.2023: Notice under Section 143(2) issued for scrutiny.
- 21.03.2024: Draft assessment order issued disallowing expenses of Rs. 2,72,03,648.
- 17.12.2024: Dispute Resolution Panel (DRP) upheld the AO’s disallowance.
- 27.01.2025: Final Assessment Order passed under Section 143(3) r.w.s. 144C(13).
- 2025: Appeal filed before ITAT Delhi (ITA No. 1933/Del/2025).
- 21.04.2026: Hearing conducted.
- 15.07.2026: Judgment pronounced.
The Parties' Positions
For the Assessee
- Argued that the India branch remained a PE under the India-UK DTAA even after business transfer.
- Contended that expenses were incurred to preserve the legal and statutory existence of the PE, including litigation costs, statutory compliance, and maintenance of corporate identity.
- Relied on Pride Foramer S.A. v. CIT (SC), GiriBuildwell Pvt. Ltd., CIT v. Ganga Properties Ltd., and Nakodar Bus Service (P) Ltd. to establish that expenses for preserving business existence are allowable even without active operations.
- Highlighted that the AO failed to examine the nature of expenses and treated all expenses as non-deductible merely due to cessation of business.
- Pointed out that the AO had previously allowed a 15% tax rate on similar interest income under the DTAA in AY 2014-15, indicating inconsistency.
For the Revenue
- Contended that Section 28(i) permits deduction of business expenses only if business was carried on during the previous year.
- Argued that the transfer of business on a going concern basis amounted to complete cessation of business.
- Relied on Goetze (India) Ltd. v. CIT, DCIT v. MDLR Airlines, and Hindustan Chemical Works Ltd. to support disallowance.
- Asserted that interest income from tax refunds was not business income and could not be offset against business expenses.
- Cited the Bangalore ITAT decision in Shanmugam Ravi v. DCIT to uphold the disallowance.
Relief Sought
The assessee sought:
- Allowance of Rs. 2,72,03,648 as deductible business expenses under Section 28(i) and Section 37(1).
- Setting aside of the assessment order dated 27.01.2025.
- Direction to the AO to re-examine the nature and purpose of the expenses claimed.
The Legal Issue
Whether expenses incurred by a non-resident company to maintain the legal and statutory existence of its Permanent Establishment in India, after the transfer of its business operations to a subsidiary, qualify as allowable business expenditures under Section 28(i) of the Income Tax Act, 1961, even in the absence of active business activity during the previous year?
Arguments Presented
For the Appellant/Petitioner
The assessee relied on the Supreme Court’s expansive interpretation of "business" in Pride Foramer S.A. v. CIT, which held that "for the purpose of business" includes acts incidental to the preservation of business, such as payment of statutory dues, protection of assets, and litigation expenses. The assessee argued that retaining assets worth over Rs. 34 crores indicated ongoing obligations tied to the PE. Legal and professional fees were incurred to resolve pending litigation, comply with statutory requirements, and maintain corporate identity - all essential to preserving the PE’s existence. The Tribunal’s own precedent in Tulip Star Hotel Ltd. and NCR Business Park Pvt. Ltd. supported this view. The Revenue’s reliance on Shanmugam Ravi was challenged as inconsistent with binding High Court rulings.
For the Respondent/State
The Revenue contended that Section 28(i) requires actual business activity during the previous year for any expense to be deductible. The transfer of the entire business on a going concern basis constituted cessation, not a temporary lull. Interest income from tax refunds was not business income but a windfall, and Section 29 mandates computation under business head only if business existed. The AO’s reliance on Goetze (India) was justified to reject the alternative claim under DTAA, as no revised return was filed. The DRP’s affirmation was correct, and the Tribunal should uphold the disallowance.
The Court's Analysis
The Tribunal acknowledged the Revenue’s position that Section 28(i) conditions deductibility on the existence of business activity. However, it emphasized that the Supreme Court in Pride Foramer S.A. had explicitly broadened the scope of "business" beyond profit-making activities to include acts incidental to its preservation. The Court observed:
"The expression 'for the purpose of business' is wider in scope than the expression 'for the purpose of earning profits'. Its range is wide: it may take in not only the day-to-day running of a business but also the rationalisation of its administration and modernisation of its machinery; it may include measures for preservation of business and for protection of its assets and property from expropriation, coercive process or assertion of hostile title; it may also comprehend payment of statutory dues and taxes imposed as a pre-condition to commence or for carrying on a business; it may comprehend many other acts incidental to the carrying on of a business."
The Tribunal noted that the assessee retained assets worth Rs. 34.64 crores, significantly exceeding the value of transferred assets. These assets included advance tax recoverables and statutory dues, indicating ongoing legal and financial obligations tied to the PE. The nature of the expenses - primarily legal and professional fees - suggested they were incurred to resolve pending litigation, comply with statutory filings, and maintain corporate standing. The AO and DRP failed to examine the specific purpose of each expense. Instead, they applied a blanket disallowance based solely on the cessation of business operations. This approach ignored the distinction between cessation and dormancy, and the legal obligation to maintain a PE under the DTAA. The Tribunal held that without a detailed breakdown of the expenses and their direct nexus to the PE’s preservation, the disallowance could not be sustained. The matter required a de novo examination by the AO.
The Verdict
The appeal was allowed for statistical purposes. The Tribunal set aside the assessment order dated 27.01.2025 and remanded the matter to the Assessing Officer for de novo assessment. The AO is directed to examine the nature and purpose of each expense claimed under Rs. 2,72,03,648, determine its connection to the preservation of the Permanent Establishment, and allow or disallow expenses on a case-by-case basis. The assessee must provide detailed invoices and supporting documentation for each expense category. The AO shall complete the fresh assessment within 8 weeks from the date of receipt of this order.
What This Means For Similar Cases
Expenses for PE Maintenance Are Not Automatically Disallowed
- Practitioners must now argue that expenses incurred to preserve a Permanent Establishment - such as legal fees for pending litigation, statutory compliance costs, or audit fees - may qualify as business expenditures even after operational cessation.
- The mere fact that business operations have ceased does not negate the existence of a PE under tax treaties.
- Revenue authorities cannot apply blanket disallowances; each expense must be evaluated for its nexus to the PE’s continued legal existence.
Documentation Is Critical for Allowability
- Assessees must maintain and submit itemized records of expenses, clearly linking them to the preservation of statutory rights, litigation, or compliance obligations tied to the PE.
- Invoices, correspondence with authorities, and litigation records should be annexed to substantiate claims.
- Failure to provide granular detail may result in disallowance, even if the legal principle supports allowance.
DTAA Benefits Do Not Override Procedural Requirements
- While the DTAA may offer lower tax rates, claims for such benefits must be made through a revised return under Section 139(5), as held in Goetze (India).
- Assessees cannot rely on past practice or inconsistent treatment by the AO to justify non-compliance with procedural norms.