Topic

ITAT jurisprudence

ITAT jurisprudence refers to the legal principles established by the Income Tax Appellate Tribunal in India while adjudicating appeals against income tax orders.

31 articlesLatest July 2026
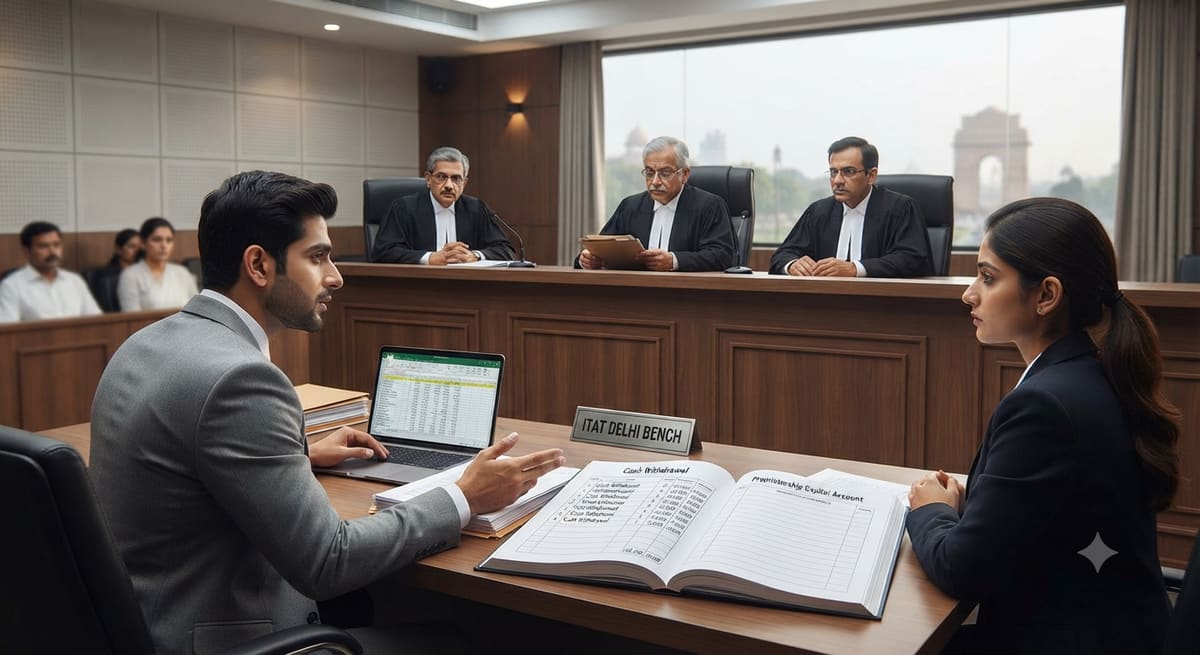
Section 69A IT Act | Cash Withdrawals from Proprietorship Capital Account Within Week of Search Establish Source, Reversing Unexplained Income Addition : ITAT Delhi
Case Law Analysis
|Income Tax Appellate Tribunal

Section 69A IT Act | Cash Withdrawals from Proprietorship Capital Account Within Week of Search Establish Source, Reversing Unexplained Income Addition : ITAT Delhi

ITAT Delhi has ruled that cash withdrawn from a proprietor’s capital account shortly before a search can constitute a credible source for unexplained cash, overturning an addition of Rs. 9 lakh under Section 69A. This sets a critical precedent for small business owners facing scrutiny during income tax searches, affirming that ledger entries alone - even without vouchers - may suffice if consistent with business practice and timing.
Section 37(1) IT Act | Business Expenditure Cannot Be Disallowed Solely Due to Wrong Address or Disregard of KYC Documents: ITAT Delhi
Case Law Analysis
|Income Tax Appellate Tribunal

Section 37(1) IT Act | Business Expenditure Cannot Be Disallowed Solely Due to Wrong Address or Disregard of KYC Documents: ITAT Delhi

The ITAT Delhi ruled that disallowance of business expenditure under Section 37(1) is unlawful when the tax authority fails to verify a vendor at the correct address provided by the assessee and ignores supporting KYC, TDS, and payment records. This sets a critical precedent for taxpayers: documentary compliance must be evaluated on substance, not procedural missteps by revenue officials.

Section 271(1)(c) IT Act | Penalty Inapplicable on Ad-hoc Additions Even for Alleged Bogus Purchases: ITAT Surat
Case Law Analysis
|Income Tax Appellate Tribunal

Section 271(1)(c) IT Act | Penalty Inapplicable on Ad-hoc Additions Even for Alleged Bogus Purchases: ITAT Surat

ITAT Surat holds that penalties under Section 271(1)(c) of the Income Tax Act cannot be levied on ad-hoc or estimated additions, even in cases of alleged bogus purchases. The ruling reinforces that penalty provisions require concrete evidence of concealment, not mere presumptive additions, impacting tax assessments involving disputed transactions.

Natural Justice Mandate | ITAT Pune Quashes Assessment Order for Non-Disclosure of Third-Party Replies Under Section 133(6) IT Act : ITAT Pune
Case Law Analysis
|Income Tax Appellate Tribunal

Natural Justice Mandate | ITAT Pune Quashes Assessment Order for Non-Disclosure of Third-Party Replies Under Section 133(6) IT Act : ITAT Pune

ITAT Pune ruled that income tax assessments are vitiated if the Assessing Officer fails to provide the assessee with third-party replies obtained under Section 133(6) of the Income Tax Act, 1961. The Tribunal emphasized that non-disclosure violates principles of natural justice, setting aside the assessment order and reinforcing procedural fairness in tax proceedings.

Condonation of Delay | Reliance on Unverified RMS-NMS Data Constitutes Sufficient Cause Under Limitation Act: ITAT Pune
Case Law Analysis
|Income Tax Appellate Tribunal

Condonation of Delay | Reliance on Unverified RMS-NMS Data Constitutes Sufficient Cause Under Limitation Act: ITAT Pune

ITAT Pune condoned a 79-day delay in filing an income tax appeal, holding that reliance on unverified data from the RMS-NMS insight portal constitutes sufficient cause under the Limitation Act. This ruling empowers taxpayers who act in good faith based on flawed government-generated alerts, reinforcing procedural fairness over technical non-compliance.

Section 271AAC(1) & 272A(1)(d) NI Act | Penalty Invalid If Underlying Unexplained Income Addition Is Deleted on Appeal : ITAT Jaipur
Case Law Analysis
|Income Tax Appellate Tribunal

Section 271AAC(1) & 272A(1)(d) NI Act | Penalty Invalid If Underlying Unexplained Income Addition Is Deleted on Appeal : ITAT Jaipur

When an appellate authority deletes an addition of unexplained income under Section 69A, penalties imposed under Sections 271AAC(1) and 272A(1)(d) automatically lapse - the penalty cannot stand without its foundational tax liability. This ruling protects cooperative societies and other assessees from punitive measures rooted in nullified assessments, reinforcing that penalties are consequential, not independent, under the Income Tax Act.

Section 147 Income Tax Act | Reassessment Invalid Without Recorded Reasons & Section 151 Approval: ITAT Delhi Reduces Addition from Rs. 35 Lakh to Rs. 3 Lakh
Case Law Analysis
|Income Tax Appellate Tribunal

Section 147 Income Tax Act | Reassessment Invalid Without Recorded Reasons & Section 151 Approval: ITAT Delhi Reduces Addition from Rs. 35 Lakh to Rs. 3 Lakh

The ITAT Delhi set aside a Rs. 35 lakh addition for unexplained cash deposits during demonetization because the reassessment under Section 147 lacked mandatory reasons and failed to secure prior approval under Section 151. Only Rs. 3 lakh was upheld after scrutiny, reinforcing that procedural compliance is non-negotiable in reassessments - a critical safeguard for taxpayers facing post-demonetization scrutiny.

Maintenance Charges from Tenants Classified as Business Income, Not House Property Income | ITAT Delhi
Case Law Analysis
|Income Tax Appellate Tribunal

Maintenance Charges from Tenants Classified as Business Income, Not House Property Income | ITAT Delhi

The ITAT Delhi has ruled that maintenance charges collected by a realty company from tenants constitute business income under the Income Tax Act, not income from house property. This allows the assessee to claim full deductions under Section 37, significantly impacting real estate firms that bundle maintenance fees with rentals and altering how such income is reported and taxed across the sector.

Section 35(1)(ii) Income Tax Act | Retrospective Cancellation of Donee Approval Cannot Void Deductions for Genuine Donations Made During Valid Approval Period : ITAT Kolkata
Case Law Analysis
|Income Tax Appellate Tribunal

Section 35(1)(ii) Income Tax Act | Retrospective Cancellation of Donee Approval Cannot Void Deductions for Genuine Donations Made During Valid Approval Period : ITAT Kolkata

ITAT Kolkata rules that when a donee institution’s approval under Section 35(1)(ii) is cancelled retrospectively, donations made by taxpayers while the approval was active and in good faith remain deductible. This protects legitimate claimants from being penalized for administrative actions taken after the fact, reinforcing legal certainty for corporate philanthropy in scientific research.

Section 68 Income Tax Act | Proportionate Addition Required for Demonetization Cash Deposits, Not Lumpsum Assessment : ITAT Dehradun
Case Law Analysis
|Income Tax Appellate Tribunal

Section 68 Income Tax Act | Proportionate Addition Required for Demonetization Cash Deposits, Not Lumpsum Assessment : ITAT Dehradun

The ITAT Dehradun ruled that cash deposits during demonetization cannot be treated as unexplained income through mechanical lumpsum additions, even when the assessee fails to fully discharge its burden of proof. A reduced addition of Rs. 3 lakh was upheld as fair, setting a precedent for nuanced, fact-sensitive application of Section 68 in unorganized sector businesses.

Section 153C IT Act | DVO Valuation Alone Insufficient for Unexplained Investment Additions Without Incriminating Evidence : ITAT Delhi
|Income Tax Appellate Tribunal

Section 153C IT Act | DVO Valuation Alone Insufficient for Unexplained Investment Additions Without Incriminating Evidence : ITAT Delhi

The ITAT Delhi has ruled that assessments under Section 153C cannot be sustained solely on Departmental Valuation Officer reports when no incriminating material links the assessee to the unexplained investments. This sets a critical precedent for taxpayers facing post-search assessments, requiring the revenue to establish a direct evidentiary connection beyond mere valuation discrepancies.

Section 69C IT Act | Return of Goods Nullifies Fictitious Purchase Claim; Only Retained Stock Subject to 15% Gross Profit Addition : ITAT Delhi
Case Law Analysis
|Income Tax Appellate Tribunal

Section 69C IT Act | Return of Goods Nullifies Fictitious Purchase Claim; Only Retained Stock Subject to 15% Gross Profit Addition : ITAT Delhi

ITAT Delhi ruled that when goods purchased under suspicion of fictitious transactions are fully returned, the purchase claim is extinguished - only the retained stock (Rs.26 lakh) attracts a 15% gross profit addition under Section 69C. This clarifies that genuine returns, even after delay, rebut the presumption of bogus purchases, offering critical relief to traders facing speculative tax assessments.

Section 80P(2)(d) IT Act | Interest Income from Cooperative Banks Qualifies for Deduction by Primary Credit Cooperatives : ITAT Pune
Case Law Analysis
|Income Tax Appellate Tribunal

Section 80P(2)(d) IT Act | Interest Income from Cooperative Banks Qualifies for Deduction by Primary Credit Cooperatives : ITAT Pune

Primary credit cooperative societies are entitled to claim deduction under Section 80P(2)(d) for interest earned from cooperative banks, overturning the tax officer’s disallowance. This ruling clarifies that such income is intrinsic to the cooperative’s core function of providing credit to members, reinforcing tax exemption for rural financial cooperatives operating under state cooperative laws.