Topic

Classification Dispute

A classification dispute in Indian customs and excise law arises when there is disagreement over the correct tariff heading for goods, affecting duty liability.

5 articlesLatest May 2026
Customs Classification | Mere Processing Without Suppression Does Not Trigger Extended Limitation Under Section 28(4) : CESTAT Kolkata
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

Customs Classification | Mere Processing Without Suppression Does Not Trigger Extended Limitation Under Section 28(4) : CESTAT Kolkata

CESTAT Kolkata rules that CRCL reports stating goods 'appear to be processed' are insufficient to prove intentional misdeclaration, and thus cannot justify invoking the extended limitation period under Section 28(4) of the Customs Act. This protects importers from punitive duties based on ambiguous technical assessments, reinforcing that classification disputes are not fraud unless suppression is proven.
GRI 1 & Eo Nomine Rule | Bluetooth Earphones Classifiable as Audio Devices (CTI 8518), Not Data Transmission (CTI 8517) : CESTAT
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

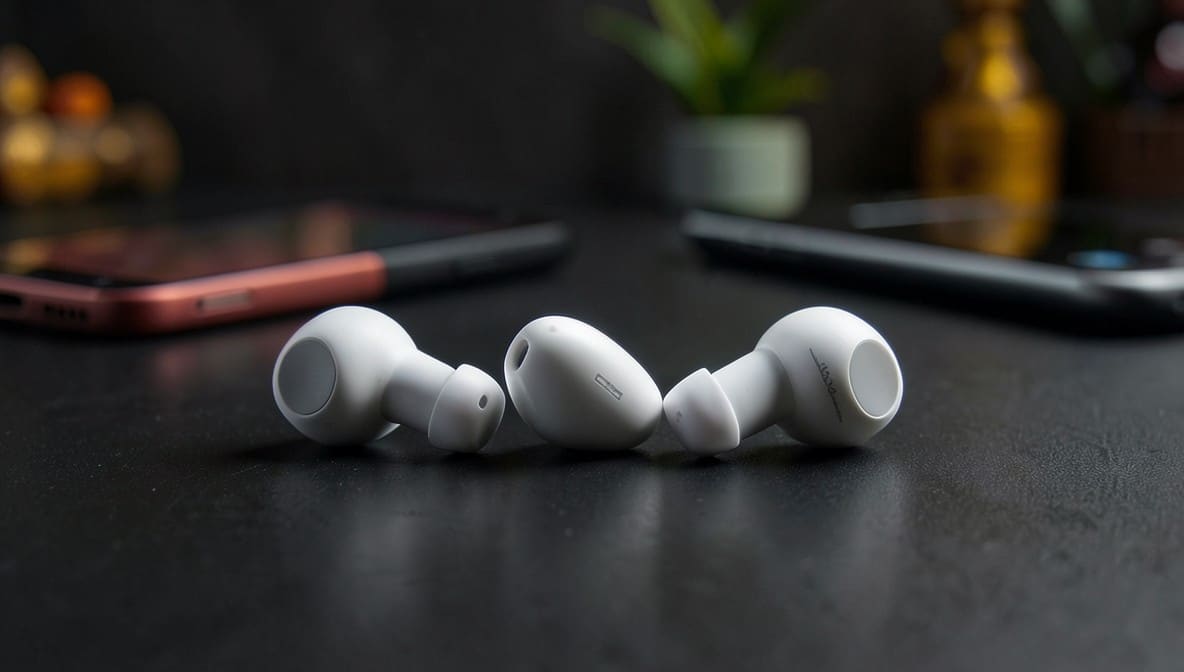
GRI 1 & Eo Nomine Rule | Bluetooth Earphones Classifiable as Audio Devices (CTI 8518), Not Data Transmission (CTI 8517) : CESTAT

CESTAT rules that Bluetooth earphones' primary function is sound reproduction, not data transmission, classifying them under CTI 8518 (15% duty) instead of CTI 8517 (10% duty). The decision clarifies classification disputes under General Interpretative Rule 1 and the eo nomine provision, impacting importers of wireless audio devices.

Section 11A Central Excise Act | Extended Limitation Inapplicable Without Proof of Suppression in Bona Fide Classification Disputes : CESTAT Chandigarh
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

Section 11A Central Excise Act | Extended Limitation Inapplicable Without Proof of Suppression in Bona Fide Classification Disputes : CESTAT Chandigarh

CESTAT Chandigarh rules that extended limitation under Section 11A of the Central Excise Act cannot be invoked merely for classification disputes unless deliberate suppression or intent to evade duty is proven. The ruling shields manufacturers from retrospective demands where classification errors stem from bona fide belief, reinforcing the need for clear evidence of fraudulent intent in excise proceedings.

Chapter 30 vs Chapter 33 | CESTAT Classifies Ayurvedic P&P Medicines with Excipients as Medicaments, Not Cosmetics : CESTAT
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

Chapter 30 vs Chapter 33 | CESTAT Classifies Ayurvedic P&P Medicines with Excipients as Medicaments, Not Cosmetics : CESTAT

CESTAT rules that Ayurvedic Patent & Proprietary medicines containing permitted excipients must be classified under Chapter 30 (medicaments) of the Central Excise Tariff, not Chapter 33 (cosmetics). The decision sets a precedent for manufacturers, ensuring duty benefits and regulatory clarity for similar products.