
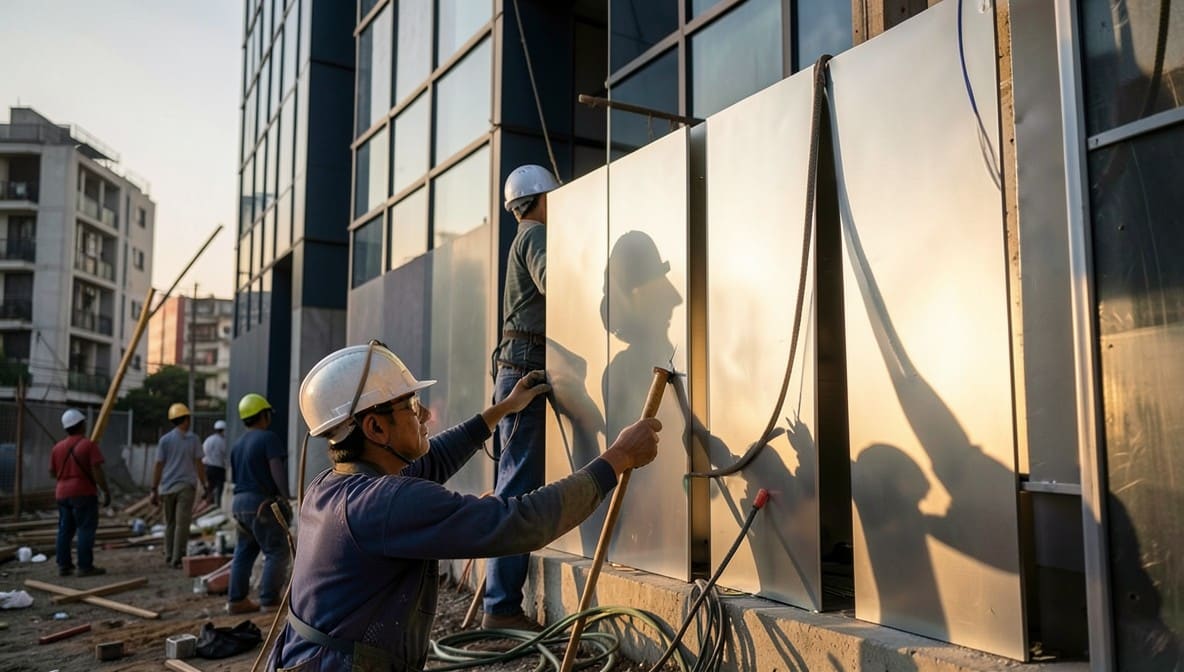
The Supreme Court has clarified that the mere cutting, grooving, and routing of pre-coated Aluminum Composite Panels (ACPs) to fit building façades does not amount to "manufacture" under the Central Excise Act, 1944, and further held that disputes on excisability of goods fall exclusively within the appellate jurisdiction of the Supreme Court under Section 35L, barring High Courts from adjudicating such matters.
Background & Facts
The Dispute
The appellant, M/s Alupro Building Systems Pvt. Ltd., is a construction contractor that installs Aluminum Composite Panels (ACPs) on building exteriors. The ACPs are imported pre-coated composite products consisting of a polyethylene core sandwiched between two aluminum sheets. The appellant purchases these panels in standard sizes and performs on-site modifications to suit architectural designs.
Key Facts
- The ACPs imported by the appellant are classified under Customs Tariff Heads 7606/7610 and customs duties are paid at the time of import.
- The appellant undertakes two primary processes: (i) cutting the ACPs into required rectangular or square dimensions, and (ii) routing/grooving the back surface to enable mechanical fixing.
- These modified panels are then fixed to structural frames using angles, clamps, and fasteners, with gaps between panels sealed using weather-resistant sealant.
- Prior to April 2002, the appellant paid excise duty on these cutting and grooving activities.
- From April 2002 onwards, the appellant discontinued payment, believing the process did not constitute "manufacture" under Section 2(f) of the Central Excise Act, 1944.
- On 14.09.2004, the Revenue issued a Show Cause Notice (SCN) demanding excise duty of Rs. 21,46,437/- for the period April 2002 to December 2003, along with interest and penalty.
- The appellant paid the demanded amount under protest and challenged the SCN.
- The Additional Commissioner of Central Excise, by Order dated 21.06.2005, confirmed the demand.
- The Commissioner (Appeals), by Order dated 28.10.2005, upheld the duty demand but set aside penalty and interest.
- The Customs, Excise and Service Tax Appellate Tribunal (CESTAT), by Final Order dated 27.06.2006, allowed the appellant’s appeal, holding that no new product emerged and the Revenue failed to prove marketability.
- The High Court of Karnataka, by impugned judgment dated 01.04.2010, reversed CESTAT’s order, holding that cutting and grooving amounted to manufacture.
Procedural History
- April 2002: Appellant discontinues payment of excise duty on cutting and grooving of ACPs.
- 14.09.2004: Show Cause Notice issued by Revenue demanding duty of Rs. 21,46,437/-.
- 21.06.2005: Additional Commissioner confirms duty demand.
- 28.10.2005: Commissioner (Appeals) upholds duty demand but cancels penalty and interest.
- 27.06.2006: CESTAT allows appeal, holding no manufacture and Revenue failed to prove marketability.
- 01.04.2010: High Court of Karnataka allows Revenue’s appeal under Section 35G, holding that cutting and grooving constitutes manufacture.
- 27.05.2026: Supreme Court allows appeal, setting aside High Court’s judgment.
Relief Sought
The appellant sought quashing of the High Court’s judgment dated 01.04.2010, restoration of CESTAT’s order dated 27.06.2006, and a declaration that the cutting and grooving of ACPs does not constitute manufacture under Section 2(f) of the Central Excise Act, 1944.
The Legal Issue
The central questions were: (1) Whether the High Court had jurisdiction under Section 35G to adjudicate a dispute on the excisability of goods, and (2) Whether the process of cutting, grooving, and routing of imported ACPs amounts to "manufacture" under Section 2(f) of the Central Excise Act, 1944.
Arguments Presented
For the Appellant
The appellant argued that the process of cutting and grooving ACPs does not result in a new product with a distinct name, character, or use. The essential identity of the ACP remains unchanged; only its dimensions and shape are modified for installation purposes. Reliance was placed on Union of India v. J.G. Glass Industries Ltd. and Servo-Med Industries (P) Ltd. v. CCE to assert that both transformation and marketability must be established for manufacture. It was further contended that the Revenue failed to discharge its burden of proving marketability of the modified panels as distinct goods. The appellant also argued that the High Court lacked jurisdiction under Section 35G because the dispute pertained to excisability, which falls under Section 35L(1)(b).
For the Respondent
The Revenue contended that the cutting, grooving, and routing processes result in an irreversible change to the ACPs, altering their end-use from generic panels to customized building façade components. It relied on Quippo Energy Ltd. v. CCE to argue that the transformation, even if minor, coupled with the specific adaptation for construction use, satisfies the test of manufacture. The Revenue further submitted that the High Court was entitled to examine the substantial question of law regarding the nature of the activity.
The Court's Analysis
The Court undertook a two-pronged analysis: first on jurisdictional competence under Sections 35G and 35L, and second on the definition of "manufacture" under Section 2(f).
On jurisdiction, the Court held that Section 35G explicitly bars appeals to the High Court on any order relating to "the determination of any question having a relation to the rate of duty of excise or to the value of goods for purposes of assessment." The Court emphasized that the word "any" and the phrase "among other things" indicate a broad exclusion. Crucially, the Court held that the question of excisability is not merely related to the rate of duty - it is a prerequisite to it. As the Court observed:
"The decision on excisability of goods is a precursor to the determination of any question having a relation to the rate of excise duty or to the value of goods for the purpose of assessment. To hold otherwise would be to sever what is inherently a continuous chain of fiscal adjudication."
The Court further held that the 2014 amendment to Section 35L(2), which explicitly includes "determination of taxability or excisability of goods" within the scope of "rate of duty," is clarificatory and retrospective. The amendment merely made explicit what was always implicit in the statutory scheme. The Court relied on Reliance Media Works Ltd. and DLF Golf Resort Ltd. to affirm that such clarificatory amendments operate from the date of the original enactment.
On the definition of manufacture, the Court applied the two-fold test established in J.G. Glass Industries and refined in Servo-Med: (1) whether a distinct product with a new name, character, or use emerges, and (2) whether the resulting product is marketable as such. The Court found that neither limb was satisfied.
Regarding transformation, the Court held that cutting and grooving are merely preparatory steps to facilitate installation. The ACP retains its fundamental identity: aluminum-polyethylene composite. The Court drew parallels with Bharat Forge, S.R. Tissues, and Aman Marble Industries, where cutting, slitting, or polishing did not constitute manufacture because the essential character remained unchanged.
On marketability, the Court reiterated that the burden lies squarely on the Revenue. The Revenue produced no evidence - no trade records, no invoices, no market surveys - to show that the cut and grooved ACPs were bought or sold as distinct commercial goods. The Court cited Union Carbide India Ltd. and Cipla Ltd. to emphasize that mere assertion or past payment of duty cannot substitute for objective proof of marketability.
"The mere fact that goods are adapted for a specific use does not transform them into a new commercial product. The market must recognize the modified item as something distinct from the original."
The Court concluded that the High Court erred in both jurisdiction and substantive law.
The Verdict
The appeal was allowed. The Supreme Court set aside the High Court’s judgment dated 01.04.2010 and restored CESTAT’s order dated 27.06.2006. The demand for excise duty of Rs. 21,46,437/-, along with interest and penalty, was quashed. All pending applications were disposed of.
What This Means For Similar Cases
Excisability Disputes Are Exclusively for the Supreme Court
- Practitioners must now file appeals on excisability, taxability, or classification disputes directly before the Supreme Court under Section 35L(1)(b), not the High Court.
- Any High Court order on such matters, even if framed as a "substantial question of law," is void for want of jurisdiction.
- Litigants should challenge jurisdiction at the earliest stage to avoid procedural waste.
Transformation Must Be Substantive, Not Superficial
- Cutting, shaping, drilling, or routing goods to fit a specific application does not constitute manufacture if the core identity remains unchanged.
- The test is not physical alteration but commercial transformation: does the product acquire a new name, character, or use in the market?
- Precedents like S.R. Tissues and Aman Marble Industries now stand reaffirmed as controlling authority.
Burden of Proving Marketability Rests on the Revenue
- The Revenue must produce concrete evidence - market surveys, trade publications, purchase orders, or invoices - to prove that the modified product is recognized and traded as a distinct commodity.
- Mere existence in a tariff entry or past payment of duty is insufficient.
- Courts will not infer marketability from hypothetical demand or technical feasibility.
Marketability Requires Commercial Recognition, Not Just Utility
- A product may be functionally useful but not marketable if it lacks commercial identity.
- The test is not whether the product can be sold, but whether it is known, bought, and sold as a distinct article in the market.
- Custom-made components for a single buyer, as in Sonic Electrochem, are not marketable.
Jurisdictional Clarity Prevents Forum Shopping
- The Supreme Court’s clarification eliminates ambiguity in appellate routes under the Central Excise Act.
- Tax authorities can no longer bypass the Supreme Court by framing excisability disputes as "substantial questions of law."
- This ensures uniformity in interpretation across states and prevents conflicting High Court rulings.
Practical Takeaway for Practitioners
- For manufacturers: If your process involves only sizing, cutting, or fitting imported components, you may have a strong defense against excise demands.
- For tax authorities: Before issuing SCN, conduct a marketability assessment with verifiable data - not assumptions.
- For litigants: Always raise jurisdictional objections under Section 35G at the first opportunity.





