The Customs, Excise and Service Tax Appellate Tribunal (CESTAT), Mumbai, has delivered a significant ruling on the imposition of redemption fines and penalties under the Customs Act, 1962. The Tribunal held that marginal excess in surface area of imported marble slabs, arising from differing measurement methodologies, does not constitute deliberate misdeclaration or suppression of facts. Consequently, the imposition of redemption fines and penalties under Sections 111(l), 111(m), and 114A of the Act was set aside, reinforcing that penal consequences require an element of mens rea or deliberate defiance of law.
Background & Facts
The Dispute
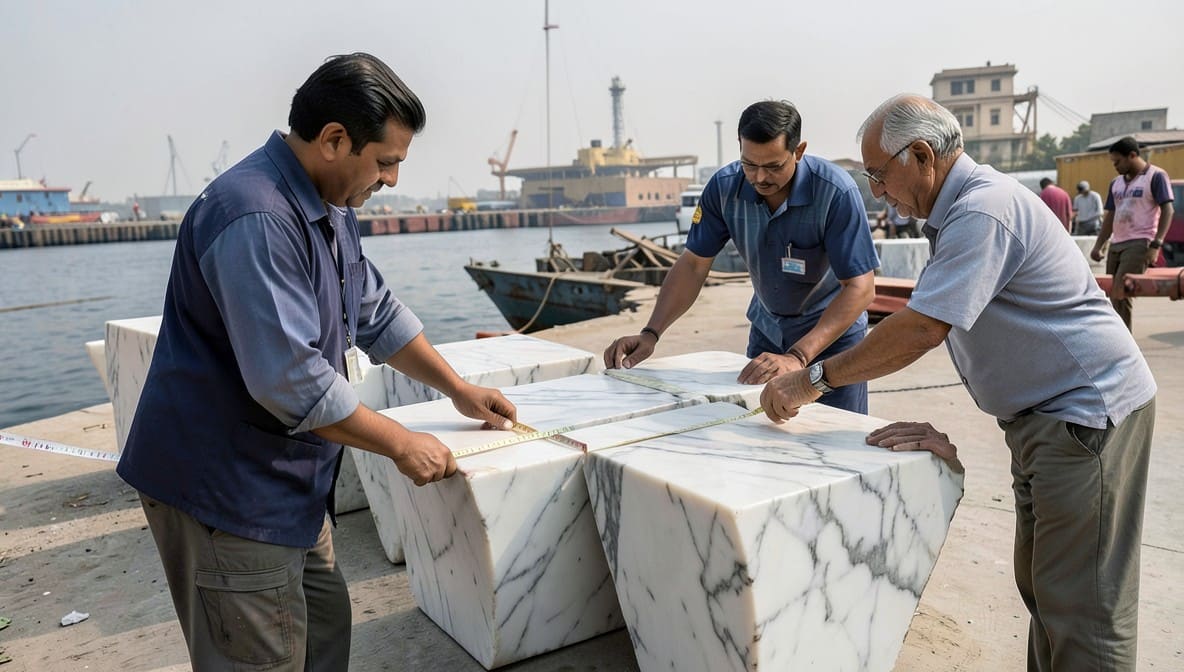
The appellant, Bajrang Marble Co., imported two consignments of 'Honed Polished Marble Slabs' vide Bills of Entry No. 3552711 and 3552720, both dated 11.12.2015. The consignments were examined by the Preventive Unit of Customs, which adopted a measurement methodology of taking the maximum length and maximum breadth of each slab. This method reported an excess surface area of around 13%, marginally exceeding the 10% tolerance limit prescribed by Standing Order No. 22/2010 dated 16.04.2010.
Key Facts
- The appellant imported marble slabs of varying thicknesses (20MM-2MM and 20MM-1MM) on 11.12.2015
- 100% physical examination was conducted under Panchnama dated 18.12.2015 and 21.12.2015
- The Customs authorities measured the slabs by taking the maximum length and maximum breadth, resulting in an excess surface area of 13%
- The Standing Order No. 22/2010 permits a 10% tolerance limit for measurement variations without imposition of fine or penalty
- The appellant sent a letter dated 05.01.2016 accepting the measurement report and agreeing to pay differential duty
- A subsequent letter dated 26.02.2016 sought to resile from the earlier acceptance, claiming it was made to avoid delay
- The request for re-measurement by a trade expert was rejected by the lower authority
Procedural History
- 12.04.2016: Order-in-Original No. 2/2015-16 AM(l) imposed a redemption fine of Rs. 25 lakhs and penalty of Rs. 12.50 lakhs, along with differential duty of Rs. 4,90,570
- 18.02.2016: Order-in-Original No. 208/2015-16 AM(l) imposed similar penalties
- 12.05.2016: Commissioner of Customs (Appeals-II) partially modified the orders, reducing the redemption fine and penalties to:
- Rs. 2 lakhs and Rs. 1 lakh (for the first appeal)
- Rs. 1.5 lakhs and Rs. 50,000 (for the second appeal)
- Present appeals filed before CESTAT Mumbai challenging the confirmation of fine and penalty
Relief Sought
The appellant sought setting aside of the redemption fine and penalty imposed under Sections 111(l), 111(m), and 114A of the Customs Act, 1962, contending that the excess surface area was due to differing measurement methodologies and not deliberate misdeclaration.
The Legal Issue
The central question before the Tribunal was whether the imposition of redemption fine under Sections 111(l) and 111(m) and penalty under Section 114A of the Customs Act, 1962 is legally sustainable where:
- The excess surface area arises from differing methods of measurement of non-uniform marble slabs
- The appellant is not contesting the differential customs duty
- There is no evidence of fraudulent intent or deliberate misdeclaration
Arguments Presented
For the Appellant
- The appellant was ready and willing to pay the differential duty from the inception
- The contest was limited to the levy of redemption fine and penalty, which was unwarranted in the absence of fraudulent intent or deliberate misdeclaration
- The marble slabs were not uniform rectangles or squares, and some had suffered breakage
- The variance in measurement was an inevitable consequence of the method adopted by Customs (measuring maximum length by maximum breadth)
- The marginal variation of around 3% (after deducting the 10% tolerance limit) was due to different methods of measurement
- The Standing Order No. 22/2010 itself recognized that variations in measurement are inherent in the marble industry
- The excess quantity did not amount to misdeclaration as it was not deliberate
For the Respondent
- The excess of 13% beyond the declared surface area exceeded the 10% tolerance limit under Standing Order No. 22/2010
- The appellant’s letter dated 05.01.2016 constituted an unqualified acceptance of the excess quantity
- The imposition of fine and penalty was justified as the excess exceeded the prescribed tolerance
The Court's Analysis
The Tribunal meticulously examined the facts and legal provisions to determine whether the imposition of redemption fine and penalty was sustainable. The key observations were:
-
Measurement Methodology and Tolerance Limit:
"The Panchnama-based measurement was carried out by taking the maximum length and maximum breadth of each slab, a methodology that necessarily overstates the actual surface area of non-rectangular or broken slabs by treating them as perfect rectangles."
The Tribunal noted that the Standing Order No. 22/2010, which grants a 10% tolerance limit for measurement variations, is a formal recognition by the Department that measurement variations in marble slabs are inherent and unavoidable. While the excess in this case was 13%, marginally exceeding the threshold, the Tribunal held that this marginal overage was reasonably attributable to differing measurement methodologies rather than deliberate misdeclaration.
-
Absence of Fraudulent Intent: The Tribunal emphasized that Sections 111(l), 111(m), and 114A of the Customs Act, 1962 are not strict liability provisions. The invocation of these provisions requires a finding of:
- Deliberate misdeclaration
- Wilful misstatement
- Suppression of facts with intent to evade customs duty
The Tribunal observed:
"Penal consequence like confiscation generally require deliberate defiance of law, conscious disregard of obligation or dishonest conduct, which we are unable to find in the facts of this case."
The Tribunal found no evidence of the appellant having made a knowingly false declaration or attempting to smuggle or evade duty. The appellant’s readiness to pay differential duty from the inception further supported the absence of fraudulent intent.
-
Contemporaneous Protest Requirement: The Tribunal scrutinized the appellant’s letter dated 05.01.2016, wherein the appellant unequivocally accepted the measurement report and agreed to pay differential duty. The Tribunal held:
"In law, a protest must be contemporaneous and explicit; it cannot be introduced by way of a subsequent communication after the fact."
The subsequent letter dated 26.02.2016, purporting to qualify the earlier acceptance, was deemed a post hoc attempt to resile from the earlier acceptance. Consequently, the Tribunal upheld the rejection of the request for re-measurement.
-
Legal Sustainability of Redemption Fine and Penalty: The Tribunal concluded that the ingredients of Sections 111(l), 111(m), and 114A were not satisfied in this case. The excess surface area was not a result of deliberate misdeclaration but rather a consequence of measurement methodology. Since the appellant had accepted the differential duty liability from the inception, no further penal liability arose.
The Verdict
The Tribunal allowed the appeals and set aside the impugned Orders-in-Appeal dated 12.05.2016, which had confirmed the redemption fine and penalty (even in reduced form). The Tribunal held that the imposition of redemption fine and penalty under Sections 111(l), 111(m), and 114A of the Customs Act, 1962 was not legally sustainable in the facts of the case.
What This Means For Similar Cases
Mens Rea Is Essential for Penal Consequences
- Sections 111(l), 111(m), and 114A of the Customs Act, 1962 are not strict liability provisions. The imposition of redemption fine and penalty requires proof of:
- Deliberate misdeclaration
- Wilful misstatement
- Suppression of facts with intent to evade duty
- Marginal excess due to differing measurement methodologies does not constitute deliberate misdeclaration
- Practitioners must emphasize the absence of fraudulent intent and highlight the appellant’s willingness to pay differential duty to avoid penal consequences
Measurement Methodology Matters
- Standing Orders or administrative instructions prescribing tolerance limits (e.g., Standing Order No. 22/2010) recognize inherent measurement variations in certain commodities
- Excess beyond tolerance limits must be attributable to deliberate misdeclaration and not merely differing measurement methods
- Non-uniform or broken slabs measured as perfect rectangles overstate actual surface area, and this must be factored into legal arguments
Contemporaneous Protest Is Crucial
- Acceptance of measurement reports or duty liability must be explicitly made under protest if the appellant intends to contest the findings later
- Subsequent communications purporting to qualify earlier acceptance will not suffice as a valid protest
- Trade experts or alternative measurement methods should be requested contemporaneously to avoid rejection by authorities