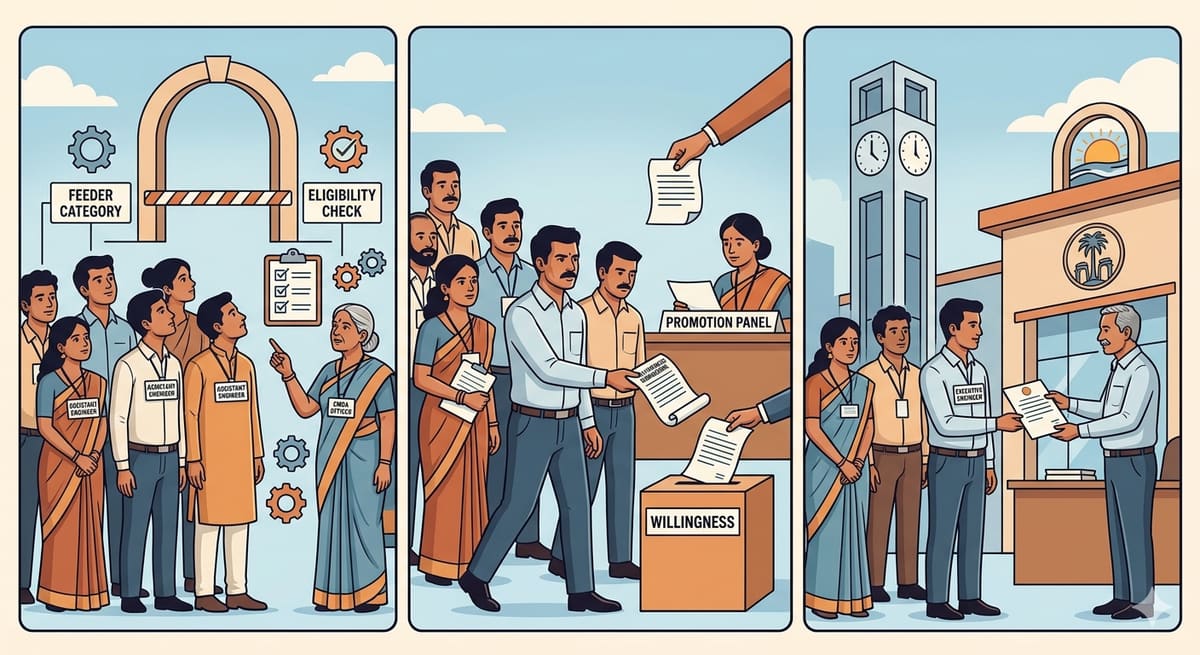
The Madras High Court clarified that maternity leave cannot be treated as a break in service for the purpose of mandatory two-year Firka Revenue Inspector requirement, and that denial of promotion on grounds of unfulfilled service when the employee was not posted in that post after maternity leave is unsustainable.
Background & Facts
The Dispute
The writ petitioner, S.Menaka, a directly recruited Revenue Assistant, challenged two orders: (i) G.O. (1D) No.490 dated July 31, 2025 rejecting a proposal to relax the mandatory two-year Firka Revenue Inspector service requirement, and (ii) Roc.No.2563392/2024/A1 dated April 22, 2025 promoting her juniors to Tahsildar overlooking her seniority. She sought quashing of these orders and direction to grant her promotion to Tahsildar with consequential monetary benefits.
Key Facts
- The writ petitioner joined service on August 14, 2008 as a Revenue Assistant via direct recruitment.
- She completed foundational training at Civil Service Training Institute, Bhavanisagar.
- Her first stint as Firka Revenue Inspector was from January 04, 2012 to March 04, 2012.
- She served as Firka Revenue Inspector, Neikkarapatti Firka, Palani Taluk from March 12, 2012 to November 04, 2013, completing 1 year 8 months and 17 days.
- She applied for maternity leave from November 05, 2013 to May 04, 2014.
- Upon rejoining on May 05, 2014, she was posted as Special Revenue Inspector (Land Acquisition) by the District Collector (third appellant) without her request.
- She was transferred to Collector Office, Dindigul District as Assistant on October 30, 2014.
- Promoted as Deputy Tahsildar vide Order dated September 29, 2015.
- Completed Police Training in 2015 and Special Judicial Magistrate Training in 2017.
- On March 05, 2024, the third appellant sent a proposal to the second appellant seeking relaxation of the mandatory two-year Firka Revenue Inspector service by adjusting her Special Revenue Inspector (Land Acquisition) service.
- The second appellant rejected the proposal on July 31, 2025 (G.O. (1D) No.490).
- She filed W.P. (MD) No.24070 of 2025 challenging the rejection order.
- She also filed W.P. (MD) No.14279 of 2025 challenging the promotion order Roc.No.2563392/2024/A1 dated April 22, 2025.
- The learned Single Judge allowed both writ petitions by order dated January 23, 2026, directing the appellants to include her name in the 2024 panel list per seniority and grant promotion to Tahsildar from the date her immediate juniors were promoted, with all consequential monetary and service benefits within twelve weeks.
- Aggrieved, the appellants filed these Writ Appeals (W.A. (MD) Nos.1385 & 1386 of 2026).
Procedural History
- 14.08.2008: Joined service as Revenue Assistant.
- 04.01.2012 - 04.03.2012: First stint as Firka Revenue Inspector.
- 12.03.2012 - 04.11.2013: Second stint as Firka Revenue Inspector (1 year 8 months 17 days).
- 05.11.2013 - 04.05.2014: Maternity leave.
- 05.05.2014: Rejoined duty; posted as Special Revenue Inspector (Land Acquisition).
- 30.10.2014: Transferred as Assistant, Collector Office, Dindigul.
- 29.09.2015: Promoted as Deputy Tahsildar.
- 2015: Completed Police Training.
- 2017: Completed Special Judicial Magistrate Training.
- 05.03.2024: Third appellant's proposal for relaxation of service requirement.
- 31.07.2025: Second appellant rejected proposal (G.O. (1D) No.490).
- 22.04.2025: Promotion order Roc.No.2563392/2024/A1 passed.
- 23.01.2026: Learned Single Judge allowed writ petitions, directed promotion within twelve weeks.
- 03.09.2026: Reserved for judgment.
- 29.09.2026: Judgment delivered.
Parties' Positions
For the Appellants (Government officials): Contended that the writ petitioner had not completed the mandatory two-year service as Firka Revenue Inspector, a prerequisite for promotion to Deputy Tahsildar, and that the rejection of the relaxation proposal and promotion of juniors were valid exercises of administrative discretion.
For the Respondent (Writ petitioner): Argued that maternity leave must be counted towards Firka Revenue Inspector service, that the department failed to post her in that post after maternity leave thereby preventing completion of the requirement, and that denial of promotion on grounds of a shortfall caused by the department's own action was violative of service rules and maternity rights.
Relief Sought
The writ petitioner sought quashing of G.O. (1D) No.490 dated July 31, 2025 and Roc.No.2563392/2024/A1 dated April 22, 2025, direction to include her name in the 2024 panel list per seniority, grant promotion to Tahsildar from the date her immediate juniors were promoted, with all consequential monetary and service benefits.
The Legal Issue
The core question was whether maternity leave period can be counted towards the mandatory two-year service as Firka Revenue Inspector required for promotion to Deputy Tahsildar under Rule 7(a) of the Tamil Nadu Revenue Subordinate Service Rules, and whether denial of promotion on grounds of unfulfilled service when the employee was not posted in the requisite post after maternity leave is sustainable.
Arguments Presented
For the Appellants
The appellants relied on the plain language of Rule 7(a) read with Annexure III, insisting that two years of actual service as Firka Revenue Inspector is a condition precedent for promotion to Deputy Tahsildar. They argued that the writ petitioner’s service fell short by 3 months and 13 days, that the proposal to adjust her Special Revenue Inspector (Land Acquisition) service was correctly rejected as it did not constitute Firka Revenue Inspector service, and that the promotion of juniors was based on seniority and not arbitrary.
For the Respondent
The respondent cited the Supreme Court’s holdings in Umadevi v. State of Tamil Nadu (2025) 8 SCC 263 and Municipal Corporation of Delhi v. Female Workers (Muster Roll) (2000) 3 SCC 224 to assert that maternity leave is a fundamental right and must be treated as service for seniority and benefits. She contended that the department’s transfer to Special Revenue Inspector (Land Acquisition) after maternity leave prevented her from completing the Firka Revenue Inspector tenure, and that the government’s own Circular No.4/2010 dated November 16, 2010 obliges district administrations to post candidates in Firka Revenue Inspector posts to enable completion of the mandatory period.
The Court's Analysis
The Court examined Rule 38(b)(ii) of the Tamil Nadu Ministerial Service Rules, which makes Annexure IX applicable to directly recruited Revenue Assistants, and Annexure III of the Tamil Nadu Revenue Subordinate Service Rules under Rule 7(a). It noted that the writ petitioner had served 1 year 8 months and 17 days as Firka Revenue Inspector, with a shortfall of 3 months and 13 days due to her not being posted in that post after maternity leave. The Court held that maternity leave, being a paid leave under the Maternity Benefit Act, 1961, constitutes service for seniority and other benefits, citing the Supreme Court’s emphasis on facilitating women’s continued participation in the workplace. It further observed that the purpose of the mandatory service requirement is to ensure adequate knowledge, skills, and experience, but where the employee is denied the opportunity to serve in the requisite post through no fault of her own, the condition ought to be relaxed. The Court relied on the government’s Circular No.4/2010, which advises district administrations to post candidates as Firka Revenue Inspectors to enable them to complete the mandatory period, and found that the appellants’ failure to do so rendered their rejection of the relaxation proposal unsustainable. Consequently, the Court affirmed the Single Judge’s view that the writ petitioner’s promotion could not be denied for want of service qualification when she was not given the chance to acquire it.
"This Court holds that maternity leave cannot be cited to the detriment of the mother's professional growth or promotion in any manner."
The Verdict
The Writ Appeals are dismissed as devoid of merits. The Court upheld the Single Judge’s order dated January 23, 2026, directing the appellants to promote the writ petitioner to the Tahsildar cadre from the date her immediate juniors were given promotion, with all consequential monetary and service benefits. Twelve weeks' time from the judgment date (29 September 2026) is granted for compliance. No order as to costs was passed.
What This Means For Similar Cases
Maternity Leave Counts as Service
Maternity leave, being paid leave under the Maternity Benefit Act, 1961, must be treated as service for seniority, promotion, and other benefits, and cannot be used to disadvantage a female employee’s career progression.
Department Must Provide Opportunity to Complete Mandatory Service
When a government employee is not posted in the requisite post after maternity leave, the administration cannot rely on a shortfall in mandatory service to deny promotion; it must either relax the condition or provide an opportunity to complete the required tenure.
Reliance on Administrative Circulars
Circular No.4/2010 dated November 16, 2010 of the Revenue and Disaster Management Department creates a binding expectation that district administrations post candidates in Firka Revenue Inspector posts to enable completion of the two-year service requirement; failure to do so undermines the validity of any rejection of a relaxation proposal.
Promotion Contingent on Consequential Benefits
Where promotion is directed, the employee is entitled to all consequential monetary and service benefits from the effective date of promotion, including arrears and seniority benefits.