Topic

section 249

3 articlesLatest July 2026
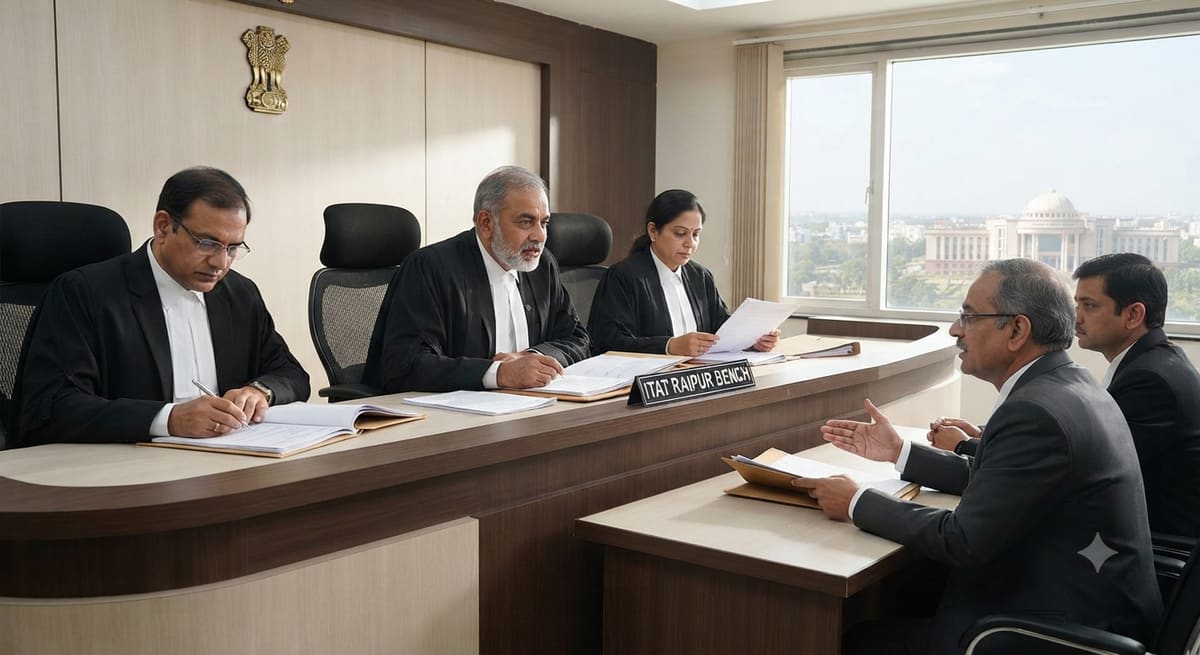
Natural Justice Requires Hearing Before Rejecting Appeal for Delay | ITAT Raipur
Case Law Analysis
|Income Tax Appellate Tribunal

Natural Justice Requires Hearing Before Rejecting Appeal for Delay | ITAT Raipur

The ITAT Raipur bench ruled that dismissing an income tax appeal solely due to delay, without affording the appellant an opportunity to explain the reason, violates fundamental principles of natural justice. This sets a critical precedent for taxpayers and tax authorities alike: procedural fairness trumps technical non-compliance when substantive rights are at stake.

Section 249, Income-tax Act | Delay Condonation Permitted When Technical Defects Cannot Override Substantial Justice : ITAT Dehradun
Case Law Analysis
|Income Tax Appellate Tribunal

Section 249, Income-tax Act | Delay Condonation Permitted When Technical Defects Cannot Override Substantial Justice : ITAT Dehradun

ITAT Dehradun condoned a 399-day delay in filing an income tax appeal, reaffirming that rigid procedural compliance must yield to the principle of substantial justice established in Collector v. Katiji. This ruling empowers taxpayers facing genuine hardship to seek redress without being barred by technicalities, reinforcing the tribunal’s role as a forum for equitable tax justice.

No Notice of Assessment = Condoned Delay in Income Tax Appeal | Section 249A IT Act, Procedural Fairness : ITAT Mumbai
Case Law Analysis
|Income Tax Appellate Tribunal

No Notice of Assessment = Condoned Delay in Income Tax Appeal | Section 249A IT Act, Procedural Fairness : ITAT Mumbai

The ITAT Mumbai ruled that a 140-day delay in filing an income tax appeal is excusable when the assessee received no intimation of the assessment order from either the department or their chartered accountant. This reinforces that procedural fairness under the Income Tax Act requires active communication - not passive vigilance - from taxpayers, protecting individuals from punitive dismissal due to administrative silence.