Topic

Renting of Immovable Property

Renting of immovable property under Indian law refers to the leasing of land or buildings, with tax implications governed by the Finance Act, 1994 and related service tax exemptions.

5 articlesLatest June 2026
Renting Railway Space for Hoardings Is Renting of Immovable Property, Not Support Service | RCM Inapplicable: CESTAT Hyderabad
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

Renting Railway Space for Hoardings Is Renting of Immovable Property, Not Support Service | RCM Inapplicable: CESTAT Hyderabad

CESTAT Hyderabad has ruled that leasing railway premises for advertising hoardings constitutes renting of immovable property under service tax law, not a business support service. This means the reverse charge mechanism does not apply, relieving advertisers from liability to pay tax on behalf of railways and clarifying the tax treatment of infrastructure-based advertising contracts nationwide.
Composite Agricultural Activity Exempts Lease of Tea Estates with Infrastructure from Service Tax: CESTAT Chennai
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

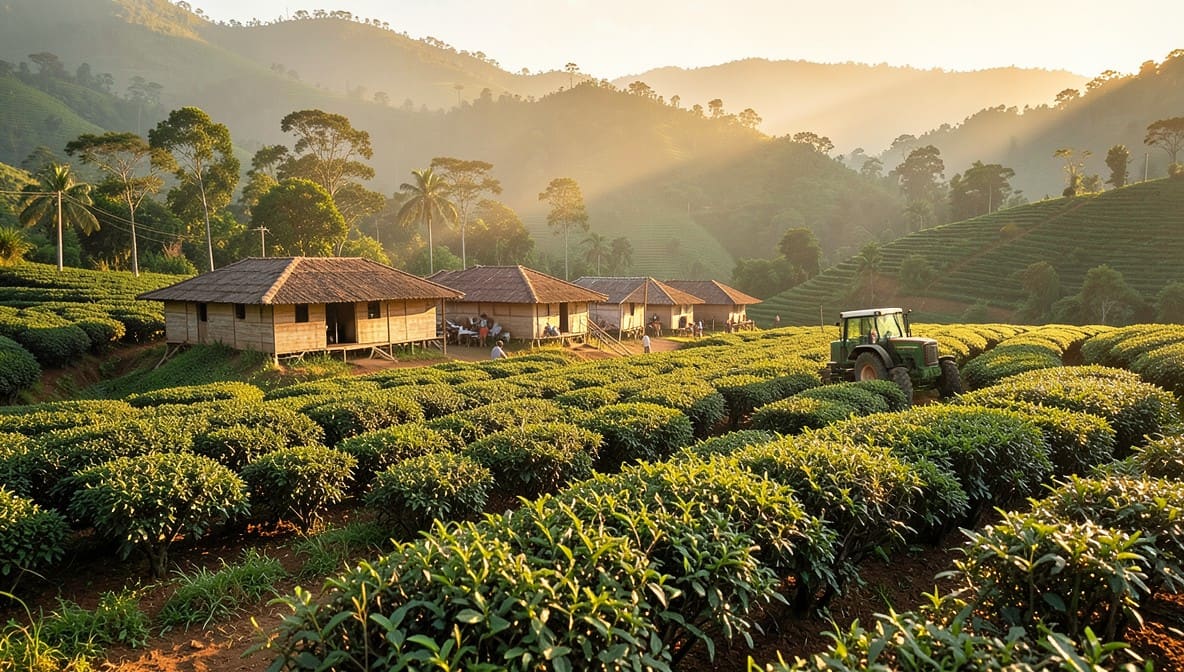
Composite Agricultural Activity Exempts Lease of Tea Estates with Infrastructure from Service Tax: CESTAT Chennai

CESTAT Chennai ruled that leasing tea estates along with incidental labor, machinery, and infrastructure constitutes a single composite agricultural activity, not a taxable service under the Negative List regime. This clarifies that farmers and plantation owners can lease land with operational assets without triggering service tax liability, reinforcing the exemption for genuine agricultural operations.

Finance Act, 1994 | Job Work Amounting to Manufacture Exempt from Service Tax Even If Expenses Reimbursed: CESTAT Hyderabad
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

Finance Act, 1994 | Job Work Amounting to Manufacture Exempt from Service Tax Even If Expenses Reimbursed: CESTAT Hyderabad

CESTAT Hyderabad rules that job work constituting manufacture of excisable goods under the Finance Act, 1994, is exempt from service tax, even if the principal reimburses expenses. The ruling clarifies that the nature of the activity-not the reimbursement mechanism-determines tax liability, providing relief to manufacturers engaged in job work agreements.

Section 65(105)(zzzz) Finance Act | Residential Lease to Company Exempt from Service Tax Even If Occupied by Director: CESTAT Chennai
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

Section 65(105)(zzzz) Finance Act | Residential Lease to Company Exempt from Service Tax Even If Occupied by Director: CESTAT Chennai

CESTAT Chennai rules that renting immovable property for residential use-even if leased to a company and occupied by its managing director-falls under the statutory exemption from service tax under Section 65(105)(zzzz) of the Finance Act. The ruling clarifies that the nature of use, not the lessee’s identity, determines tax liability, offering relief to property owners and corporate lessors.