Topic

Reassessment Notice

A reassessment notice under the Income Tax Act, 1961, allows the tax department to reopen past assessments if it suspects undisclosed income, subject to strict time limits and procedural conditions.

14 articlesLatest August 2026
Section 148 notice barred by Section 149(1)(b) limitation; Rs 20.04 cr share-capital addition quashed | Income-Tax reassessment : ITAT (Kolkata)
Case Law Analysis
|Income Tax Appellate Tribunal

Section 148 notice barred by Section 149(1)(b) limitation; Rs 20.04 cr share-capital addition quashed | Income-Tax reassessment : ITAT (Kolkata)

ITAT Kolkata ruled the Section 148 reassessment notice for AY 2015-16 was barred by Section 149(1)(b) and set aside the ₹20.04 crore share-capital addition treated as unexplained cash credit. The decision protects taxpayers from reassessment notices served outside the statutory limitation period.
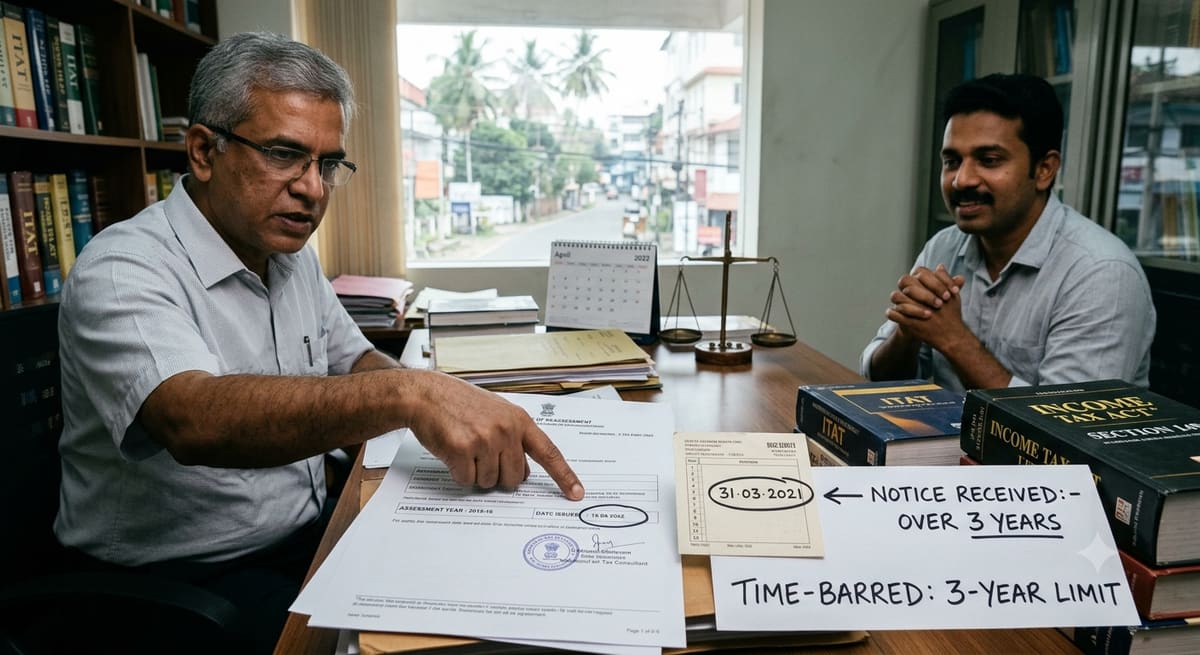

Section 149(1) First Proviso | Reassessment Notice Issued After 31.03.2022 for AY 2015-16 Barred by 3-Year Limit: ITAT Cochin
Case Law Analysis
|Income Tax Appellate Tribunal

Section 149(1) First Proviso | Reassessment Notice Issued After 31.03.2022 for AY 2015-16 Barred by 3-Year Limit: ITAT Cochin

ITAT Cochin has ruled that a reassessment notice issued on 06.05.2022 for AY 2015-16 is time-barred because the income escaped assessment did not exceed ₹50 lakh, triggering the three-year limitation under Section 149(1). This reinforces that post-2022 notices for pre-2019 assessments cannot be revived unless the monetary threshold is crossed, protecting taxpayers from arbitrary reopening.

Section 148 IT Act | Reassessment Notices Issued Beyond Limitation Period Void Ab Initio: ITAT Delhi Applies Rajeev Bansal Precedent
Case Law Analysis
|Income Tax Appellate Tribunal

Section 148 IT Act | Reassessment Notices Issued Beyond Limitation Period Void Ab Initio: ITAT Delhi Applies Rajeev Bansal Precedent

ITAT Delhi quashes reassessment notices for AYs 2013-14 and 2014-15, ruling that notices issued under the old Section 148 provisions after 31.03.2021 are time-barred. The Tribunal relied on the Supreme Court’s decision in Union of India v. Rajeev Bansal, reinforcing strict compliance with limitation periods in tax reassessment proceedings.

Section 148 Income Tax Act | Reassessment Notice Invalid If Section 151(2)(b) Approval Not Obtained Within 3 Years : ITAT Delhi
Case Law Analysis
|Income Tax Appellate Tribunal

Section 148 Income Tax Act | Reassessment Notice Invalid If Section 151(2)(b) Approval Not Obtained Within 3 Years : ITAT Delhi

The ITAT Delhi has ruled that a reassessment notice under Section 148 is void if the mandatory prior approval from the Principal Chief Commissioner or Principal Director General of Income Tax under Section 151(2)(b) is obtained more than three years after the end of the relevant assessment year. This sets a strict temporal limit on procedural compliance, impacting all tax authorities issuing reopening notices and reinforcing the need for timely administrative due process in income tax reassessments.

Section 148 Income Tax Act | Reassessment Notice Invalid Beyond 3 Years Without Pr. CCIT Approval Under Section 151(ii) : ITAT Delhi
Case Law Analysis
|Income Tax Appellate Tribunal

Section 148 Income Tax Act | Reassessment Notice Invalid Beyond 3 Years Without Pr. CCIT Approval Under Section 151(ii) : ITAT Delhi

The ITAT Delhi has ruled that any reassessment notice issued under Section 148 after three years from the end of the assessment year is void unless prior approval is obtained from the Principal Chief Commissioner of Income Tax, as mandated by Section 151(ii). This reinforces strict procedural compliance, protecting taxpayers from arbitrary reopening of closed assessments and setting a binding precedent for all assessing officers handling delayed reassessments.

Section 148 IT Act | Unsigned Reassessment Notice Void Ab Initio; Jurisdictional Defect Non-Curable : ITAT Nagpur
Case Law Analysis
|Income Tax Appellate Tribunal

Section 148 IT Act | Unsigned Reassessment Notice Void Ab Initio; Jurisdictional Defect Non-Curable : ITAT Nagpur

ITAT Nagpur rules that a reassessment notice under Section 148 of the Income Tax Act must bear a manual or digital signature to be valid. The absence of such signature renders the notice void ab initio, stripping the Assessing Officer of jurisdiction to proceed, and this defect cannot be cured under Sections 292B or 292BB. The ruling reinforces strict compliance with statutory mandates under Section 282A, impacting all pending and future reassessment proceedings.

Section 148 IT Act | Reassessment Notice Issued Beyond Limitation Period Void After Supreme Court's Rajeev Bansal Ruling : ITAT Agra
Case Law Analysis
|Income Tax Appellate Tribunal

Section 148 IT Act | Reassessment Notice Issued Beyond Limitation Period Void After Supreme Court's Rajeev Bansal Ruling : ITAT Agra

ITAT Agra quashed reassessment notices issued on 30.07.2022 for AYs 2013-14 and 2014-15, holding that the notices exceeded the limitation period under Section 148 of the IT Act post the Supreme Court's decision in Rajeev Bansal. The tribunal ruled that the legal fiction expiry bars reassessment notices issued beyond the prescribed timeline, reinforcing the binding precedent on tax authorities.

Section 151 IT Act | Invalid Sanction Under Section 151 Vitiates Reassessment Notice : ITAT Delhi Quashes Rs. 9.91 Lakh Addition
Case Law Analysis
|Income Tax Appellate Tribunal

Section 151 IT Act | Invalid Sanction Under Section 151 Vitiates Reassessment Notice : ITAT Delhi Quashes Rs. 9.91 Lakh Addition

ITAT Delhi sets aside a reassessment notice under Section 148 of the Income Tax Act for lack of valid sanction under Section 151, emphasizing strict procedural compliance. The ruling nullifies a Rs. 9.91 lakh addition, reinforcing that jurisdictional defects cannot be cured post-facto and safeguarding assessees from arbitrary reassessments.

Section 148 IT Act | Reassessment Notices for AY 2015-16 Issued After 01.04.2021 Are Void : ITAT Delhi Upholds Supreme Court's TOLA Limitation Ruling
Case Law Analysis
|Income Tax Appellate Tribunal

Section 148 IT Act | Reassessment Notices for AY 2015-16 Issued After 01.04.2021 Are Void : ITAT Delhi Upholds Supreme Court's TOLA Limitation Ruling

ITAT Delhi rules that reassessment notices under Section 148 of the Income Tax Act for Assessment Year 2015-16 issued after 01.04.2021 are time-barred, affirming the Supreme Court's judgment in Union of India v. Ashish Agarwal. The decision reinforces that the Taxation and Other Laws (Amendment) Act, 2020 (TOLA) does not extend the limitation period for reassessment under the old regime, impacting pending tax reassessment proceedings.

Section 149(1)(b) IT Act | Reassessment Notice Void If Escaped Income Below ₹50 Lakh Threshold: ITAT Rajkot
Case Law Analysis
|Income Tax Appellate Tribunal

Section 149(1)(b) IT Act | Reassessment Notice Void If Escaped Income Below ₹50 Lakh Threshold: ITAT Rajkot

ITAT Rajkot rules that reassessment notices under Section 148 of the IT Act are invalid if the escaped income falls below the ₹50 lakh threshold mandated by Section 149(1)(b). The tribunal also held that notices issued beyond the surviving limitation period under TOLA are time-barred, reinforcing procedural compliance as a jurisdictional prerequisite. This ruling impacts taxpayers facing reassessment for AY 2016-17 and beyond, setting a precedent for threshold-based jurisdictional challenges.