Topic

reassessment

Reassessment under the Income Tax Act, 1961 allows tax authorities to reopen completed assessments if they have reason to believe income has been escaped, subject to strict procedural and evidentiary conditions.

66 articlesLatest 1 week ago
Section 151 Income Tax Act | Reassessment Beyond 3 Years Requires PCCIT/CCIT Sanction, Not PCIT Approval : ITAT Kolkata
Case Law Analysis
|Income Tax Appellate Tribunal

Section 151 Income Tax Act | Reassessment Beyond 3 Years Requires PCCIT/CCIT Sanction, Not PCIT Approval : ITAT Kolkata

ITAT Kolkata held that reassessment beyond three years under Section 148 mandates PCCIT or CCIT sanction under Section 151; PCIT approval is jurisdictionally invalid. The tribunal quashed a notice where only PCIT approval was obtained, reinforcing the strict hierarchy for time-barred proceedings and protecting taxpayers from procedurally flawed orders.
Section 56(2)(x) IT Act | Rights Issue Price Differential Not Taxable If Shareholding Static; Section 148A Notice Void Sans Timely Info : Bombay HC
Case Law Analysis

Section 56(2)(x) IT Act | Rights Issue Price Differential Not Taxable If Shareholding Static; Section 148A Notice Void Sans Timely Info : Bombay HC

The Bombay HC quashed reassessment for AY 2020-21, ruling a Section 148A(1) notice invalid where mandatory information was furnished post-limitation. On merits, the Court held Section 56(2)(x) inapplicable to proportionate rights allotments with unchanged shareholding and no disproportionate benefit - a mere issue price vs. FMV differential is not taxable in such cases.

Section 148 notice barred by Section 149(1)(b) limitation; Rs 20.04 cr share-capital addition quashed | Income-Tax reassessment : ITAT (Kolkata)
Case Law Analysis
|Income Tax Appellate Tribunal

Section 148 notice barred by Section 149(1)(b) limitation; Rs 20.04 cr share-capital addition quashed | Income-Tax reassessment : ITAT (Kolkata)

ITAT Kolkata ruled the Section 148 reassessment notice for AY 2015-16 was barred by Section 149(1)(b) and set aside the ₹20.04 crore share-capital addition treated as unexplained cash credit. The decision protects taxpayers from reassessment notices served outside the statutory limitation period.

Section 148 Re-assessment Notice Time-Barred Under Section 149(1)(a) - Quashed for AY 2016-17 & 2017-18 | ITAT Panaji
|Income Tax Appellate Tribunal

Section 148 Re-assessment Notice Time-Barred Under Section 149(1)(a) - Quashed for AY 2016-17 & 2017-18 | ITAT Panaji

ITAT Panaji quashed the 29 July 2022 Section 148 notice as time-barred under Section 149(1)(a), setting aside assessments for AY 2016-17 and 2017-18. The tribunal held that reassessment cannot proceed when the three-year limitation expires and the monetary threshold is below Rs 50 lakh, applying the Ganesh Dass Khanna test. Taxpayers gain protection from stale reassessment notices.

SC Restores ITAT Jaipur’s Reassessment Jurisdiction After HC Quash | Section 148 Faceless Scheme : ITAT Jaipur
Case Law Analysis
|Income Tax Appellate Tribunal

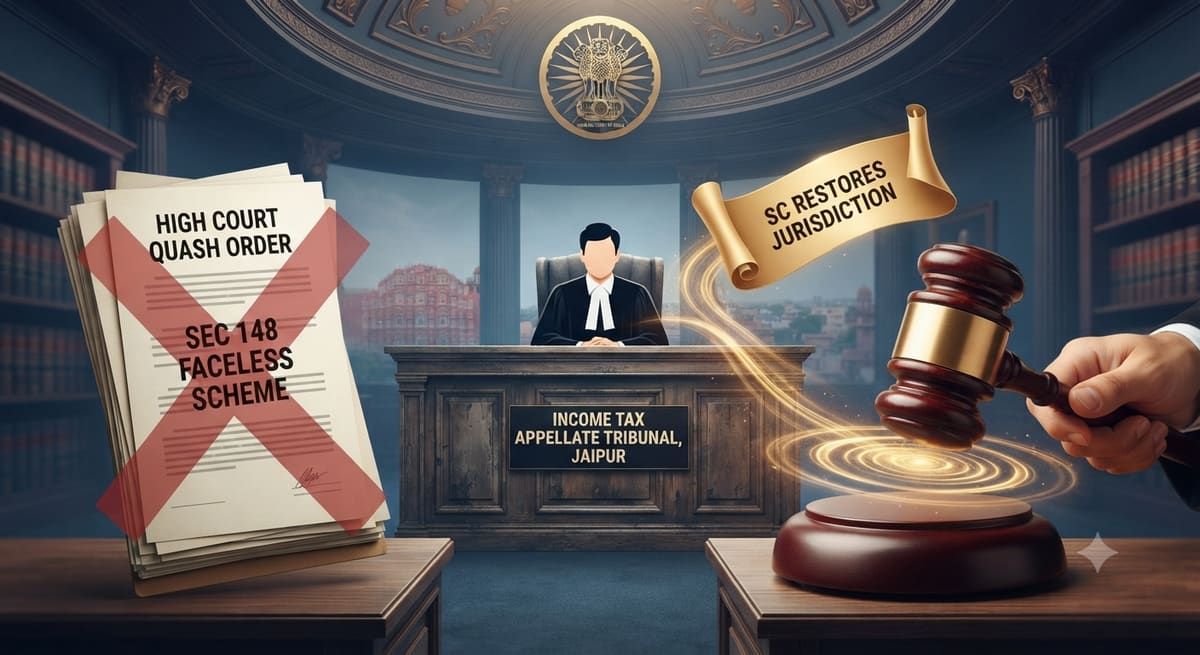
SC Restores ITAT Jaipur’s Reassessment Jurisdiction After HC Quash | Section 148 Faceless Scheme : ITAT Jaipur

Supreme Court set aside a Rajasthan High Court order quashing a Section 148 reassessment notice, restoring the Income Tax Appellate Tribunal Jaipur’s jurisdiction to re-examine the case under the Faceless Assessment Scheme. The ruling clarifies that appellate jurisdiction under the Act remains distinct from writ jurisdiction, impacting reassessment proceedings pending before ITAT.

7-Day Compliance Period Mandatory Under Section 148A IT Act | Kolkata ITAT Quashes Reassessment Notices : ITAT Kolkata
Case Law Analysis
|Income Tax Appellate Tribunal

7-Day Compliance Period Mandatory Under Section 148A IT Act | Kolkata ITAT Quashes Reassessment Notices : ITAT Kolkata

Kolkata ITAT quashed reassessment notices under Section 148A for failing to provide the mandatory 7-day compliance period and unsigned notices, reinforcing strict procedural safeguards in tax reassessment. The ruling underscores the importance of adherence to statutory timelines for notices issued under the Income Tax Act, impacting future reassessment proceedings.

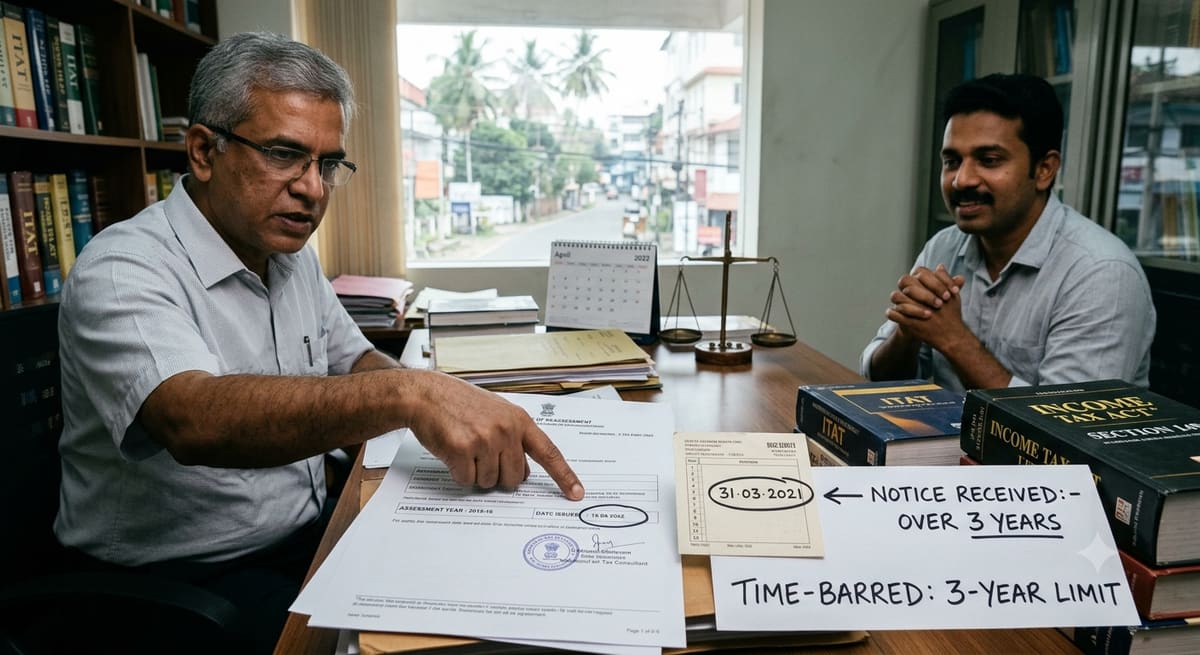
Section 149(1) First Proviso | Reassessment Notice Issued After 31.03.2022 for AY 2015-16 Barred by 3-Year Limit: ITAT Cochin
Case Law Analysis
|Income Tax Appellate Tribunal

Section 149(1) First Proviso | Reassessment Notice Issued After 31.03.2022 for AY 2015-16 Barred by 3-Year Limit: ITAT Cochin

ITAT Cochin has ruled that a reassessment notice issued on 06.05.2022 for AY 2015-16 is time-barred because the income escaped assessment did not exceed ₹50 lakh, triggering the three-year limitation under Section 149(1). This reinforces that post-2022 notices for pre-2019 assessments cannot be revived unless the monetary threshold is crossed, protecting taxpayers from arbitrary reopening.

Section 143(2) Notice Mandatory for Reassessment | Non-Compliance Vitiates Assessment Under Section 144C : ITAT Mumbai
Case Law Analysis
|Income Tax Appellate Tribunal

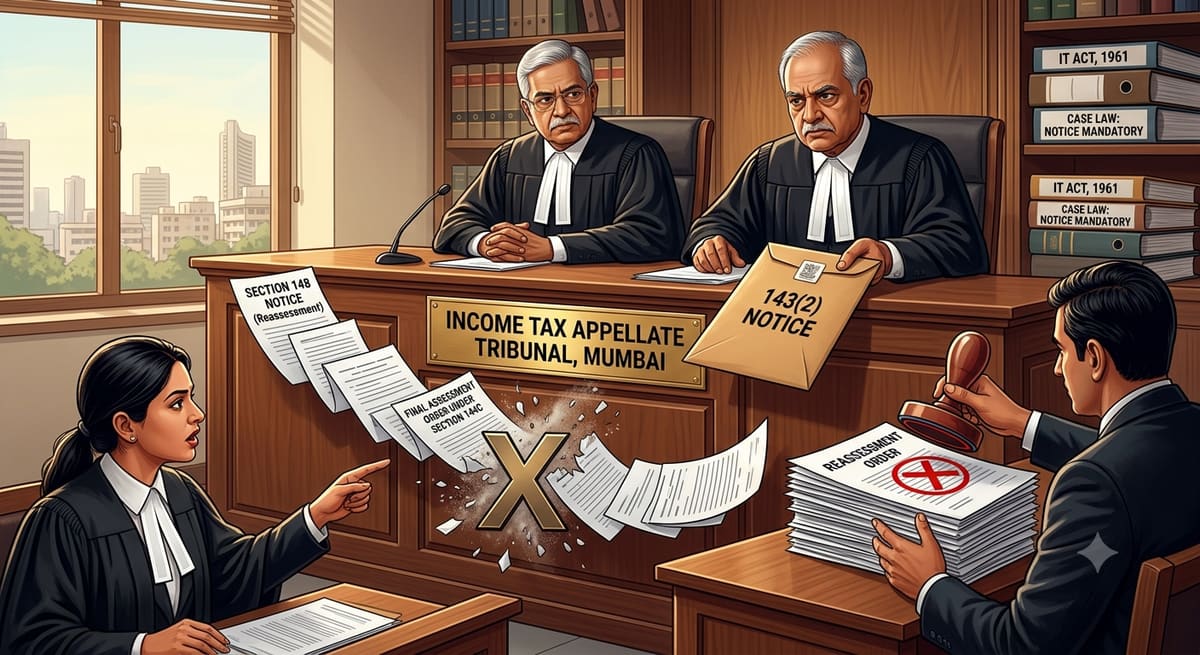
Section 143(2) Notice Mandatory for Reassessment | Non-Compliance Vitiates Assessment Under Section 144C : ITAT Mumbai

ITAT Mumbai rules that failure to issue a mandatory notice under Section 143(2) during reassessment proceedings renders the entire assessment void ab initio. The tribunal held that issuing a demand notice alongside a draft assessment order under Section 144C without adhering to procedural safeguards constitutes a jurisdictional error, impacting all taxpayers undergoing reassessment.

Section 148 IT Act | Approval Authority Must Align with Notice Timing: ITAT Delhi Quashes Reassessment for Wrong Competent Authority
Case Law Analysis
|Income Tax Appellate Tribunal

Section 148 IT Act | Approval Authority Must Align with Notice Timing: ITAT Delhi Quashes Reassessment for Wrong Competent Authority

ITAT Delhi ruled that reassessment notices under Section 148 of the Income Tax Act must be approved by the competent authority based on the timing of issuance. For notices issued after three years, only the Pr. Chief Commissioner-not the Pr. CIT-can grant approval. The Tribunal quashed the assessment order, reinforcing strict procedural compliance in tax reassessment.