Topic

ITAT Jaipur

9 articlesLatest August 2026
Section 149(1)(a) bars reopening where §148 notice issued after 3 years and escaped income < Rs 50 Lakh - bogus political donation deduction denied | ITAT Jaipur
|Income Tax Appellate Tribunal

Section 149(1)(a) bars reopening where §148 notice issued after 3 years and escaped income < Rs 50 Lakh - bogus political donation deduction denied | ITAT Jaipur

The tribunal held that a section 148 notice dated 12-April-2023 was time-barred under section 149(1)(a) because the income escaping assessment was below Rs 50 lakh, and therefore quashed the assessment disallowing the claimed deduction under 80GGC for a bogus political donation. The ruling underscores that reopening notices beyond three years are invalid when the escaped income does not exceed the Rs 50 lakh threshold.
ITAT Jaipur | Non-Application of Mind by AO Invalidates Section 153C Assessment
|Income Tax Appellate Tribunal

ITAT Jaipur | Non-Application of Mind by AO Invalidates Section 153C Assessment

ITAT Jaipur quashed an assessment under Section 153C of the Income Tax Act, 1961, after finding the Assessing Officer failed to apply mind while recording satisfaction. The ruling underscores strict compliance with statutory prerequisites for invoking Section 153C, impacting pending and future assessments based on similar jurisdictional flaws.

DTVSV Act 2020 Section 5 Immunity | Penalty u/s 271(1)(c) Quashed Post-Scheme Settlement : ITAT Jaipur
Case Law Analysis
|Income Tax Appellate Tribunal

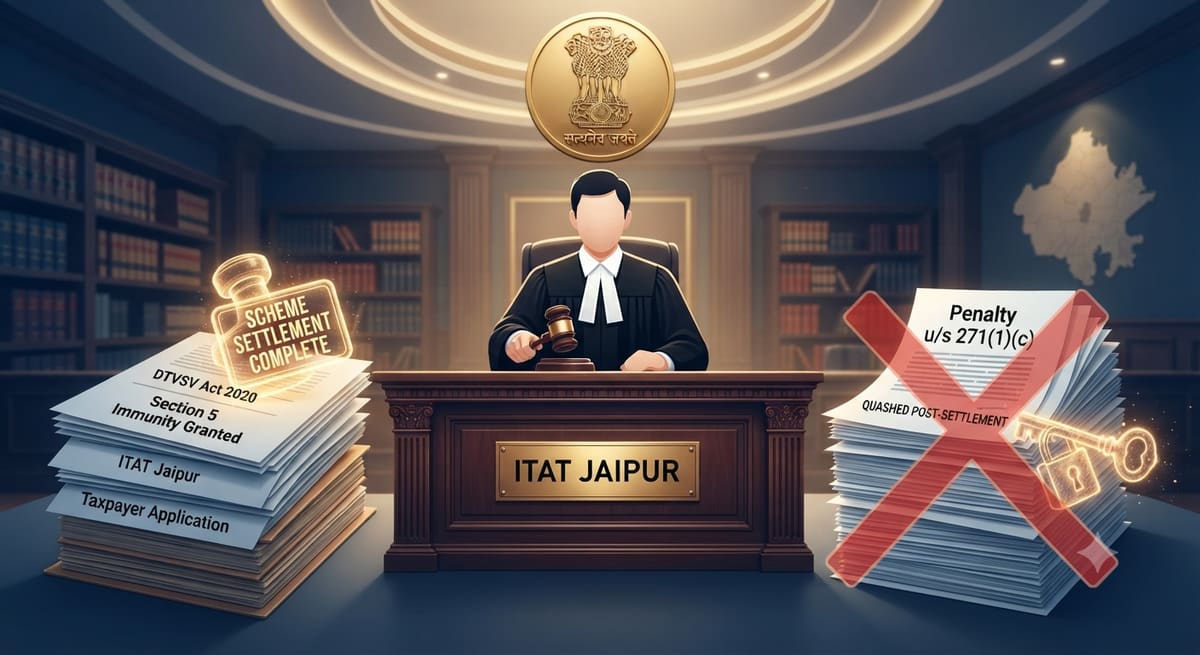
DTVSV Act 2020 Section 5 Immunity | Penalty u/s 271(1)(c) Quashed Post-Scheme Settlement : ITAT Jaipur

The ITAT Jaipur bench quashed penalty under Section 271(1)(c) after the assessee settled quantum dispute under the Direct Tax Vivad Se Vishwas Scheme 2020, holding that Section 5 grants immunity from penalty post-scheme settlement. This ruling clarifies that penalty proceedings cannot survive once a dispute is resolved under the DTVSV Act.

Section 271AAC(1) & 272A(1)(d) NI Act | Penalty Invalid If Underlying Unexplained Income Addition Is Deleted on Appeal : ITAT Jaipur
Case Law Analysis
|Income Tax Appellate Tribunal

Section 271AAC(1) & 272A(1)(d) NI Act | Penalty Invalid If Underlying Unexplained Income Addition Is Deleted on Appeal : ITAT Jaipur

When an appellate authority deletes an addition of unexplained income under Section 69A, penalties imposed under Sections 271AAC(1) and 272A(1)(d) automatically lapse - the penalty cannot stand without its foundational tax liability. This ruling protects cooperative societies and other assessees from punitive measures rooted in nullified assessments, reinforcing that penalties are consequential, not independent, under the Income Tax Act.

Section 145(3) IT Act | Statistical Deviations Alone Cannot Justify Rejection of Audited Books : ITAT Jaipur
Case Law Analysis
|Income Tax Appellate Tribunal

Section 145(3) IT Act | Statistical Deviations Alone Cannot Justify Rejection of Audited Books : ITAT Jaipur

The ITAT Jaipur deleted a Rs. 40.82 lakh addition for unexplained cash deposits, ruling that mere deviations in cash sales or bank deposits-even amid demonetization-are insufficient to reject duly audited books of accounts. This reinforces that tax authorities must identify specific, material defects in accounting records, not rely on speculative patterns, protecting compliant businesses from arbitrary assessments.