Topic

Extended Limitation

Extended limitation under Indian tax laws allows authorities to reassess tax demands beyond the usual period only if there is evidence of suppression or fraudulent intent.

14 articlesLatest June 2026
CENVAT Credit on Capital Goods | Eligibility Based on Post-Registration Use, Not Receipt Date: CESTAT Kolkata
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

CENVAT Credit on Capital Goods | Eligibility Based on Post-Registration Use, Not Receipt Date: CESTAT Kolkata

CESTAT Kolkata ruled that CENVAT credit on capital goods like tippers is valid if used for taxable services after registration, even if purchased and received earlier. This removes the department’s arbitrary denial of credit based on pre-registration acquisition, empowering service providers to claim rightful input tax credits without being penalized for timing mismatches.
Section 65(91a) Finance Act | Construction of Individual Houses for Tsunami Victims, Police & NGOs Not 'Residential Complex' : CESTAT Chennai
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

Section 65(91a) Finance Act | Construction of Individual Houses for Tsunami Victims, Police & NGOs Not 'Residential Complex' : CESTAT Chennai

CESTAT Chennai rules that service tax cannot be levied on construction of standalone dwellings for tsunami survivors, police housing, or NGOs, as these do not qualify as 'residential complexes' under the Finance Act. This clarifies the scope of commercial construction taxation and protects non-profit and humanitarian housing projects from misapplied service tax demands.

Service Tax Double Taxation Barred | No Demand If Provider Already Paid Tax, Even Under Extended Limitation Without Wilful Evasion : CESTAT Chennai
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

Service Tax Double Taxation Barred | No Demand If Provider Already Paid Tax, Even Under Extended Limitation Without Wilful Evasion : CESTAT Chennai

CESTAT Chennai rules that service tax cannot be imposed on a recipient when the service provider has already paid the tax, invalidating departmental demands even under extended limitation periods unless wilful evasion is proven. This clarifies Cenvat credit eligibility and protects businesses from cascading tax liability where input tax has been fully discharged by suppliers.

CTH 9013 | LCD Panels for Automotive Instrument Clusters Not 'Parts of Motor Vehicles' Under Specificity Doctrine : CESTAT Chennai
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

CTH 9013 | LCD Panels for Automotive Instrument Clusters Not 'Parts of Motor Vehicles' Under Specificity Doctrine : CESTAT Chennai

CESTAT Chennai rules that LCD panels, even when custom-designed for vehicle instrument clusters, cannot be classified as motor vehicle parts under CTH 8708/8714 because they are more specifically covered under CTH 9013 as liquid crystal devices. This clarifies that mere integration into a vehicle does not override the principle of specific tariff headings over use-based classification, impacting importers of electronics for automotive use nationwide.

Service Tax Not Leviable on Software Sales with VAT Payment or Overseas Exhibitions : CESTAT Chandigarh Clarifies Extended Limitation Requires Proof of Suppression
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

Service Tax Not Leviable on Software Sales with VAT Payment or Overseas Exhibitions : CESTAT Chandigarh Clarifies Extended Limitation Requires Proof of Suppression

CESTAT Chandigarh rules that service tax cannot be imposed on software sales where VAT is already paid or on overseas exhibitions, as these do not qualify as taxable services. The tribunal also held that extended limitation under Section 73(1) of the Finance Act, 1994, requires concrete proof of suppression, not merely non-payment, impacting tax assessments for IT firms and exporters.

Service Tax Valuation | Reimbursable Expenses Excluded from Taxable Value Under Pure Agent Rule: CESTAT Chennai
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

Service Tax Valuation | Reimbursable Expenses Excluded from Taxable Value Under Pure Agent Rule: CESTAT Chennai

CESTAT Chennai reaffirms that reimbursable expenses collected by service providers do not form part of taxable value under the Service Tax Valuation Rules, provided the 'Pure Agent' conditions are met. The ruling shields businesses from retrospective tax demands on expenses like freight, warehousing, and survey charges, reinforcing the Supreme Court's precedent invalidating Rule 5(1).

Customs Tariff Classification | Integrated Analytical Systems Must Fall Under Chapter 9027, Not 9032 : CESTAT Bangalore Rejects Extended Limitation Without Proof
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

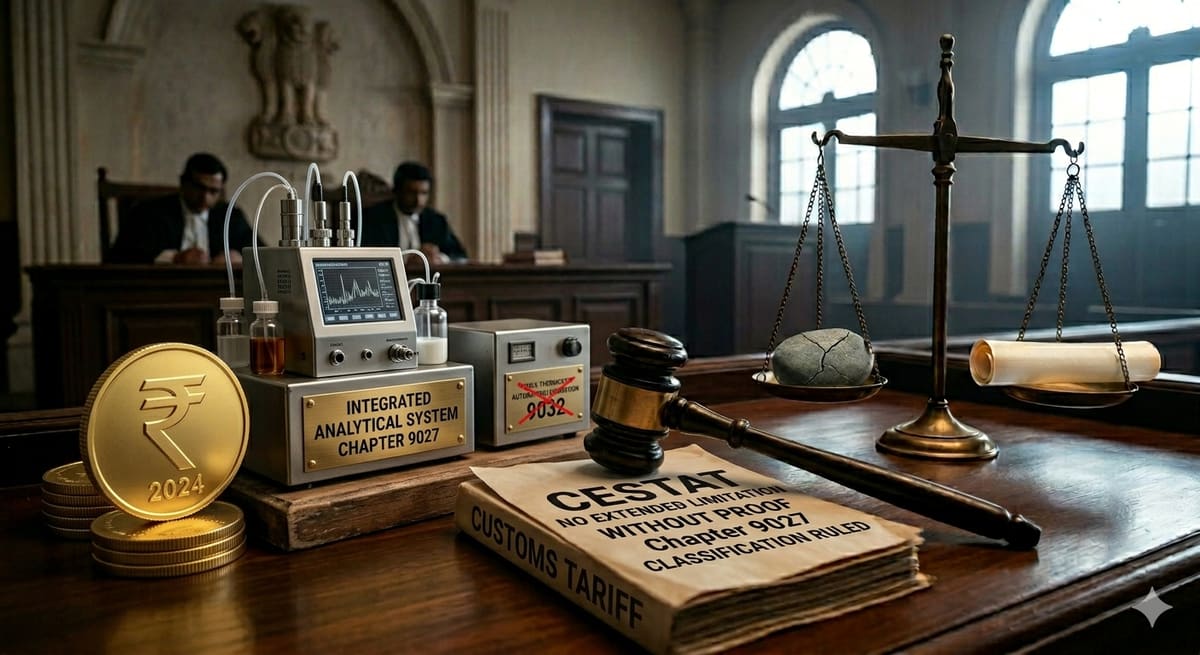
Customs Tariff Classification | Integrated Analytical Systems Must Fall Under Chapter 9027, Not 9032 : CESTAT Bangalore Rejects Extended Limitation Without Proof

CESTAT Bangalore ruled that an aerosol generator forming part of an integrated analytical system must be classified under Customs Tariff Heading 90278090, not 9032. The tribunal rejected the Department's reclassification and held that extended limitation cannot be invoked without concrete proof, setting a precedent for tariff disputes involving integrated systems.

Section 11A(4) Central Excise Act | Extended Limitation Inapplicable Where Department Had Full Knowledge of Transactions : CESTAT Principal Bench
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

Section 11A(4) Central Excise Act | Extended Limitation Inapplicable Where Department Had Full Knowledge of Transactions : CESTAT Principal Bench

CESTAT quashes excise demand and penalties, ruling that extended limitation under Section 11A(4) cannot be invoked if the department was fully aware of the transactions. The judgment reaffirms that suppression of facts must be deliberate for extended limitation to apply, impacting tax assessments where transparency exists.

Trade Discounts & Manufacturer Incentives Not Taxable as Business Auxiliary Service | CESTAT Kolkata Clarifies Trading Profit Distinction
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

Trade Discounts & Manufacturer Incentives Not Taxable as Business Auxiliary Service | CESTAT Kolkata Clarifies Trading Profit Distinction

CESTAT Kolkata rules that incentives and trade discounts received by car dealers from manufacturers constitute trading profits, not taxable services under Business Auxiliary Service. This removes a major compliance burden on auto dealers and invalidates extended limitation demands where no suppression of facts is proven, setting a critical precedent for dealer-tax disputes across India.

Section 11A Central Excise Act | Extended Limitation Inapplicable Without Proof of Suppression in Bona Fide Classification Disputes : CESTAT Chandigarh
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

Section 11A Central Excise Act | Extended Limitation Inapplicable Without Proof of Suppression in Bona Fide Classification Disputes : CESTAT Chandigarh

CESTAT Chandigarh rules that extended limitation under Section 11A of the Central Excise Act cannot be invoked merely for classification disputes unless deliberate suppression or intent to evade duty is proven. The ruling shields manufacturers from retrospective demands where classification errors stem from bona fide belief, reinforcing the need for clear evidence of fraudulent intent in excise proceedings.