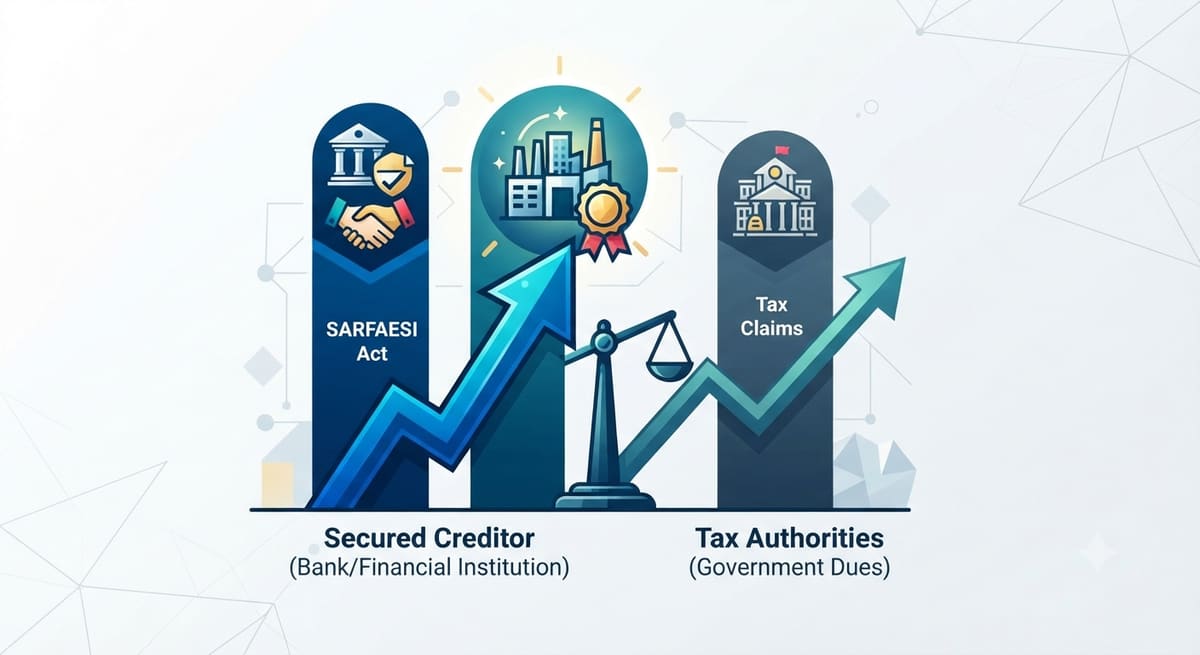
The Bombay High Court has clarified that a bank’s prior registered security interest under the SARFAESI Act takes precedence over subsequent GST recovery proceedings, reinforcing the statutory priority of secured creditors in asset enforcement.
Background & Facts
The Dispute
Axis Bank Limited, having extended credit to a borrower, registered its security interest in the Central Registry of Securitisation Asset Reconstruction and Security Interest of India (CERSAI) under the Securitisation and Reconstruction of Financial Assets and Enforcement of Security Interest Act, 2002. Subsequently, the Central Goods and Services Tax Department issued a communication dated 10 February 2022, purporting to restrict the bank from enforcing its security interest over the pledged asset, citing pending GST dues. The bank challenged this communication as unlawful and contrary to its statutory rights under the SARFAESI Act.
Procedural History
- 2019: Axis Bank registered its security interest in CERSAI against the borrower’s assets.
- 2021: Borrower defaulted on loan repayments; bank initiated proceedings under SARFAESI Act.
- February 2022: Deputy Commissioner of CGST issued Exhibit-F communication directing restraint on asset enforcement.
- 2026: Petition filed before the Bombay High Court seeking quashing of the communication.
Relief Sought
The petitioner sought quashing of the impugned communication dated 10.02.2022, arguing that it violated the hierarchy of claims established under the SARFAESI Act and the Full Bench judgment in Jalgaon Janta Sahakari Bank Ltd. v. Joint Commissioner of Sales Tax.
The Legal Issue
The central question was whether a government authority, acting under the GST regime, can issue a notice or direction that impedes a secured creditor from enforcing its security interest when that interest was duly registered in CERSAI prior to the initiation of recovery proceedings.
Arguments Presented
For the Petitioner
The petitioner relied on the Full Bench judgment in Jalgaon Janta Sahakari Bank Ltd. v. Joint Commissioner of Sales Tax to argue that once a security interest is validly registered under the SARFAESI Act, it attains statutory priority over subsequent claims, including tax dues. The communication issued by the GST Department was ultra vires, as it effectively created a de facto lien without statutory authority and contravened the scheme of the SARFAESI Act. The bank emphasized that CERSAI registration provides public notice and legal sanctity to its claim.
For the Respondent
The Respondent did not file a written submission but appeared through counsel who contended that the GST Department has a statutory mandate under the CGST Act to recover dues, and that such recovery powers cannot be overridden by private contractual arrangements. The argument implied that tax claims, especially those involving public revenue, should be treated as paramount.
The Court's Analysis
The Court examined the legislative intent behind the SARFAESI Act and the CERSAI registry system. It noted that the Act was enacted to establish a transparent, priority-based mechanism for enforcement of security interests, with CERSAI serving as the central public repository for such registrations. The Court held that the Jalgaon Janta Sahakari Bank precedent was directly applicable: once a security interest is registered, no other authority can unilaterally impose restrictions on its enforcement.
"The registration of security interest in CERSAI is not a mere formality; it is a statutory notification that binds all third parties, including revenue authorities, to respect the priority of the secured creditor."
The Court rejected the notion that tax recovery claims inherently override secured interests. It emphasized that while tax dues are important, they are not automatically superior to registered security interests. The CGST Department’s communication, issued without any judicial or quasi-judicial order, amounted to an executive overreach that undermined the statutory framework of the SARFAESI Act. The Court further observed that the Department’s remedy lay in filing a claim before the Debt Recovery Tribunal or seeking attachment under the provisions of the CGST Act itself, not through unilateral directives.
The Verdict
The petitioner succeeded. The Court held that a duly registered security interest under the SARFAESI Act prevails over subsequent GST recovery notices, and quashed the impugned communication dated 10.02.2022. The bank was permitted to proceed with enforcement without hindrance.
What This Means For Similar Cases
Registered Security Interest Is Absolute Against Tax Notices
- Practitioners must immediately challenge any GST or tax authority notice that seeks to restrain enforcement of a CERSAI-registered security interest.
- The burden shifts to the revenue authority to prove that the security interest was fraudulent or improperly registered - not merely that dues are outstanding.
Procedural Remedies for Tax Authorities Are Prescribed
- Tax authorities cannot issue ad hoc directions to banks or financial institutions to freeze assets.
- Proper recourse is to file a claim before the DRT under Section 17 of SARFAESI Act or initiate attachment proceedings under Section 83 of the CGST Act.
CERSAI Registration Is a Shield, Not a Formality
- Financial institutions must ensure timely and accurate CERSAI registration at the time of loan disbursement.
- Failure to register may leave the creditor vulnerable to competing claims, even if the security agreement is valid.