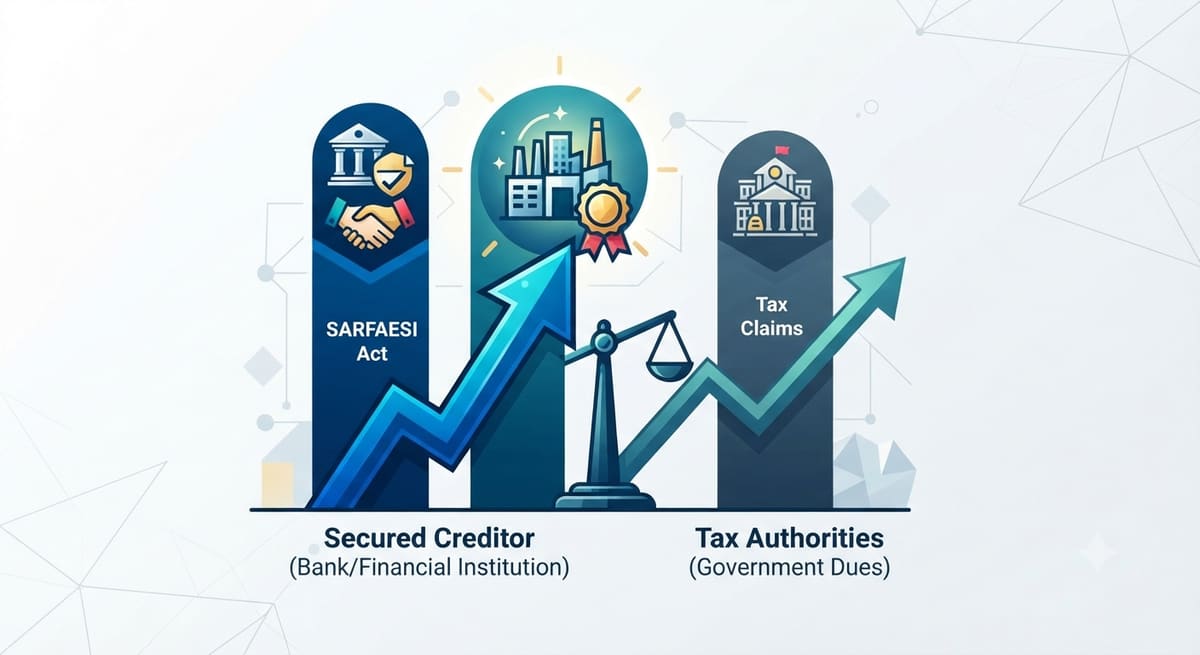
The Bombay High Court has affirmed that a secured creditor’s priority under the SARFAESI Act prevails over subsequent state tax claims, provided the security interest was duly registered in CERSAI before any attachment notice. This ruling reinforces the statutory hierarchy established by Parliament and provides critical clarity for banks and financial institutions navigating competing claims over secured assets.
Background & Facts
The Dispute
Axis Bank Limited, a secured creditor, had extended a loan to a borrower and registered its security interest in the Central Registry of Securitisation Asset Reconstruction and Security Interest of India (CERSAI) on 10 April 2018. The security interest pertained to a residential flat. Subsequently, the State of Maharashtra, through its tax authorities, issued notices of attachment against the same property to recover outstanding State Goods and Services Tax (SGST) dues. The first such notice was dated 27 June 2023, followed by a second on 23 August 2024.
Procedural History
- 10 April 2018: Axis Bank registered its security interest in CERSAI.
- 27 June 2023: State of Maharashtra issued first notice of attachment for SGST dues.
- 23 August 2024: Second notice of attachment issued, referencing the earlier notice.
- 2026: Axis Bank filed Writ Petition No. 640 of 2026 before the Bombay High Court seeking quashing of the attachment orders.
- 18 February 2026: Court heard arguments and delivered judgment.
Relief Sought
The petitioner sought a writ of mandamus or certiorari directing the State to remove its lien or charge on the secured asset, asserting that its prior CERSAI registration conferred legal priority under Section 26E of the SARFAESI Act.
The Legal Issue
The central question was whether a secured creditor’s priority under Section 26E of the SARFAESI Act is defeated when the State issues a notice of attachment after the creditor’s CERSAI registration, even if the attachment precedes any sale or enforcement by the creditor.
Arguments Presented
For the Petitioner
Axis Bank relied on the Full Bench judgment in Janta Sahakari Bank Ltd. v. Joint Commissioner of Sales Tax (2022 SCC OnLine Bom 1767), arguing that Section 26E grants secured creditors priority over all other dues, including taxes, provided their security interest is registered in CERSAI before any competing claim is enforced. The bank emphasized that its registration in 2018 was prior to the State’s 2023 attachment notice, and that the non-obstante clause in Section 26E overrides any contrary provision under tax laws.
For the Respondent
The State contended that the Full Bench judgment’s cut-off date of 24 January 2020 - when amendments to the SARFAESI Act came into force - required examination of whether the attachment predated or postdated that date. It argued that the nature of tax dues under state legislation warranted a different treatment and that registration alone, without actual enforcement, did not conclusively establish priority.
The Court's Analysis
The Court undertook a detailed review of the Full Bench judgment in Janta Sahakari Bank, particularly paragraphs 85 and 154. It held that Section 26E was enacted to eliminate ambiguity in the hierarchy of claims over secured assets. The provision explicitly states that the secured creditor’s claim shall have priority over all other dues, including taxes, cesses, and rates payable to the State.
"Priority means precedence or going before... Parliament advisedly used the word 'priority over all other dues' in the SARFAESI Act to obviate any confusion as to inter se distribution of proceeds..."
The Court rejected the State’s argument that the 24 January 2020 cut-off date created a temporal limitation on priority. It clarified that the cut-off applied only to the requirement of registration for newly created security interests after that date, not to the validity of pre-existing registrations. Since Axis Bank’s CERSAI registration dated back to 2018, it was fully protected under the law as it stood at the time of creation.
The Court further noted that the State’s attachment notices, issued in 2023 and 2024, were subsequent to the bank’s registration. The State’s failure to register its attachment in CERSAI or to challenge the bank’s prior interest rendered its claim subordinate. The Court emphasized that non-obstante clauses in Section 31B and Section 26E were designed precisely to prevent such competing claims from undermining the secured creditor’s position.
The Verdict
The petitioner won. The Court held that a secured creditor with a prior CERSAI registration enjoys absolute priority over subsequent state tax claims, regardless of whether the creditor has yet enforced its security interest. The Court directed the State to remove its lien on the property and dismissed all pending applications.
What This Means For Similar Cases
CERSAI Registration Is the Defining Event
- Practitioners must verify CERSAI registration dates before advising clients on asset recovery or tax liability exposure.
- Any attachment by tax authorities after CERSAI registration is legally invalid against the secured creditor’s priority.
- Banks must ensure timely registration of all security interests, even for existing loans, to preserve priority.
State Tax Claims Cannot Override SARFAESI Priority
- Revenue departments must now register their attachment orders in CERSAI to claim any enforceable interest.
- The judgment closes the loophole where tax authorities assumed automatic superiority over financial institutions.
- Legal notices issued by tax officials must now be cross-checked against CERSAI records before enforcement.
Enforcement Timing Does Not Affect Priority
- A secured creditor need not have initiated SARFAESI proceedings to claim priority.
- Priority is determined by the date of CERSAI registration, not the date of auction or sale.
- This protects creditors even during prolonged litigation or delays in enforcement.