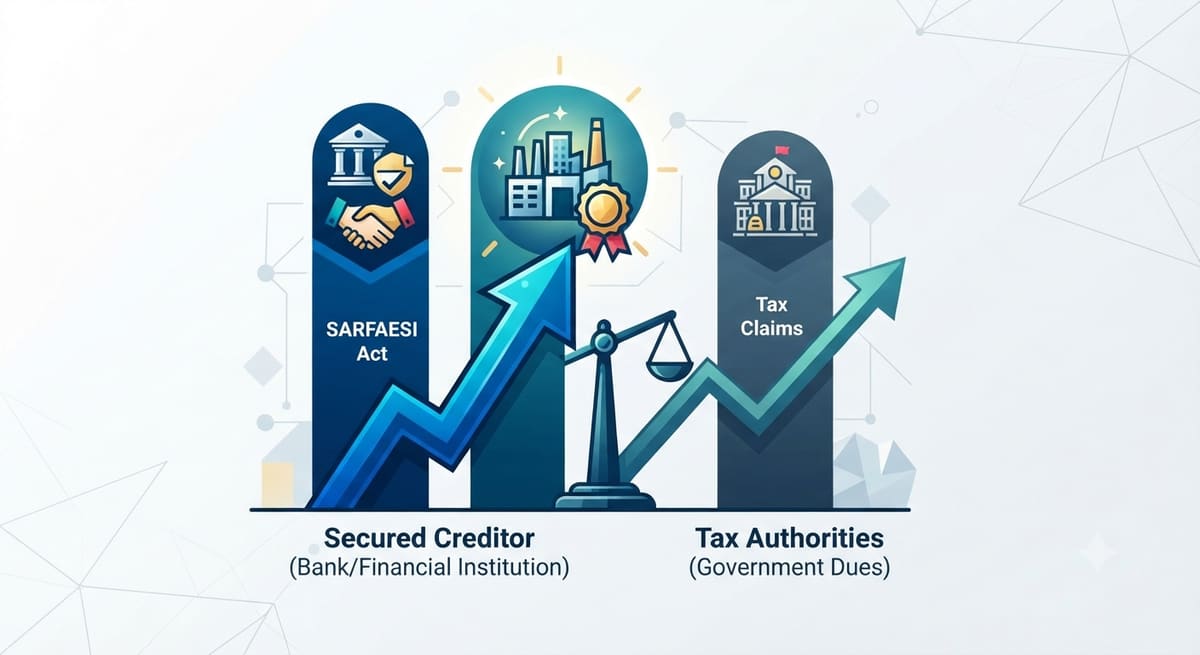
The Bombay High Court has reaffirmed the priority of secured creditors' dues over tax claims when tax authorities fail to register their charges with the Central Registry of Securitisation Asset Reconstruction and Security Interest of India (CERSAI). This judgment underscores the binding nature of the full Bench decision in Jalgaon Janta Sahakari Bank Ltd. v. Joint Commissioner of Sales Tax, clarifying the legal framework governing such disputes.
Background & Facts
The Dispute
The Central Bank of India (petitioner), a secured creditor, filed two writ petitions challenging the priority of tax dues claimed by the Maharashtra Sales Tax and State Tax Departments (respondents). The bank asserted its priority under the Securitisation and Reconstruction of Financial Assets and Enforcement of Security Interest Act, 2002 (SARFAESI Act), relying on its CERSAI registration of security interest dated 26th November 2025.
Key Facts
Writ Petition (L) No. 5750 of 2026:
The Sales Tax Department issued an attachment order dated 4th August 2017 against the secured asset.
The bank’s security interest was registered with CERSAI on 26th November 2025.
The department failed to register its charge with CERSAI or demonstrate compliance with proclamation requirements under the Maharashtra Land Revenue Code, 1960 (MLRC).
Mutation entries (Nos. 187 dated 2nd January 2014 and 211 dated 26th August 2017) were recorded in the 7/12 extract of the secured asset.
Writ Petition (L) No. 5830 of 2026:
The State Tax Department issued a communication dated 14th October 2020 to the Tahsildar for recording its encumbrance in the revenue record (7/12 extract).
The bank’s security interest was registered with CERSAI on 26th November 2025.
The department’s charge was not registered with CERSAI.
Procedural History
Both petitions were filed by the Central Bank of India as the secured creditor.
The respondents (Sales Tax and State Tax Departments) relied on attachment orders and mutation entries but did not register their charges with CERSAI.
The Court examined the applicability of the full Bench judgment in Jalgaon Janta Sahakari Bank Ltd. v. Joint Commissioner of Sales Tax (2022 SCC OnLine Bom 1767).
Relief Sought
The petitioner sought:
Quashing of the impugned orders dated 9th December 2013, 26th August 2017, and 14th October 2020.
Removal of mutation entries (Nos. 187, 211, and 232) from the 7/12 extract of the secured asset.
The Legal Issue
The central question was whether the secured creditor’s dues under the SARFAESI Act take priority over tax dues when the tax authorities fail to register their charges with CERSAI or comply with proclamation requirements under the MLRC.
Arguments Presented
For the Petitioner
The bank relied on Section 26E of the SARFAESI Act, which grants secured creditors priority over all other dues, including taxes.
It argued that the full Bench judgment in Jalgaon Janta Sahakari Bank Ltd. applied, as the Sales Tax Department’s attachment order (2017) predated the 24th January 2020 amendment to the SARFAESI Act but lacked CERSAI registration or proclamation compliance.
For the State Tax Department, the bank contended that the 14th October 2020 communication post-dated the amendment, and the department’s failure to register its charge with CERSAI rendered its claim subordinate.
For the Respondent
The State argued that the bank’s auction sale of the secured asset on an as-is-where-is basis would not extinguish the tax liability.
It submitted joint affidavits asserting that the departments’ claims remained enforceable regardless of the bank’s priority.
No oral submissions were made regarding amendments to Section 37 of the Maharashtra Value Added Tax Act, 2002 (MVAT).
The Court's Analysis
The Court relied on the full Bench judgment in Jalgaon Janta Sahakari Bank Ltd. v. Joint Commissioner of Sales Tax, which held:
"Priority means precedence or going before (Black's Law Dictionary). In the present context, it would mean the right to enforce a claim in preference to others. In view of the splurge of 'first charge' used in multiple legislation, Parliament advisedly used the word 'priority over all other dues' in the SARFAESI Act to obviate any confusion as to inter se distribution of proceeds received from sale of properties of the borrower/dealer."
The Court emphasized that:
Post-24th January 2020, any attachment order not registered with CERSAI is unenforceable against a secured creditor’s registered interest.
For pre-amendment attachments (pre-24th January 2020), the State must demonstrate compliance with MLRC proclamation requirements (attachment, public proclamation via drum-beating, and publication) to claim priority.
The non-obstante clauses in Sections 31B and 26E of the SARFAESI Act ensure secured creditors’ priority over all other dues, including taxes.
In Writ Petition No. 5750 of 2026, the Sales Tax Department’s 2017 attachment order lacked CERSAI registration and evidence of proclamation compliance, rendering its claim subordinate to the bank’s dues.
In Writ Petition No. 5830 of 2026, the State Tax Department’s 14th October 2020 communication post-dated the amendment and was unregistered with CERSAI, thus failing to override the bank’s priority.
The Verdict
The Court allowed both writ petitions. It quashed the impugned orders dated 9th December 2013, 26th August 2017, and 14th October 2020, and directed the removal of mutation entries Nos. 187, 211, and 232 from the 7/12 extract of the secured asset. The respondents were ordered to comply within six weeks of the judgment.
What This Means For Similar Cases
CERSAI Registration Is Non-Negotiable
Tax authorities must register their charges with CERSAI to enforce priority over secured creditors post-24th January 2020.
Failure to register renders their claims unenforceable against a secured creditor’s registered interest.
Pre-Amendment Attachments Require Proclamation Compliance
For attachments issued before 24th January 2020, tax departments must prove compliance with MLRC proclamation requirements (attachment, public proclamation, and publication).
Without such proof, secured creditors retain priority under Section 26E of the SARFAESI Act.
Secured Creditors’ Priority Is Absolute
The non-obstante clauses in Sections 31B and 26E of the SARFAESI Act ensure that secured creditors’ dues take precedence over all other claims, including taxes, cesses, and revenues.