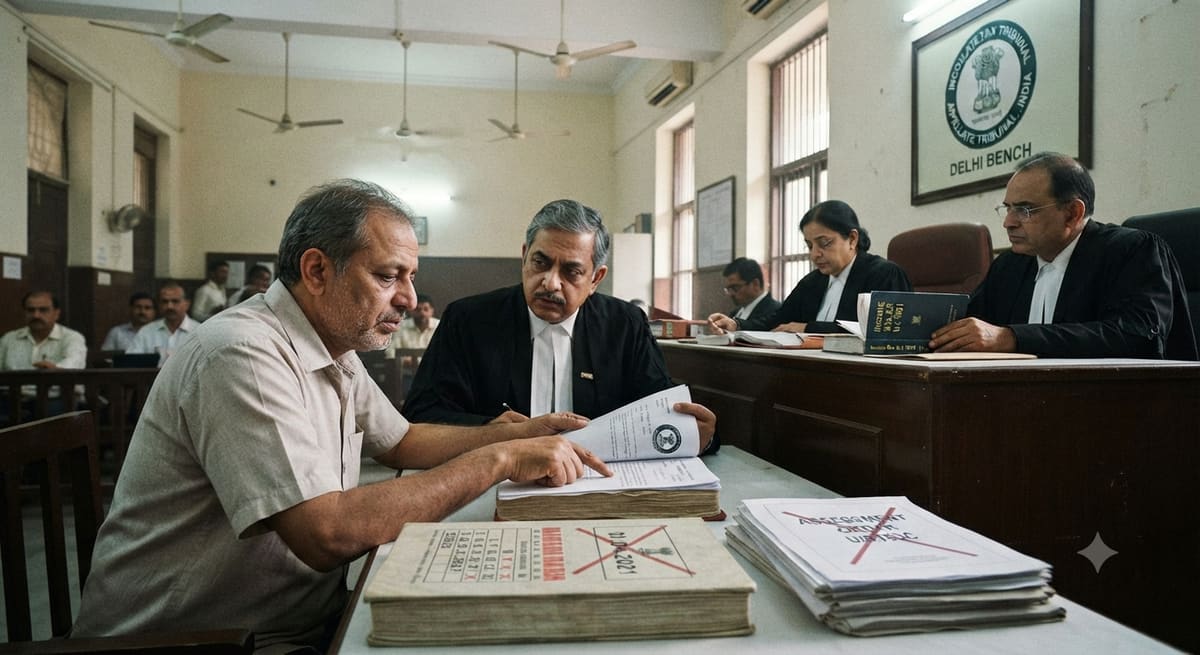
The Income Tax Appellate Tribunal, Delhi, has invalidated assessments under Section 153C of the Income-tax Act, 1961, where the deemed date of search falls on or after 01.04.2021, affirming that the Finance Act, 2021, prospectively bars such proceedings. This ruling clarifies the temporal applicability of a critical anti-evasion provision and sets a binding precedent for similar cases.
Background & Facts
The Dispute
The appellant, M/s Abhisar Estates Private Limited, faced three assessment proceedings under Section 153C of the Income-tax Act, 1961, for assessment years 2014-15 to 2016-17. These proceedings were triggered by incriminating material seized during a search conducted under Section 132 in the case of Alankit Group on 18.10.2019. The Assessing Officer (AO) of the appellant recorded a satisfaction note on 10.05.2022, following which a notice under Section 153C was issued on 27.05.2022, leading to the impugned assessments.
Key Facts
- Search under Section 132 conducted in the case of Alankit Group on 18.10.2019
- Seized documents and cash payment records (Rs. 4,91,830) relating to the appellant were forwarded to the AO of the appellant
- The AO recorded satisfaction under Section 153C(1) on 10.05.2022
- Notice under Section 153C issued to the appellant on 27.05.2022
- Assessment orders passed for A.Y. 2014-15 to 2016-17 on the basis of the above notice
- The appellant challenged the validity of these assessments before the Principal Commissioner of Income Tax (Appeals)-25, Delhi, which upheld them on 29.09.2025
- The appellant filed three appeals before the ITAT Delhi on 01.10.2025
- The ITAT delivered a prior order on 10.02.2026 in ITA No. 733/Del/2025 (A.Y. 2017-18) on identical facts, holding Section 153C inapplicable post 01.04.2021
Procedural History
- 18.10.2019: Search conducted under Section 132 in case of Alankit Group
- 10.05.2022: AO recorded satisfaction note under Section 153C(1)
- 27.05.2022: Notice issued to appellant under Section 153C
- 29.09.2025: PCIT(A) upheld the assessments
- 01.10.2025: Appeals filed before ITAT Delhi (ITA Nos. 7003 to 7005/Del/2025)
- 21.04.2026: Hearing concluded; order pronounced
- 29.04.2026: Order dated and signed by members
The Parties' Positions
For the Appellant
The appellant contended that the deemed date of search under Section 153C(1) is the date of recording satisfaction (10.05.2022), as the actual date of receipt of seized material by the AO was not available in the record. Since this date is after 01.04.2021, the newly inserted Section 153C(3) bars any assessment under Section 153C. The appellant relied on the Tribunal’s own order in Geetanjali Bhayana v. DCIT (183 taxmann.com 95) and the Madras High Court’s decision in Hargovind v. ACIT (180 taxmann.com 197).
For the Respondent
The Department argued that the search was initiated on 18.10.2019, prior to 01.04.2021, and therefore Section 153C(3) does not apply. It contended that the amendment is prospective only in relation to searches initiated on or after 01.04.2021, not the date of satisfaction or notice. It also cited Commissioner of Customs v. Dilip Kumar and Company (2018) 9 SCC 1 to argue that coordinate bench decisions are not binding.
Relief Sought
The appellant sought quashing of the three impugned assessments under Section 153C for A.Y. 2014-15 to 2016-17, on the ground that they were void ab initio due to non-compliance with Section 153C(3). All other grounds were rendered academic.
The Legal Issue
The central question was whether Section 153C of the Income-tax Act, 1961, permits an assessment to be made where the deemed date of search under the first proviso to Section 153C(1) is on or after 01.04.2021, in light of the newly inserted Section 153C(3) by the Finance Act, 2021.
Arguments Presented
For the Appellant
The appellant’s counsel argued that the first proviso to Section 153C(1) deems the date of recording satisfaction by the AO as the date of search when the actual receipt date of seized material is unavailable. Since satisfaction was recorded on 10.05.2022, the search is deemed to have occurred after 01.04.2021. Section 153C(3) explicitly bars assessments under Section 153C in relation to searches initiated on or after that date. The appellant relied on Geetanjali Bhayana and Hargovind v. ACIT, both of which held that the amendment is not merely procedural but substantive and prospective. The Tribunal’s own prior order in A.Y. 2017-18 affirmed this interpretation.
For the Respondent
The Department contended that the search under Section 132 was initiated on 18.10.2019, which predates 01.04.2021, and therefore the amendment does not apply. It argued that Section 153C(3) only restricts searches initiated on or after 01.04.2021, not the subsequent procedural steps like satisfaction or notice. It further argued that coordinate bench decisions are not binding under the doctrine of precedent and that the Tribunal should not be bound by its own earlier ruling in a different assessment year.
The Court's Analysis
The Tribunal examined the language of Section 153C(3), inserted by the Finance Act, 2021, which states: "Nothing contained in this section shall apply in relation to a search initiated under section 132 or books of account, other documents or any assets requisitioned under section 132A on or after the 1st day of April, 2021."
The Tribunal noted that the phrase "search initiated" must be interpreted in light of the first proviso to Section 153C(1), which provides that in the case of an "other person," the date of search is either the date of receipt of seized material by the AO or, if unavailable, the date of recording satisfaction. The Tribunal relied on Ojjas Healthcare Pvt. Ltd. (161 taxmann.com 160) to confirm that in the absence of evidence of receipt, the satisfaction date is deemed the search date.
"The provisions of Sub-Section (3) of Section 153C states that... if the search is initiated subsequent to 01.04.2021, the provision of Section 153C will not apply and accordingly, no proceedings can be initiated against the other person."
The Tribunal held that the Madras High Court’s interpretation in Hargovind v. ACIT was persuasive and consistent with the statutory language. It further noted that the Department did not dispute the applicability of the first proviso or the deemed date of search. The Tribunal emphasized that judicial consistency demands adherence to its own prior decision in the appellant’s case for A.Y. 2017-18, delivered on 10.02.2026, which had already settled the issue on identical facts.
While acknowledging the Department’s reliance on Commissioner of Customs v. Dilip Kumar, the Tribunal distinguished that case as involving a different statutory context and held that in tax matters, consistency in interpretation across similar factual matrices is essential to ensure fairness and predictability.
The Verdict
The appellant succeeded. The ITAT Delhi quashed the three impugned assessments under Section 153C for A.Y. 2014-15 to 2016-17, holding that the deemed date of search (10.05.2022) falls after 01.04.2021, rendering the proceedings void under Section 153C(3). All other grounds were rendered academic. The order was pronounced on 21.04.2026 and signed on 29.04.2026.
What This Means For Similar Cases
Deemed Search Date Controls Applicability of Section 153C
- Practitioners must now calculate the deemed date of search under the first proviso to Section 153C(1) - not the actual search date - to determine if Section 153C applies
- If satisfaction is recorded on or after 01.04.2021, the assessment is invalid regardless of when the original search occurred
- This applies even if the search under Section 132 was conducted years earlier
Precedent Binding Within Same Assessee’s Cases
- Tribunals are bound by their own prior rulings on identical facts involving the same assessee, even if not binding as stare decisis on other cases
- This creates a strong procedural advantage for taxpayers who have previously succeeded on this issue in any assessment year
- Counsel should cite prior favorable orders from the same tribunal as persuasive authority in pending cases
Procedural Compliance Is Non-Negotiable
- The Department cannot rely on the initiation date of the original search to justify Section 153C proceedings if the deemed date falls post-01.04.2021
- Any assessment based on a notice issued after 01.04.2021, where satisfaction was recorded on or after that date, is liable to be quashed
- Taxpayers should challenge such assessments at the first opportunity, even if the underlying search predates the amendment