The Himachal Pradesh High Court has set aside a conviction under Section 138 of the Negotiable Instruments Act after holding that a multi-city cheque presented at a non-home branch with an amount exceeding the RBI-prescribed cap is legally void. This ruling clarifies that compliance with RBI’s cheque policy is not optional but mandatory for enforceability, and failure to adhere to it defeats the very foundation of a Section 138 prosecution.
Background & Facts
The Dispute
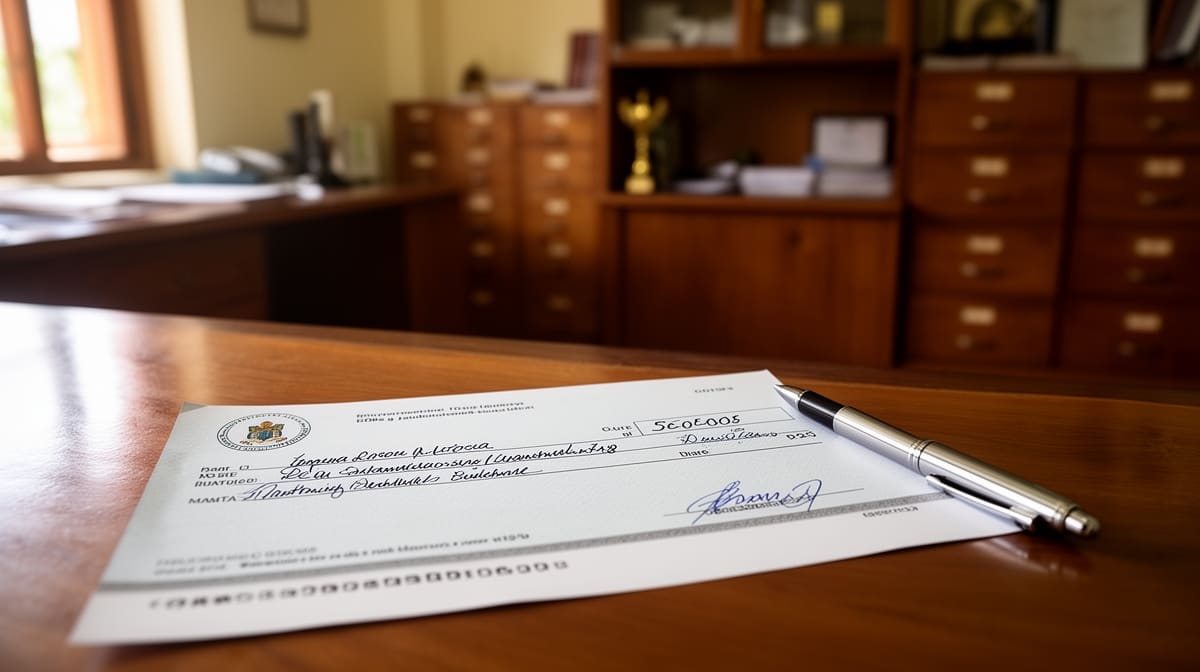
The complainant, Anuj Kumar, filed a complaint against the accused, Vinod Sipahiya, alleging that the accused had borrowed ₹1,50,000 on 10.09.2011 and issued a post-dated cheque No. 613701 dated 19.12.2011 for the same amount as security. The cheque was drawn on State Bank of India, Palampur, and presented by the complainant at the State Bank of India branch in Ghorab (Nagrota Bagwan), which is a non-home branch. The cheque was dishonoured with the endorsement "insufficient funds". A legal notice dated 15.01.2015 was issued and received by the accused, who failed to make payment. The complainant then filed a criminal complaint under Section 138 NI Act read with Section 420 IPC.
Key Facts
- The accused admitted in his statement under Section 313 CrPC that he had taken a loan of ₹1,50,000 and issued three cheques as security.
- The cheque in question (Ex.C6) bore the legend: "Valid for ₹50,000/- and under".
- The cheque was presented at Ghorab branch, while the drawee branch was Palampur - making it a non-home branch transaction.
- The complainant, Anuj Kumar (CW2), admitted in cross-examination that the accused had handed over three blank cheques as security.
- The complainant filled the amount as ₹1,50,000 on a cheque that was capped at ₹50,000 for non-home branch presentation.
- The accused claimed he had repaid ₹1,20,000 and owed only ₹30,000, but produced no evidence to substantiate this.
- The accused denied receiving the legal notice, but the Trial Court accepted service based on postal records.
Procedural History
- 10.09.2011: Loan of ₹1,50,000 advanced by complainant; cheque issued as security.
- 19.12.2011: Cheque dated for payment, but presented on 15.01.2015.
- 15.01.2015: Cheque presented at non-home branch (Ghorab) and dishonoured.
- 15.01.2015: Legal notice issued under Section 138 NI Act.
- 20.02.2015: Complaint filed before Judicial Magistrate First Class, Kangra (Criminal Case No. 158-III/2015).
- 15.02.2024: Trial Court convicted accused under Section 138 NI Act; sentenced to 2 months simple imprisonment and ₹3,00,000 compensation.
- 01.10.2024: Additional Sessions Judge-I, Kangra, dismissed appeal and upheld conviction.
- 08.04.2026: Revision petition decided by Himachal Pradesh High Court.
The Parties' Positions
For the Accused (Petitioner): Argued that the cheque was void because it exceeded the ₹50,000 cap for non-home branch presentation under RBI’s Multi-City Cheque (CTS-2010) Policy. The complainant had misused blank cheques by filling in an amount beyond the permitted limit. The plea was raised during cross-examination of the complainant and thus was part of the record.
For the Complainant (Respondent): Contended that the cheque was dishonoured for "insufficient funds", not for invalidity, and that the plea of exceeding the cap was raised for the first time in revision, making it impermissible.
Relief Sought
The accused sought quashing of the conviction and sentence under Section 138 NI Act, acquittal, and dismissal of all pending applications.
The Legal Issue
Whether a multi-city cheque presented at a non-home branch with an amount exceeding the RBI-prescribed cap of ₹50,000, as explicitly stated on the face of the cheque, can form the basis of a prosecution under Section 138 of the Negotiable Instruments Act?
Arguments Presented
For the Appellant/Petitioner
Counsel for the accused relied on the Reserve Bank of India’s Policy on Multi-City (Payable at Par) CTS-2010 Standard Cheques, specifically Clause 4 and Clause 6, which mandate that payment at non-home branches is restricted to the amount specified on the cheque. He argued that the cheque, being capped at ₹50,000, became void for any amount above that when presented at a non-home branch. He further submitted that the complainant’s act of filling ₹1,50,000 on a cheque with a ₹50,000 cap amounted to material alteration, rendering the instrument invalid. The plea was not new - it was specifically suggested during cross-examination of the complainant, and the lower courts’ failure to consider it constituted a jurisdictional error.
For the Respondent/State
Counsel for the complainant argued that the cheque was dishonoured for "insufficient funds", not for invalidity, and that the defence of exceeding the cap was not raised before the Trial Court or Appellate Court. He relied on the principle that revisional courts cannot entertain new pleas not raised below. He further contended that the concurrent findings of two courts on the existence of debt and dishonour should not be disturbed.
The Court's Analysis
The High Court began by emphasizing the limited scope of revisional jurisdiction under Section 397 CrPC, citing Malkeet Singh Gill v. State of Chhattisgarh, State of Gujarat v. Dilipsinh Kishorsinh Rao, and Kishan Rao v. Shankargouda. It held that revisional courts cannot reappreciate evidence or substitute their view for that of concurrent findings unless there is a patent defect, jurisdictional error, or perversity.
However, the Court found that the issue of the cheque’s validity under RBI policy was not merely a factual dispute but a question of law - whether an instrument that violates a binding statutory directive can be the subject of a criminal prosecution. The Court noted that the RBI’s policy, issued under Section 21 and Section 35-A of the Banking Regulation Act, 1949, is binding on all banking companies. The Supreme Court in Pro Knits v. Canara Bank had affirmed this binding nature.
"The payment of MCCs at a non-home branch will be restricted as per the limit of the Cheque (as per the legend mentioned on the Cheque as narrated hereinabove)."
The Court held that the cheque bore a clear legend: "Valid for ₹50,000/- and under". When presented at a non-home branch (Ghorab) for ₹1,50,000, it violated the RBI’s policy. The instrument, therefore, was not merely dishonoured - it was legally unenforceable for the amount claimed. The Court distinguished this from a mere "insufficient funds" scenario, noting that the bank’s refusal was not due to lack of balance but due to regulatory non-compliance.
The Court further held that the plea was not new. It was specifically raised during cross-examination of the complainant, who admitted the accused had issued three cheques of ₹50,000 each as security. The lower courts’ failure to consider this material fact - which rendered the instrument void - amounted to a jurisdictional error. The Court relied on Boston Beverages Pvt. Ltd. v. Kingston Beverages to affirm that non-compliance with RBI’s multi-city cheque policy invalidates the instrument for presentation beyond the cap.
The Court concluded that a void instrument cannot give rise to a criminal offence under Section 138 NI Act, as the essential ingredient of a legally enforceable debt or liability is absent. The conviction, therefore, was unsustainable.
The Verdict
The revision petition is allowed. The judgment of conviction and sentence dated 15.02.2024 by the Judicial Magistrate First Class, Kangra, and the order dated 01.10.2024 by the Additional Sessions Judge-I, Kangra, are set aside. The accused is acquitted of the offence under Section 138 of the NI Act. The accused is directed to furnish bail bonds of ₹50,000 with one surety of like amount to the satisfaction of the Registrar (Judicial) or the Trial Court, effective for six months. Pending miscellaneous applications are disposed of.
What This Means For Similar Cases
A Cheque Exceeding RBI Cap Is Void - Not Just Dishonoured
- Practitioners must now examine the face of every multi-city cheque for RBI-mandated caps before filing a Section 138 complaint.
- A dishonour due to regulatory violation (e.g., exceeding cap) is not equivalent to "insufficient funds" - it negates the existence of a legally enforceable liability.
- Prosecutions based on cheques with caps exceeding the presented amount are liable to be quashed at any stage.
Revisional Courts Can Intervene on Jurisdictional Errors Involving Statutory Compliance
- Even if a plea is not explicitly raised as a defence, if it is suggested during cross-examination and relates to a binding statutory directive (like RBI policy), revisional courts may consider it.
- Failure to appreciate such a material legal defect constitutes a jurisdictional error, not merely an error of appreciation.
- This opens the door for challenging convictions where the instrument’s validity is compromised by regulatory non-compliance.
Documentary Compliance Trumps Oral Admissions
- An accused’s admission of debt does not cure a void instrument. The cheque’s validity is a threshold legal requirement.
- Courts must now conduct a dual analysis: (1) existence of debt, and (2) validity of the instrument under applicable banking regulations.
- Practitioners should include RBI policy compliance as a mandatory checklist in all Section 138 cases involving multi-city cheques.