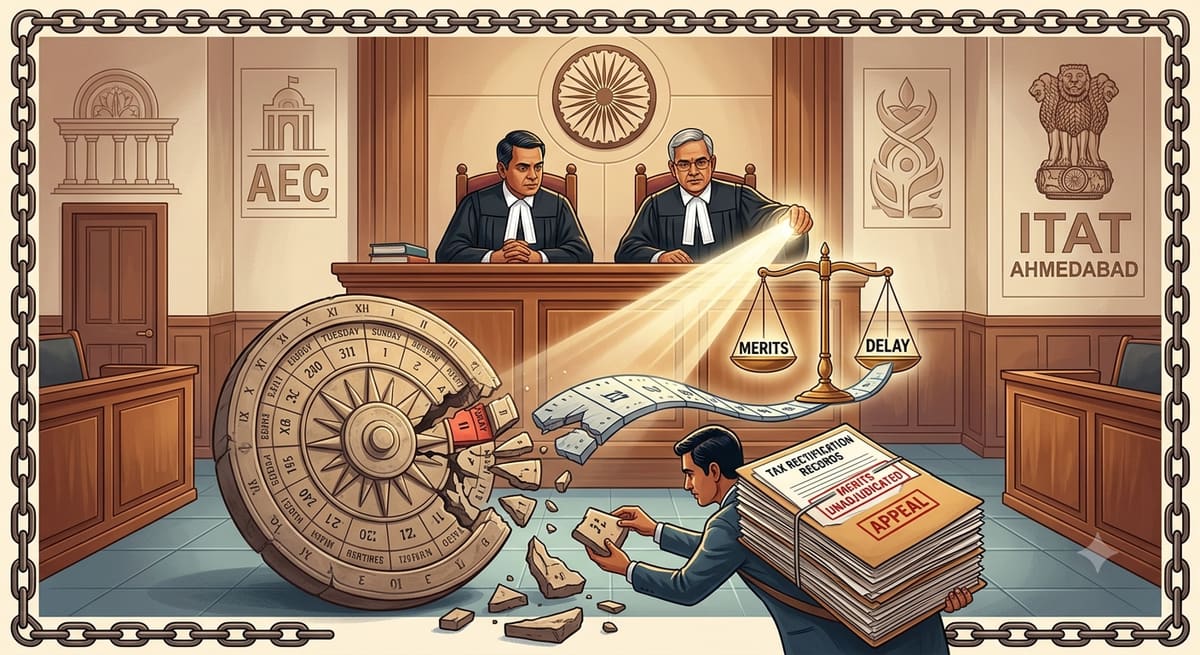
The ITAT Ahmedabad has clarified that the enhanced tax rate of 60% under Section 115BBE of the Income-tax Act, 1961, applies prospectively from Assessment Year 2018-19 and cannot be applied retrospectively to transactions occurring before 01.04.2017. This ruling reinforces the principle that rectification under Section 154 cannot be used to resolve debatable questions of law, especially where judicial precedents consistently support the taxpayer’s position.
Background & Facts
The Dispute
The dispute arose from the Assessing Officer’s rectification order dated 21.10.2024, which increased the tax rate on an addition of Rs. 1,40,76,000 made under Section 69A from 30% to 60%, citing the amendment to Section 115BBE introduced by the Taxation Laws (Amendment) Act, 2016. The assessee, Udayan Mandavia, challenged this rectification before the Commissioner of Income Tax (Appeals), arguing that the amendment was prospective and that the rectification violated principles of natural justice.
Key Facts
- The assessee is an individual engaged in business activities.
- An addition of Rs. 1,40,76,000 was made under Section 69A for A.Y. 2017-18, relating to unexplained cash deposits.
- The original assessment was completed under Section 147 read with Section 144B, applying a 30% tax rate under Section 115BBE as it stood prior to the amendment.
- The Taxation Laws (Amendment) Act, 2016, amended Section 115BBE to increase the tax rate from 30% to 60%, effective from 01.04.2017.
- The Assessing Officer, on 21.10.2024, issued a rectification order under Section 154 to apply the 60% rate to the addition, claiming it was a mistake apparent from record.
- The assessee received no show cause notice, email, or e-proceedings portal intimation regarding the rectification; knowledge was gained only via SMS.
- The assessee’s pre-regularization transactions occurred prior to 01.04.2017.
Procedural History
- 21.10.2024: Assessing Officer passed rectification order under Section 154, increasing tax rate from 30% to 60%.
- 28.11.2025: Ld. CIT(A) quashed the rectification order, holding the issue debatable and beyond Section 154’s scope.
- 24.03.2026: Hearing before ITAT Ahmedabad.
- 26.03.2026: ITAT pronounced order dismissing the Department’s appeal.
The Parties' Positions
For the Department (Appellant)
- Argued that the original assessment applied the wrong tax rate, and the rectification under Section 154 was a mere correction of a clerical or arithmetical error.
- Contended that the amendment to Section 115BBE was clear and mandatory, and its application to A.Y. 2017-18 was not open to interpretation.
- Relied on the literal wording of the amendment, asserting that the effective date of 01.04.2017 meant it applied to all assessments for A.Y. 2017-18, regardless of transaction date.
For the Assessee (Respondent)
- Argued that the amendment was prospective and could not be applied to transactions occurring before 01.04.2017.
- Relied on judicial precedents from the Madras High Court and other Tribunals holding that the 60% rate applies only from A.Y. 2018-19.
- Asserted that Section 154 cannot be used to resolve legal disputes requiring interpretation.
- Raised violation of natural justice due to non-service of notice.
Relief Sought
The Department sought to set aside the CIT(A)’s order and restore the rectification order dated 21.10.2024, thereby enforcing the 60% tax rate on the addition of Rs. 1,40,76,000. The assessee sought confirmation of the CIT(A)’s order and dismissal of the appeal.
The Legal Issue
The central question was whether Section 154 of the Income-tax Act permits rectification of an assessment to apply the amended 60% tax rate under Section 115BBE for Assessment Year 2017-18, where the underlying transactions occurred before 01.04.2017, and whether the applicability of the amendment is a debatable issue of law beyond the scope of rectification.
Arguments Presented
For the Appellant
The Department contended that the amendment to Section 115BBE was unambiguous and effective from 01.04.2017, making the 60% rate applicable to all assessments for A.Y. 2017-18. It argued that the original application of 30% was a clear mistake apparent from record, and rectification under Section 154 was a procedural necessity to ensure correct tax computation. The Department dismissed the reliance on judicial precedents as non-binding and urged the Tribunal to apply the plain language of the statute.
For the Respondent
The assessee argued that the amendment was not retrospective and that judicial authorities, including the Madras High Court and multiple Tribunals, had consistently held that the 60% rate applies only from A.Y. 2018-19. The assessee emphasized that Section 154 cannot be invoked to resolve legal controversies requiring interpretation, and that the absence of a show cause notice rendered the rectification invalid under principles of natural justice.
The Court's Analysis
The Tribunal undertook a comprehensive review of judicial precedents on the applicability of the amended Section 115BBE. It noted that the Hon’ble Madras High Court in S.M.I.L.E. Microfinance Ltd. v. ACIT [2025] 179 taxmann.com 65 had held:
"Therefore this Court is of the considered opinion that the revenue is empowered to impose 60% rate of tax for the transactions from 01.04.2017 onwards and not prior to the said cut-off date. And for prior transaction the revenue is empowered to impose only 30% rate of tax."
The Tribunal further cited the Ahmedabad Bench’s decision in Maranbhai Bharwad v. ITO (ITA No. 272/Ahd/2024), the Chennai Bench’s ruling in Jagathesh v. ACIT [2026] 182 taxmann.com 28, and the Surat Bench’s judgment in Reva Enterprises v. ITO [2025] 180 taxmann.com 767 - all of which uniformly held that the 60% rate does not apply to A.Y. 2017-18.
The Tribunal emphasized that Section 154 is confined to correcting mistakes apparent from the record and cannot be used to resolve issues requiring legal interpretation. It observed:
"Once this position is accepted, the very foundation of the rectification order passed under section 154 collapses."
The Tribunal also accepted the assessee’s contention regarding violation of natural justice, noting the absence of any formal notice or opportunity to be heard prior to the rectification. It held that the existence of multiple judicial opinions on the issue rendered it inherently debatable, thereby excluding it from the purview of Section 154.
The Verdict
The Department’s appeal was dismissed. The ITAT upheld the order of the Ld. CIT(A) quashing the rectification order dated 21.10.2024. The addition of Rs. 1,40,76,000 under Section 69A shall be taxed at the pre-amended rate of 30% under Section 115BBE for A.Y. 2017-18. The Tribunal confirmed that the 60% rate applies only from A.Y. 2018-19 onwards. No further directions were issued as the matter was resolved on the merits.
What This Means For Similar Cases
Rectification Under Section 154 Cannot Resolve Legal Ambiguities
- Practitioners must now argue that any attempt to use Section 154 to change tax rates based on contested statutory interpretation is invalid.
- Where judicial precedents exist on the applicability of a provision, the issue is deemed debatable and outside Section 154’s scope.
- Tax officers must avoid unilateral rectifications on matters requiring legal interpretation - proceedings must be reopened under Section 147 if a change in interpretation is sought.
Prospective Application of Tax Amendments Is Now Firmly Established
- For A.Y. 2017-18, transactions occurring before 01.04.2017 must be taxed at 30% under Section 115BBE, even if the assessment was completed after the amendment.
- The effective date of 01.04.2017 refers to the financial year of the transaction, not the assessment year.
- Taxpayers with similar additions under Section 69A for A.Y. 2017-18 may now challenge rectification orders and seek refunds of excess tax paid.
Natural Justice Requires Formal Notice for Rectification
- Any rectification order altering tax liability must be preceded by a show cause notice.
- Reliance on SMS or e-proceedings portal notifications alone is insufficient to satisfy the requirement of hearing.
- Failure to serve notice renders the rectification order void ab initio, regardless of the correctness of the substantive change.