The Income Tax Appellate Tribunal, Ahmedabad, has reaffirmed that procedural technicalities must yield to substantial justice when a taxpayer’s substantive challenge to a tax addition remains pending before the First Appellate Authority. In a significant ruling, the Tribunal condoned a delay of 485 days in filing an appeal against a rectification order, recognizing that the core legal issue - applicability of Section 56(2) - was already under adjudication in a separate appeal.
Background & Facts
The Dispute
The appellant, Bharat Bheraji Barot, faced an income tax assessment for the Assessment Year 2020-2021, wherein the Assessing Officer initially made an addition of Rs. 1,25,98,300 under Section 56(2) of the Income Tax Act, 1961, treating certain sums as unexplained income. Subsequently, upon receipt of the District Valuation Officer’s report, the Assessing Officer passed a rectification order under Section 154 on 20.12.2022, reducing the addition to Rs. 42,00,000. The appellant did not file an appeal against the original assessment order dated 24.09.2022, believing that the rectification proceedings were a continuation of the assessment process under Section 143(3). Instead, he filed an appeal only against the rectification order dated 20.12.2022.
Key Facts
Original Assessment Order under Section 143(3): 24.09.2022 (addition of Rs. 1,25,98,300)
Rectification Order under Section 154: 20.12.2022 (addition reduced to Rs. 42,00,000)
Appeal filed against Rectification Order: Before CIT(A)
CIT(A) Order: 27.09.2024 (dismissed appeal ex parte for non-filing of submissions)
Appellant’s explanation: Financial hardship prevented engagement of professional; appeal filed only after financial recovery
Delay in filing appeal before ITAT: 485 days from 27.09.2024 to 23.02.2026
Fresh appeal against original Assessment Order under Section 143(3): Filed on 20.03.2026 before CIT(A), challenging applicability of Section 56(2)
Appellant’s representation: Rectification appeal was premature; core issue now pending in fresh appeal
Procedural History
24.09.2022: Assessment Order passed under Section 143(3) by Assessing Officer
20.12.2022: Rectification Order passed under Section 154, reducing addition to Rs. 42,00,000
27.09.2024: CIT(A) dismissed appeal against rectification order ex parte for non-submission of grounds
23.02.2026: Appeal filed before ITAT challenging CIT(A)’s order
20.03.2026: Fresh appeal filed before CIT(A) against original Assessment Order under Section 143(3)
23.06.2026: Hearing concluded before ITAT
30.06.2026: Judgment pronounced
The Parties' Positions
For the Appellant
Argued that the rectification order was not a standalone order but part of ongoing assessment proceedings
Contended that the delay in filing appeal before ITAT was due to genuine financial hardship, not mala fide intent
Highlighted that a fresh appeal challenging the applicability of Section 56(2) had already been filed before CIT(A) on 20.03.2026
Submitted that the CIT(A)’s ex parte dismissal was unjust, as the appellant had no opportunity to present submissions
Requested condonation of delay and restoration of the appeal to CIT(A) for de novo adjudication in light of the pending assessment appeal
For the Respondent/Department
Did not contest the request for condonation of delay
Supported the CIT(A)’s order on merits, asserting no infirmity in the rectification or the ex parte dismissal
Maintained that the appeal against the rectification order was legally distinct and could not be merged with the assessment appeal
Relief Sought
The appellant sought:
Condonation of 485-day delay in filing the appeal before ITAT
Setting aside of the CIT(A)’s ex parte order dated 27.09.2024
Restoration of the appeal to the CIT(A) for fresh adjudication, to be heard alongside the pending appeal against the original assessment order
The Legal Issue
Can a delay in filing an appeal against a rectification order under Section 154 be condoned when the substantive issue - applicability of Section 56(2) - is already under adjudication in a separate appeal against the original assessment order, and the appellant has demonstrated a bona fide reason for the delay?
Arguments Presented
For the Appellant
The appellant relied on the Supreme Court’s decision in Collector of Land Acquisition v. Mst. Katiji & Others (AIR 1987 SC 1353), which holds that substantial justice must prevail over technicalities. It was argued that the appellant’s belief that rectification was part of the assessment process was reasonable, and the delay was neither intentional nor prejudicial to the department. The filing of a fresh appeal against the original assessment order rendered the CIT(A)’s reasoning on the rectification appeal obsolete. The appellant sought an opportunity to present full submissions on the merits of Section 56(2), which was now the central issue.
For the Respondent
The Department did not oppose condonation of delay but defended the CIT(A)’s order on procedural grounds. It contended that the rectification order was a distinct statutory action and that the appellant’s failure to file submissions warranted dismissal. The Department maintained that the appeal against the rectification order could not be merged with the appeal against the assessment order, even if the same legal issue was raised.
The Court's Analysis
The Tribunal acknowledged that while procedural compliance is essential, rigid adherence to timelines must not defeat the ends of justice. It emphasized that the appellant had not sought to gain any advantage from the delay, nor had the department suffered prejudice. The Court noted that the appellant had acted promptly once financially able, filing the appeal before the Tribunal within months of engaging counsel.
"Every day's delay must be explained does not mean that a pedantic approach should be taken and that the aforesaid doctrine must be applied in a rational, common sense and pragmatic manner, more so in circumstances where a litigant does not stand to benefit by lodging the appeal late."
The Tribunal further observed that the CIT(A) had dismissed the appeal ex parte without affording the appellant any opportunity to be heard, which violated the principles of natural justice. Crucially, the Tribunal noted that the core legal issue - whether the sum in question was taxable under Section 56(2) - was now being litigated in the fresh appeal against the original assessment order. The CIT(A)’s earlier reasoning, which confined the dispute to the cost of acquisition, was rendered irrelevant by this development.
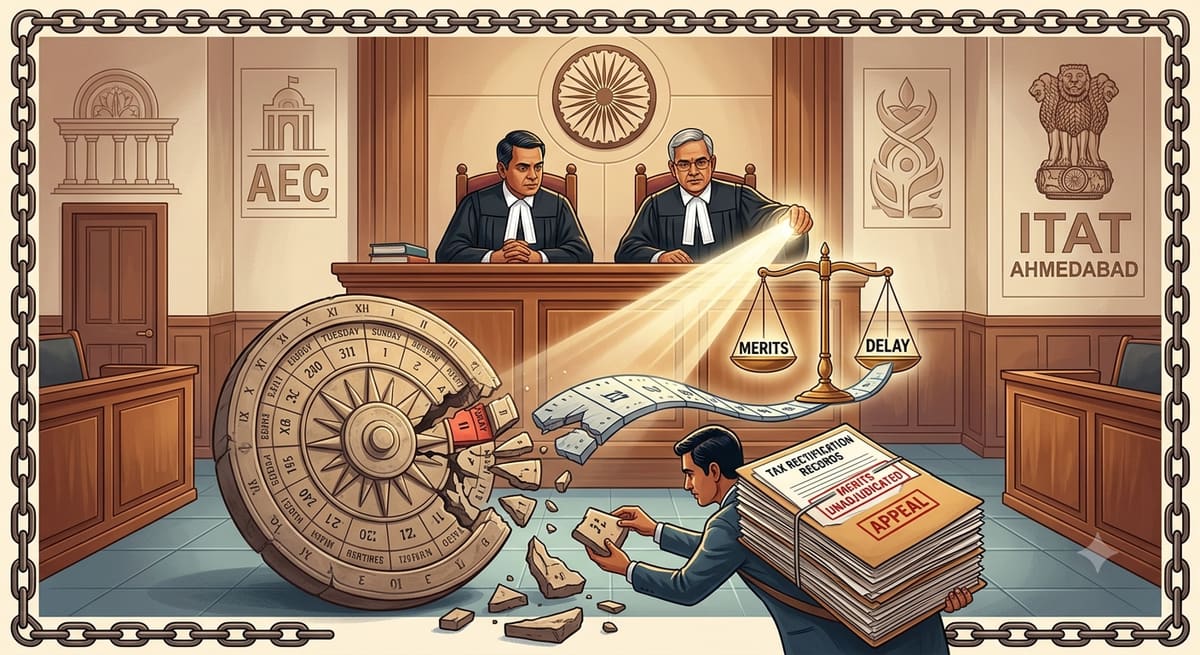
The Court held that allowing the appeal to proceed on its merits before the CIT(A), alongside the pending assessment appeal, would serve the interests of justice, avoid multiplicity of proceedings, and ensure a coherent adjudication of the same legal question. The Tribunal concluded that the appellant’s explanation for delay was reasonable and bona fide, and that the doctrine of substantial justice mandated condonation.
The Verdict
The appeal was allowed for statistical purposes. The Tribunal condoned the delay of 485 days in filing the appeal against the CIT(A)’s order. The ex parte order dated 27.09.2024 was set aside. The matter was restored to the file of the CIT(A) for de novo adjudication, to be heard jointly with the appeal filed on 20.03.2026 against the original assessment order. The appellant was granted a full opportunity to be heard in accordance with law. No costs were awarded.
What This Means For Similar Cases
Delay in Filing Appeals Can Be Condoned When Substantive Issues Are Pending
Practitioners may now seek condonation of delay in appeals against rectification orders if the core legal issue is already under adjudication in a related appeal against the original assessment
Courts will consider the litigant’s conduct, financial constraints, and absence of prejudice to the department
A fresh appeal on the same issue renders prior ex parte dismissals legally untenable
Rectification Orders Are Not Isolated; Context Matters
A rectification order under Section 154 is not a standalone adjudication but a correction within the assessment framework
Taxpayers who mistakenly treat rectification as part of ongoing assessment proceedings may still access appellate remedies if they act promptly upon realizing the error
The Tribunal’s approach signals a shift toward functional integration of related proceedings
Natural Justice Requires Hearing Before Dismissal
Ex parte dismissals of appeals without affording opportunity to file submissions are vulnerable to being set aside
Even if delay is apparent, failure to provide hearing violates fundamental principles
Practitioners should always raise violation of natural justice as a ground, even if delay is conceded